Sintra Freezes Property Tax at Legal Minimum of 0.30%: Key Fiscal Relief for Foreign Real Estate Investors
By Nikola Zdraveski
Published: October 15, 2026
Category: politics
### Sintra Freezes Property Tax at Legal Minimum of 0.30%: Key Fiscal Relief for Foreign Real Estate Investors
In a significant fiscal policy decision for **Sintra**'s real estate ecosystem, the **Câmara Municipal de Sintra** has formally approved the preservation of its municipal tax regime for 2027, maintaining the benchmark Imposto Municipal sobre Imóveis (IMI) at the statutory minimum rate of 0.30%. This definitive resolution underscores the local administration's structured commitment to curbing holding expenses for homeowners while systematically strengthening the municipality's competitive standing against peer sub-markets across the Greater Lisbon region.
### Key Takeaways
• ✓ Sintra municipal council locks urban property tax (IMI) at Portugal's legal floor of 0.30% for 2027
• ✓ Municipal corporate derrama capped at 1.5% alongside complete exemption for enterprises grossing under €150,000
• ✓ Stable local taxation provides predictable overhead costs and bolsters net yield forecasts for residential landlords
• ✓ Strategic local policy reinforces foreign investor confidence across Greater Lisbon's premier commuter and luxury enclaves
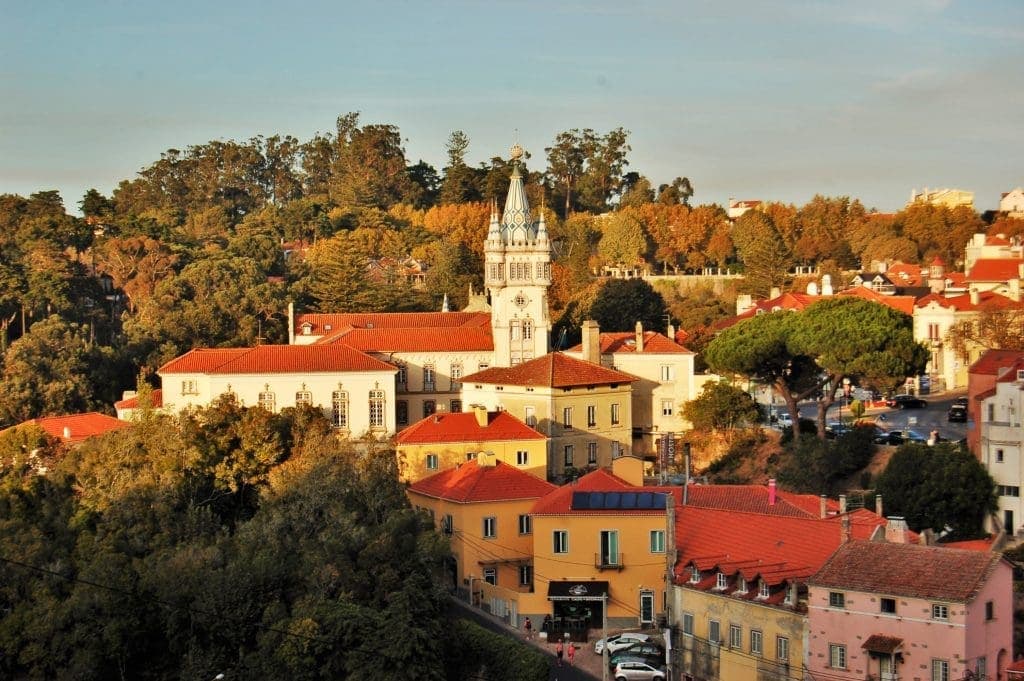
The municipality of Sintra represents one of Portugal's most economically dynamic and geographically extensive jurisdictions, extending from suburban commuter junctions along the IC19 corridor to prestigious rural estates situated within the UNESCO World Heritage cultural landscape. Prime enclaves including São Pedro de Sintra, Colares, and the coastal stretches bordering Praia das Maçãs command substantial interest from international high-net-worth individuals, while urban nodes such as Queluz, Rio de Mouro, and Massamá provide crucial housing infrastructure for Lisbon's expanding white-collar workforce.
Geographic positioning between Lisbon's western commercial districts and the upscale coastal communities of Cascais and Oeiras places Sintra at the center of institutional and residential expansion. By fixing annual holding costs at the statutory basement of 0.30%—contrasting sharply with municipalities that exercise their statutory authority to charge up to 0.45%—local governance actively protects property yields, establishing an enduring incentive for international purchasers seeking capital security and long-term appreciation in the Portuguese real estate market.
Strategic connectivity through the modern A16 and A37 motorways, coupled with suburban passenger rail networks connecting directly to Rossio and Oriente stations, ensures that residential assets in Sintra remain highly connected to Lisbon's core employment hubs. This physical infrastructure, combined with disciplined municipal fiscal parameters, ensures sustained demand from both overseas families seeking spacious family villas and portfolio investors targeting long-term tenant stability.
## Market Implications for Investors
The council's decision to preserve the 0.30% IMI ceiling delivers immediate quantitative advantages for residential landlords and commercial proprietors alike. Property holding taxation directly erodes net operating revenue; consequently, capping this statutory levy preserves margins across buy-to-let portfolios. Investors analyzing regional yields through our rental yield calculator [https://www.realestate-lisbon.com/calculators/rental-yield] can model lower fixed deductions, which proves instrumental when compounding returns over multi-year holding horizons.
Beyond baseline property levies, the municipal resolution maintains the municipal share of Personal Income Tax (IRS) at 3.5%, leaving measurable liquidity within the local household economy. This structural retention mechanism enhances tenant affordability, lowers default risk, and supports steady rental indexation across mid-market residential units. Foreign nationals establishing residency can consult qualified Sintra accountants [https://www.realestate-lisbon.com/sintra/accountants] to structure their broader tax declarations under applicable resident tax frameworks.
For corporate entities and investment vehicles, the local corporate tax surcharge (derrama) remains capped at 1.5% for enterprises generating revenues exceeding €150,000, while firms below this revenue threshold retain complete exemption. This structure provides meaningful operational savings for boutique property management companies, co-living operators, and local developers managing localized investment SPVs. In-depth analysis of these corporate frameworks is detailed within our guide to financial concerns in Portuguese real estate [https://www.realestate-lisbon.com/buying-guide/financial-concerns].
The continuity of these municipal rates also shields property portfolios from arbitrary municipal budgetary shocks. In an inflationary European macroeconomic environment where local governments frequently raise property taxes to offset fiscal deficits, Sintra's demonstrated fiscal restraint reinforces broader institutional and foreign investor confidence across both prime historical manors and contemporary developments.
## Sintra Municipal Council's Fiscal Strategy
The **Câmara Municipal de Sintra** has established an intentional policy of competitive municipal taxation aimed at stimulating regional business formation and attracting private capital inflows. By prioritizing budgetary efficiency over rate increases, municipal leadership manages to balance municipal fiscal obligations while simultaneously reinforcing its reputation as an investor-friendly jurisdiction within Greater Lisbon.
This persistent stability serves as a key pillar in the municipality's broader economic development program. International asset managers and private family offices frequently review municipal track records before committing development capital, and Sintra's adherence to legal minimums provides a predictable regulatory environment that mitigates political and legislative execution risk.
## Sintra Residential and Commercial Market Context
Sintra's property sector demonstrates distinctive resilience, anchored by an enduring imbalance between strict planning restrictions and expanding international tenant demand. The municipality contains vast protected green reserves governed by the Sintra-Cascais Natural Park, which rigorously restricts speculative urban sprawl and places a premium on existing licensed residential stock and permitted restoration projects.
Several market dynamics are currently influencing transaction volumes and property pricing across the territory:
• **Tax Predictability**: Fixed 0.30% municipal IMI rates maintain predictable operating cash flows for private landlords and institutional holdings
• **Scarcity of Prime Stock**: Severe planning constraints within protected heritage corridors drive sustained price premiums for renovated traditional estates
• **Demographic Inflow**: Growing numbers of international expatriate families prioritize Sintra for its world-class international schools and tranquil microclimate
• **Off-Plan Demand**: Increased appetite for newly developed suburban townhouses and apartments, visible in new projects featured across off-plan properties in Sintra [https://www.realestate-lisbon.com/off-plan/sintra]
The interplay of these market forces ensures that capital allocated to prime Sintra real estate benefits from robust downside protection. As central Lisbon prime prices push institutional investors toward secondary ring markets, Sintra's combination of historical prestige, rapid rail links, and favorable tax burdens positions it as an exceptional beneficiary of decentralized capital flows.
Prospective purchasers must also evaluate local planning parameters prior to acquisition. Examining the municipal master plan through our analysis of the Sintra municipal master plan [https://www.realestate-lisbon.com/sintra/pdm] is critical to ensure that any proposed residential additions, guest annexes, or commercial conversions comply fully with current municipal zoning classifications.
## Investment Considerations
For cross-border investors assessing opportunities in Sintra, comprehensive financial modeling must incorporate both transactional entry costs and annual recurring obligations. When structuring an acquisition, calculating upfront property transfer levies through the IMT tax calculator [https://www.realestate-lisbon.com/calculators/imt] provides necessary clarity regarding immediate capitalization outlays. Furthermore, buyers can model the full acquisition cost — including IMT, stamp duty, and notary fees — using tools such as HomeOS's real cost calculator [https://www.homeos.pt/comprar/preco/custo-real/], which draws on cross-referenced registry data unavailable to general search tools.
Investors should also evaluate structural and legal due diligence requirements before executing binding promissory contracts (CPCV). Engaging independent professionals, such as certified Sintra real estate lawyers [https://www.realestate-lisbon.com/sintra/real-estate-lawyers] and vetted English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants], ensures that habitation licenses, property boundaries, and potential historical conservation encumbrances are meticulously vetted. Detailed advice on mitigating transaction liabilities is available within our comprehensive breakdown of legal issues in Portuguese property [https://www.realestate-lisbon.com/buying-guide/legal-issues].
Furthermore, purchasers evaluating older quintas or historic properties in Sintra's historical core must factor in periodic maintenance outlays, as outlined in our guide to property maintenance costs in Portugal [https://www.realestate-lisbon.com/buying-guide/maintenance-costs]. Balancing these maintenance considerations against the baseline 0.30% IMI rate allows investors to construct highly precise cash-flow forecasts for both private residence and luxury tourism rental models.
## Looking Ahead
The formal confirmation of Sintra's 2027 tax parameters establishes a transparent, highly advantageous operating climate for property owners and commercial entities over the coming years. While other European urban centres grapple with fiscal consolidation through real estate tax surcharges, Sintra's disciplined alignment with Portugal's lowest legal rates reinforces its status as a reliable jurisdiction for wealth preservation and capital deployment.
As international capital continues to prioritize markets characterized by legislative clarity, favorable lifestyle attributes, and prudent municipal administration, Sintra remains uniquely positioned to capture high-value property investment. For expert guidance on property acquisition, portfolio modeling, and navigating municipal frameworks in Sintra, contact realestate-lisbon.com [https://www.realestate-lisbon.com/].