Portugal to Revise Tax Haven Blacklist: Implications for Foreign Real Estate Investors
By Pieter Paul Castelein
Published: July 3, 2026
Category: legal-updates
### Reforming Portugal's Tax Blacklist: Strategic Implications for International Real Estate Structures
In a significant development for **Portugal**'s cross-border investment framework, the Portuguese Council of Ministers has approved a draft law authorizing a comprehensive revision of the criteria used to identify jurisdictions with "clearly more favorable tax regimes." This legislative initiative, aimed at modernizing the nation's historical tax haven blacklist, has profound implications for international investors who utilize corporate holding structures to acquire and manage Portuguese property. For those active in the high-end Lisbon real estate [https://www.realestate-lisbon.com/] market, this reform represents a major step toward aligning Portugal's tax policy with contemporary European Union standards.
### Key Takeaways
• ✓ Portuguese government initiates a legislative review to modernize its tax haven blacklist of 77 jurisdictions
• ✓ The reform seeks to eliminate punitive tax treatment for countries with active Double Taxation Treaties (DTTs)
• ✓ Entities in blacklisted jurisdictions currently face a flat 10% IMT and an aggravated 1% annual IMI on real estate
• ✓ The modernization is expected to unlock substantial capital flows from key Middle Eastern and global financial hubs
The current Portuguese blacklist is notoriously extensive, encompassing **77 jurisdictions**. This stands in stark contrast to the European Union's non-cooperative tax list, which identifies only ten. Crucially, the Portuguese list continues to include several sovereign states with which Portugal has active Double Taxation Treaties (DTTs) and robust tax information exchange agreements, such as the **United Arab Emirates**, **Qatar**, **Bahrain**, and **Panama**. Investors utilizing our legal issues guide [https://www.realestate-lisbon.com/buying-guide/legal-issues] frequently encounter significant structural hurdles due to these legacy listings.
For property acquisitions in Lisbon's prime residential and commercial sectors—including upscale districts like **Chiado**, **Lapa**, and **Avenidas Novas**—the tax consequences of using a blacklisted entity are exceptionally severe. These punitive measures were originally designed to deter tax evasion but have increasingly acted as a barrier to legitimate institutional and private wealth. By revising these criteria, the government aims to foster a more competitive business environment, a trend closely monitored in our legal updates news [https://www.realestate-lisbon.com/news/legal-updates].
Furthermore, the reform is expected to benefit the luxury residential markets of **Cascais** and **Sintra**, where international buyers often prefer to hold assets through corporate vehicles for estate planning and asset protection. Streamlining the blacklist will allow these buyers to utilize standard international corporate structures without facing discriminatory tax rates, thereby enhancing the liquidity and appeal of Portugal's premium property segments.
## Market Implications for Investors
The proposed tax blacklist reform carries substantial weight for those analyzing investment insights news [https://www.realestate-lisbon.com/news/investment-insights]. Under the current regime, any entity resident in a blacklisted jurisdiction, or controlled by residents of such a jurisdiction, is subject to aggravated property taxes. Specifically, these entities face a flat **IMT rate of 10%** on acquisitions, compared to standard progressive rates that top out at 7.5% for residential properties. Investors can calculate these potential liabilities using our IMT tax calculator [https://www.realestate-lisbon.com/calculators/imt].
This **market signal** indicates a strategic shift in Portugal's approach to attracting foreign direct investment. By removing countries like the UAE and Qatar from the blacklist, the government is effectively opening the door to sovereign wealth funds, family offices, and high-net-worth individuals who have historically avoided Portugal due to these tax penalties. This influx of global capital is expected to support valuations in the prime commercial and residential sectors, as discussed in our Portugal property market insights [https://www.realestate-lisbon.com/market-insights].
In addition to transaction-level taxes, blacklisted entities are subject to an annual **IMI rate of 1%**, which is significantly higher than the standard municipal rates of 0.3% to 0.45%. Over a multi-year holding period, this aggravated annual tax severely erodes net rental yields and overall return on investment (ROI). The removal of these penalties will dramatically improve the financial performance of properties held under these structures, a key consideration in our guide on financial concerns when buying property [https://www.realestate-lisbon.com/buying-guide/financial-concerns].
Finally, the reform will reduce administrative and legal friction during the acquisition process. Currently, transactions involving international corporate structures require exhaustive due diligence to verify that no beneficial owners are resident in blacklisted jurisdictions. A simplified blacklist will streamline this process, reducing transaction times and legal costs for buyers and sellers alike.
## Pedro Fugas's Expert Perspective
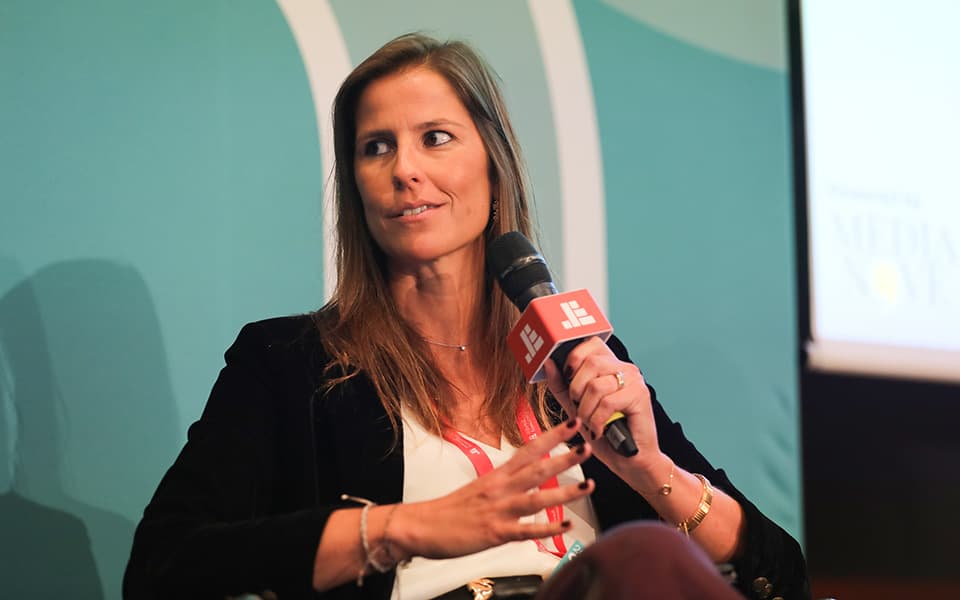
**Pedro Fugas**, a leading tax partner at KPMG, has long advocated for a thorough revision of Portugal's tax blacklist. Fugas argues that the current list is outdated and fails to reflect the realities of modern international tax cooperation. He notes that maintaining jurisdictions with active DTTs on the blacklist is a major contradiction that undermines Portugal's credibility in the global market.
Fugas highlights that Spain's recent modernization of its blacklist, which reduced the number of listed jurisdictions, has successfully enhanced its competitiveness without compromising tax revenues. By adopting a similar, risk-based approach, Portugal can protect its tax base while significantly improving its attractiveness to legitimate international capital. This expert analysis underscores the value of consulting with specialized English-speaking real estate lawyers [https://www.realestate-lisbon.com/english-speaking-lawyers] when structuring complex property acquisitions.
## The Broader Portuguese Tax and Regulatory Landscape
The revision of the tax blacklist is part of a broader legislative trend aimed at simplifying Portugal's tax code and enhancing transparency. This reform is closely linked to other key tax regimes, such as the Non-Habitual Resident (NHR) program and corporate tax incentives for urban regeneration. Understanding how these various tax frameworks interact is essential for optimizing investment returns.
Several critical tax areas are directly impacted by a jurisdiction's blacklist status:
• **Aggravated IMT and IMI**: Punitive flat rates of 10% and 1% respectively on real estate transactions and holdings.
• **Withholding Tax Penalties**: Standard withholding tax rates on dividends and interest are increased to 35% for blacklisted entities.
• **Capital Gains Treatment**: Corporate capital gains from the sale of Portuguese real estate face higher tax rates and stricter anti-abuse rules.
• **Transfer Pricing Scrutiny**: Transactions between Portuguese companies and blacklisted affiliates are subject to intense regulatory oversight.
These complex tax dynamics are analyzed in depth in our blog on regulatory and legal frameworks [https://www.realestate-lisbon.com/blog/regulatory-and-legal-frameworks]. Staying abreast of these changes is vital for maintaining compliance and maximizing tax efficiency.
## Investment Considerations
For international investors, the potential modernization of the blacklist opens up highly efficient structuring options. Before establishing any corporate holding vehicles, buyers should consult with experienced English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants] and property tax accountants [https://www.realestate-lisbon.com/professionals/accountants-property-tax] to ensure full compliance with both Portuguese and international tax laws.
Investors must also factor in the total cost of acquisition, including taxes, legal fees, and ongoing maintenance. Utilizing a true cost calculator [https://www.realestate-lisbon.com/calculators/true-cost] is essential for avoiding unexpected capital requirements. Additionally, investors can calculate their total acquisition costs, including IMT and stamp duty, using HomeOS's real cost calculator [https://www.homeos.pt/comprar/preco/custo-real/] to ensure full transparency and accurate financial modeling before signing any contracts.
For those looking to combine property investment with personal relocation, consulting with experts in expatriate tax services [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] and the NHR tax regime [https://www.realestate-lisbon.com/professionals/accountants-nhr-tax-regime] can provide a comprehensive strategy that optimizes both corporate and personal tax liabilities.
## Looking Ahead
The proposed reform of Portugal's tax haven blacklist is a highly positive development that will significantly enhance the country's standing as a premier destination for global real estate capital. By removing unnecessary tax barriers for legitimate investors, Portugal is positioning itself for a new wave of high-value acquisitions in both the residential and commercial sectors.
As this draft law progresses through the legislative process, investors should work closely with their legal and financial advisors to prepare for these changes. For ongoing analysis of tax policy and its impact on the property market, visit our policy analysis blog [https://www.realestate-lisbon.com/blog/policy-analysis]. For expert guidance and bespoke property acquisition services in Lisbon, contact the team at realestate-lisbon.com [https://www.realestate-lisbon.com/].