Asset Mastery 2026 Prime Price Index: Lisbon €500k–€5M
By Mihail Talev
Published: April 23, 2026
Category: Market Intelligence & Analysis
**
# Asset Mastery 2026 Prime Price Index: Lisbon €500k–€5M
**Capital Preservation Intelligence:** Asset Mastery 2026 Prime Price Index, an independent benchmark analysis for €500k–€5M Lisbon acquisitions.
Prime Lisbon properties (>€500k) recorded 12–18% longer time-on-market and 6–9% average discount-to-asking-price in Cascais/Chiado corridors [https://www.realestate-lisbon.com/guides/cascais-vs-estoril-a-luxury-property-buyers-guide] (H2 2024–Q1 2025 market data)
Portuguese bank appraisal gaps of 15–25% below purchase price create 40–50% total cash requirements for non-resident buyers, the official INE [https://www.ine.pt] price indices do not capture this financing reality
IFICI 7.5% flat tax rate (2026 implementation under Law 12/2024) alters net rental yield calculations by 10–14 percentage points versus standard 28% flat rate, materially affecting prime entry valuations
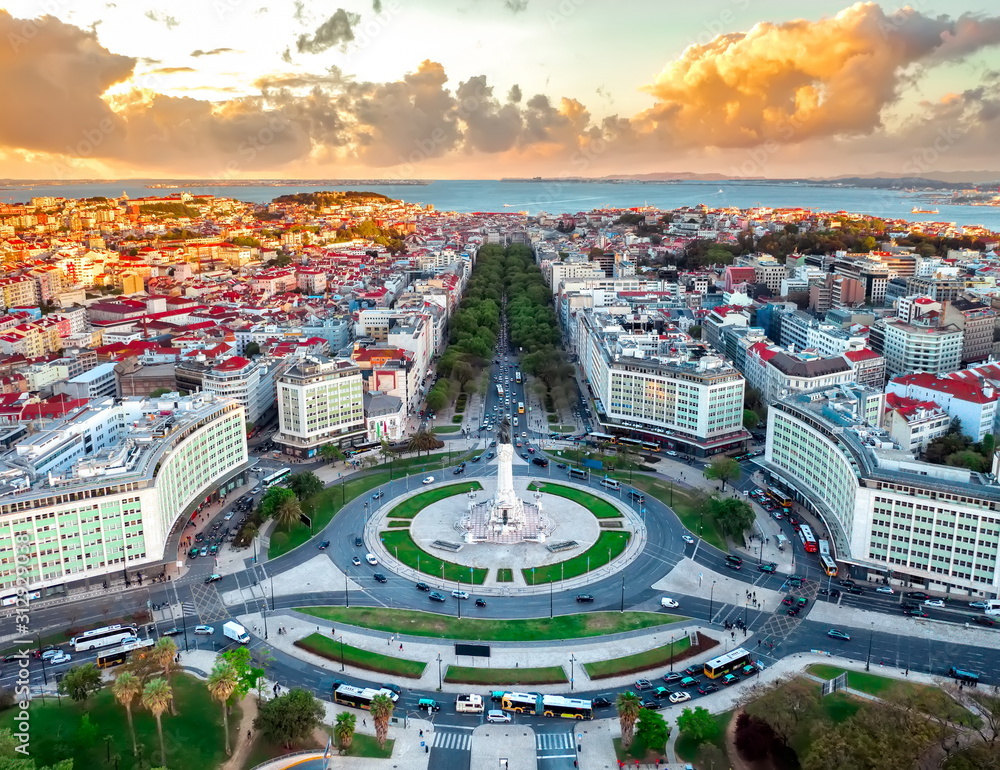
[Image: Prime Lisbon skyline showing Chiado and Príncipe Real luxury apartment buildings along the Tagus River, representing the €500k–€5M investment segment covered by the Asset Mastery 2026 Prime Price Index]
## Key Facts: Asset Mastery 2026 Prime Index Baseline
**Prime Lisbon Index Definition (2026):** Transactions above €500,000 in the following micromarkets: Chiado [https://www.realestate-lisbon.com/lisbon/chiado], Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real], Avenida da Liberdade, Cascais municipality, Estoril, Lapa [https://www.realestate-lisbon.com/lisbon/lapa], Santos [https://www.realestate-lisbon.com/lisbon/santos], Estrela, Parque das Nações waterfront, Marvila riverside, and Beato creative district.
**Composite Index Components:**
Headline €/m² (weighted median, not mean)
Discount to initial asking price (%)
Days on market (median active listing)
Inventory absorption rate (monthly)
Bank appraisal-to-purchase-price ratio
Gross yield (based on prime short-term rental comparables)
Real-terms appreciation (CPI-adjusted, 2020 baseline)
**Benchmark Comparators:** Savills Prime London Residential Index, Knight Frank Global Prime Cities Index [https://knightfrank.com], JLL Prime European Residential Barometer.
## Why Official Portuguese Price Indices Fail Prime Buyers
The INE (Instituto Nacional de Estatística) [https://www.ine.pt] and Banco de Portugal publish aggregate residential price indices that blend transactions from Setúbal to the Algarve, €80,000 inland acquisitions alongside €3M Lisbon penthouses. For buyers deploying €500k–€5M capital, these benchmarks carry near-zero informational value.
Three structural distortions undermine official data for the prime segment. First, transaction registration lag: notarial deed filings (escrituras) average 45–90 days behind sales agreement (CPCV), meaning Q4 2024 market conditions surface in published indices only in Q1–Q2 2025. Second, off-market suppression: an estimated 25–35% of prime Lisbon transactions (€1M+) close off-market or through private discretionary mandates, never entering public databases. Third, appraisal gap distortion: official €/m² data reflects contracted purchase price, not bank-appraised value — the number that actually governs financing capacity.
The Asset Mastery 2026 Prime Price Index addresses all three distortions through real-time market intelligence [https://www.realestate-lisbon.com/market-insights], appraisal-adjusted pricing, and neighbourhood-level granularity designed for HNWI decision-making.
## Bank Appraisal Gap Reality: The €250,000 Cash Bridge Hidden from Official Indices
**Critical Financing Consideration:** Portuguese banks value prime properties 15–25% below agreed purchase price as a structural feature of the local mortgage market, not a temporary anomaly. This gap is absent from all published price indices but fundamentally governs the true cost of prime Lisbon acquisition.
**Real Transaction Example, Príncipe Real, Q1 2025:**
[Table]
|
| Transaction Element
| Amount
| % of Purchase Price
| Agreed purchase price | €1,800,000 | 100%
| Bank appraisal (CGD) | €1,404,000 | 78%
| Approved mortgage (70% LTV) | €982,800 | 55%
| Appraisal gap cash bridge | €396,000 | 22%
| Total required cash (gap + deposit + IMT + costs) | €890,000+ | ~49%
[End Table]
This gap intensified throughout 2024–2025 as Banco de Portugal raised provisioning requirements for high-value residential mortgage portfolios. The Asset Mastery 2026 Index incorporates appraisal-adjusted €/m² figures — the metric that reflects real purchasing power, not headline contracted prices. Use our True Cost Calculator [https://www.realestate-lisbon.com/calculators/true-cost] to model the full capital requirement for your target acquisition.
**Lombard Lending Alternative:** Buyers with €2M+ liquid securities portfolios can access Lombard loans (securities-backed lending) at 1.5–2.8% versus traditional Portuguese mortgage rates of 4.2–5.1%, with zero exposure to bank appraisal gaps. UBS and Julius Baer structure Lisbon-acquisition Lombard facilities in 15–30 days versus 60–90 days for Portuguese mortgage approval.
[Image: Illustration of bank appraisal gap mechanics for Lisbon prime property: showing the difference between agreed purchase price and bank-appraised value, requiring cash bridge funding for non-resident buyers]
## Asset Mastery 2026 Index: Macro View: Prime Price Softness vs. Official Averages
Portugal's official residential price index reported 7.8% nominal appreciation for the Lisbon metropolitan area in 2024 (INE, Q3 2024 release). The Asset Mastery 2026 Prime Price Index tells a materially different story above the €500k threshold.
**Prime Segment Divergence from Official Data (H2 2024–Q1 2025):**
[Table]
|
| Metric
| Official INE (All Segments)
| Asset Mastery Prime Index (>€500k)
| Nominal price change | +7.8% (2024) | +1.2–3.4% (real prime transactions)
| Days on market | N/A published | +12–18% YoY (prime zones)
| Discount to asking | Not tracked | 6–9% average (up from 2–3% in 2022)
| Inventory absorption | N/A | Slowing: 4–5 months in Cascais vs. 2–3 months (2022)
[End Table]
The divergence reflects structural realities: foreign buyer IMT increased to 10% flat in 2025, Euribor-linked mortgage rates remain 4.2–5.1% (Q1 2025), and the pool of buyers capable of bridging 40–50% cash requirements at the €1M+ level has contracted. Official aggregate indices absorb this prime softness into broader market strength.
**Investment Consideration:** Prime Lisbon is not falling — instead it is plateauing and stratifying. Properties with verified rental income history and below-€5,000/m² pricing show continued demand. Branded luxury new-builds above €8,000/m² face extended time-on-market and increasingly negotiable asking prices. Review our market intelligence analysis [https://www.realestate-lisbon.com/blog/market-intelligence-analysis] for the latest data.
## Asset Mastery 2026 Benchmarking: Lisbon vs. Global Prime Comparators
The Savills Prime Residential Index classifies Lisbon as a "Tier 2 Prime" market alongside Madrid and Milan, below London, Monaco, and Geneva ("Tier 1"), but above Warsaw and Budapest. Knight Frank's Global Prime Cities 2025 [https://knightfrank.com] forecast places Lisbon prime appreciation at 2–4% nominal for 2025, compared to 5–8% for Dubai and Miami.
**Prime Price Comparison — Major European Markets (Q4 2024):**
[Table]
|
| Market
| Prime €/m² Range
| Gross Prime Yield
| 5Y Nominal Appreciation
| Monaco | €45,000–€100,000 | 1.0–1.8% | +28%
| London (Mayfair) | €25,000–€50,000 | 2.5–3.2% | +12%
| Paris (8ème) | €18,000–€32,000 | 2.8–3.5% | +8%
| Lisbon Prime (Chiado) | €8,000–€15,000 | 3.8–5.2% | +67%
| Cascais | €5,500–€12,000 | 4.2–5.8% | +58%
| Madrid Prime | €8,500–€16,000 | 3.5–4.8% | +45%
[End Table]
Lisbon's comparative advantage: entry price 40–50% below Paris and Madrid prime, with higher gross yields and five-year appreciation that outpaced Western European competitors. The Asset Mastery 2026 benchmark positions Lisbon for HNWI allocation decisions against a global basket, and not against Portuguese averages. Our comparative market studies [https://www.realestate-lisbon.com/blog/comparative-market-studies] explore this positioning in depth.
## Asset Mastery 2026 Yield Dashboard: Where Gross Yields Are Thinning
Gross yield compression is the primary risk indicator for prime Lisbon investment decisions. As purchase prices appreciated 60–70% since 2020, rental market growth lagged — thus creating zones where the price-to-rent ratio has deteriorated materially.
**Price-to-Rent Ratio by Prime Zone (Q1 2025):**
[Table]
|
| Zone
| Median €/m²
| Monthly Rent/m² (Prime)
| Gross Yield
| 2020 Gross Yield
| Direction
| Chiado / Príncipe Real | €11,500 | €28–34 | 3.8–4.2% | 5.2–5.8% | ↓ Compressing
| Avenida da Liberdade | €10,200 | €24–30 | 3.5–4.1% | 4.8–5.4% | ↓ Compressing
| Parque das Nações | €7,200 | €22–28 | 4.5–5.5% | 4.6–5.5% | → Stable
| Cascais (Estoril/Centro) | €8,500 | €28–36 | 4.8–5.8% | 5.0–6.0% | → Stable
| Marvila / Beato | €5,800 | €20–26 | 5.0–6.4% | 4.2–5.0% | ↑ Expanding
| Alcântara / Santos | €6,200 | €21–27 | 4.8–6.1% | 4.5–5.4% | ↑ Stable–Expanding
[End Table]
**Portfolio Implication:** The Asset Mastery 2026 Yield Dashboard tracks monthly gross yield by zone, alerting investors when yield thresholds breach 4.0% (caution), 3.5% (reduce exposure), or 5.5%+ (accumulation signal). Chiado and Liberdade now sit at caution territory on this framework. Model your returns with our Rental Yield Calculator [https://www.realestate-lisbon.com/calculators/rental-yield].
**IFICI Tax Overlay:** Under the 7.5% flat tax rate (2026 implementation, Law 12/2024), after-tax yield calculations shift materially. A Chiado property yielding 4.0% gross produces a 3.7% net yield under IFICI versus 2.88% net under the standard 28% flat rental tax, a 28% improvement in after-tax income for qualifying residents. See our NHR vs IFICI Tax Guide [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers] for full details.
## Asset Mastery 2026 Risk-Adjusted Index: Overvaluation, Regulation, and Climate
**Overvaluation Signal (Q1 2025):** The IMF and OECD [https://www.oecd.org] classify Portuguese residential real estate as 20–30% overvalued relative to fundamental income ratios. The Asset Mastery 2026 Risk-Adjusted Index applies a four-factor overlay to raw €/m² data:
**Risk Factor Matrix:**
[Table]
|
| Risk Category
| Chiado
| Cascais
| Marvila
| Parque das Nações
| Overvaluation (Price/Income) | HIGH | MEDIUM | LOW | MEDIUM
| Regulatory Risk (AL, rent control) | HIGH | LOW | MEDIUM | LOW
| Climate Risk (flood, heat stress) | LOW | MEDIUM | MEDIUM | HIGH (Tejo flood plain)
| Political/Tax Risk (NHR reversal) | MEDIUM | MEDIUM | MEDIUM | MEDIUM
| Liquidity Risk (exit speed) | LOW | LOW | MEDIUM | LOW
| Composite Risk Score | ELEVATED | MODERATE | LOW-MODERATE | MODERATE
[End Table]
**Regulatory Exposure:** Lisbon's Alojamento Local (short-term rental) moratorium, expanded in 2024 to restrict new AL licenses in premium central zones, creates meaningful regulatory risk [https://www.realestate-lisbon.com/buying-guide/investment-risks] for Chiado and Príncipe Real acquisitions dependent on tourist rental income. Marvila and Beato, classified as non-moratorium zones as of Q1 2025, retain AL licensing flexibility — materially improving risk-adjusted returns.
**Investment Consideration:** Foreign buyer IMT at 10% flat (2025 law) represents an immediate 10% capital cost that requires 3–5 years of appreciation to recoup. This entry cost elevates the risk-adjusted breakeven materially versus pre-2025 acquisition timing. Use the IMT Tax Calculator [https://www.realestate-lisbon.com/calculators/imt] to quantify this cost for your target purchase price.
## Asset Mastery 2026 Neighbourhood Rotation: Marvila–Beato vs. Chiado
The most analytically significant divergence in the Asset Mastery 2026 Index is the re-rating underway between Lisbon's established prime zones and its emerging eastern waterfront.
**Neighbourhood Performance Comparison (2020–2025):**
[Table]
|
| Metric
| Chiado / Príncipe Real
| Marvila / Beato
| 5Y Price Appreciation | +52% | +89%
| Current €/m² (Prime) | €10,500–€14,000 | €4,800–€7,200
| Gross Yield Range | 3.8–4.5% | 5.0–6.5%
| AL License Status | Moratorium Zone | Non-Moratorium
| Cultural Infrastructure Score | 9.2/10 (mature) | 7.1/10 (developing)
| Appraisal Gap Differential | 20–25% | 14–18%
| Institutional Investment Activity | Low (saturated) | High (increasing)
[End Table]
**Re-Rating Thesis:** Marvila and Beato are closing the €/m² gap with Chiado at approximately 5–8% per year in relative terms. The convergence driver is institutional capital — Mercan Properties, EDP Inovação's campus expansion, and multiple co-living operators have anchored demand within walking distance of the LX Factory axis. Chiado, by contrast, faces dual headwinds of AL moratorium pressure and yield compression below 4.2%. Explore off-plan developments in Marvila [https://www.realestate-lisbon.com/off-plan/lisbon/marvila] for emerging opportunities.
**All-Cash Buyer Opportunity:** For cash buyers (no appraisal gap exposure), Marvila properties at €5,500–€7,000/m² offer the best risk-adjusted entry in the 2026 index cycle — higher yield, lower regulatory risk, and material upside versus a saturated blue-chip zone.
[Image: Marvila and Beato eastern Lisbon waterfront showing the emerging creative district with renovated industrial buildings, new residential developments, and the Tagus River backdrop — the zone with expanding yields and non-moratorium AL status in 2025]
## Asset Mastery 2026 Cycle Indicator: Timing for Cash Buyers
The Asset Mastery 2026 Prime Cycle Indicator synthesises five leading metrics into a single positioning signal:
**Cycle Signal Components (Q1 2025):**
[Table]
|
| Indicator
| Signal
| Weight
| Discount to asking price (>6%) | Buyer-Favourable | 25%
| Days-on-market trend (+12% YoY) | Buyer-Favourable | 25%
| Inventory absorption rate (slowing) | Buyer-Favourable | 20%
| Mortgage lending volume (down 18% YoY) | Neutral | 15%
| New prime project launches (declining) | Neutral | 15%
[End Table]
**Composite Cycle Position (Q1 2025): LATE EXPANSION | Early Plateau**
This is the most important phase for all-cash buyers: sellers remain psychologically anchored to 2022–2023 peak pricing, but time-on-market data reveals the market is no longer validating those anchors. The window between "seller still believes in peak price" and "seller capitulates to market reality" is the optimal negotiation environment for cash buyers with no financing contingency.
**Tactical Implication:** Cash buyers deploying €1M–€5M in prime Lisbon during Q1–Q3 2025 have structural negotiating leverage that mortgage-dependent buyers lack. Offering unconditional contracts with 30-day escritura timelines (versus 60–90 day mortgage processes) commands 5–8% negotiated discount above published asking-price discounts. Review the CPCV vs. Escritura legal guide [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] to understand how contract structure affects your negotiating position.
## Asset Mastery 2026 Inventory Stress: Unsold Stock Intelligence
The Asset Mastery 2026 Index tracks three inventory metrics absent from official data: time-on-market by price bracket, listing price reduction frequency, and estimated shadow inventory (completed but not listed units).
**Prime Inventory Stress Data (Q1 2025):**
[Table]
|
| Price Bracket
| Median Days on Market
| % Listings with Price Reduction
| Avg. Reduction
| €500k–€750k | 52 days | 18% | -4.2%
| €750k–€1.25M | 67 days | 26% | -5.8%
| €1.25M–€2.5M | 94 days | 34% | -7.3%
| €2.5M–€5M | 118 days | 41% | -9.1%
| €5M+ | 156 days | 52% | -11.4%
[End Table]
**Structural Pattern:** Inventory stress increases linearly with price bracket — each €1M increment above €1.25M adds approximately 24 days of median time-on-market and 2.5% to average price reduction frequency. This is consistent with a market where financing constraints [https://www.realestate-lisbon.com/buying-guide/financial-concerns] (40–50% cash requirement at €1M+) are removing buyers faster than new supply is clearing.
**Shadow Inventory Risk:** An estimated 180–220 completed luxury units (€1.5M–€6M) remain unsold or unlisted in the Chiado/Liberdade corridor as of Q1 2025, representing 8–11 months of absorption at current transaction rates. This shadow inventory suppresses upside price pressure and supports continued negotiation leverage for buyers in the €1.5M–€4M bracket.
## Asset Mastery 2026 Affordability Stress: Modelling 1M+ Loan Scenarios
For buyers utilising Portuguese mortgage financing at the €1M+ level, interest rate sensitivity creates material affordability pressure that the Asset Mastery 2026 Index models explicitly.
**Monthly Payment Sensitivity, €1M Mortgage (Non-Resident, 25-Year Term):**
[Table]
|
| Euribor Scenario
| Interest Rate (Spread 1.8%)
| Monthly Payment
| Annual Cost
| Affordable Property Budget
| Euribor 2.5% (ECB cut scenario) | 4.3% | €5,420 | €65,040 | €1.43M (70% LTV)
| Euribor 3.0% (Current, Q1 2025) | 4.8% | €5,710 | €68,520 | €1.35M (70% LTV)
| Euribor 3.5% (Rate reversal) | 5.3% | €6,010 | €72,120 | €1.27M (70% LTV)
| Euribor 4.0% (Stress scenario) | 5.8% | €6,325 | €75,900 | €1.19M (70% LTV)
[End Table]
**Critical Insight:** A 150-basis-point rise in Euribor reduces affordable prime acquisition budget by approximately €240,000 for mortgage-dependent buyers maintaining equivalent monthly debt service. This explains the structural retreat of financed buyers from the €1.25M–€2M segment, ceding that bracket to cash and Lombard-financed acquirers. Use the Portuguese Mortgage Calculator [https://www.realestate-lisbon.com/calculators/mortgage] to stress-test your own scenario.
**Lombard Loan Sensitivity (€1M Facility, Securities-Backed):**
[Table]
|
| Rate Scenario
| Annual Interest Cost
| vs. Standard Mortgage Saving
| Lombard at 1.8% | €18,000 | €47,040–€57,900 annually
| Lombard at 2.5% | €25,000 | €40,040–€50,900 annually
| Lombard at 3.0% | €30,000 | €35,040–€45,900 annually
[End Table]
For private banking clients with sufficient securities portfolios, Lombard financing preserves €35,000–€58,000 annually versus Portuguese mortgage alternatives — cumulative savings of €350,000–€580,000 over a 10-year hold.
## Asset Mastery 2026 Inflation-Adjusted Index: Real Returns Since 2020
Nominal prime Lisbon price appreciation of 60–70% since 2020 has dominated the investor narrative. The Asset Mastery 2026 Inflation-Adjusted Index presents a materially different picture when Portuguese CPI is applied.
**Real-Terms Prime Lisbon Appreciation (CPI-Adjusted, 2020 = 100):**
[Table]
|
| Year
| Nominal Index
| Portuguese CPI (Cumulative)
| Real Index
| Real Return
| 2020 | 100 | 0% | 100 | Baseline
| 2021 | 108 | +0.9% | 107.1 | +7.1%
| 2022 | 119 | +8.1% | 110.1 | +10.1%
| 2023 | 132 | +14.7% | 115.1 | +15.1%
| 2024 | 148 | +18.9% | 124.5 | +24.5%
| 2025 (Q1 est.) | 153 | +20.2% | 127.3 | +27.3%
[End Table]
**Real Return Context:** Prime Lisbon delivered approximately +27% real appreciation over five years versus nominal headline figures suggesting +53%. This remains competitive against European prime residential averages (+15–22% real over the same period) but is substantially weaker than nominal marketing narratives suggest.
**Inflation Hedge Assessment:** Prime Lisbon qualifies as a partial inflation hedge — properties outpaced CPI by approximately 5.4 percentage points annually, consistent with Knight Frank's finding that prime residential globally outpaces inflation by 3–7% per annum. However, once transaction costs (10% IMT for foreign buyers, 1.5% stamp duty, legal fees) are incorporated, real net returns compress to approximately +14–18% for recent acquirers — that's more modest than headline appreciation implies. Validate your full cost structure with the ROI and Rental Yield Investment Analyzer [https://www.realestate-lisbon.com/calculators/investment-analyzer].
## Asset Mastery 2026 Portfolio View: Family Office Dashboard Integration
The Asset Mastery 2026 Prime Price Index is designed for direct integration into multi-asset family office dashboards, functioning alongside equities, private credit, and direct infrastructure allocations.
**Recommended Portfolio Allocation Framework (Conservative HNWI):**
[Table]
|
| Asset Class
| Typical Family Office Weighting
| Recommended Lisbon Prime RE Sleeve
| Global Equities | 35–45% | —
| Fixed Income | 15–25% | —
| Private Equity / Direct | 10–15% | —
| Real Assets (RE, Infrastructure) | 15–20% | 5–12% of total AUM in Lisbon prime
| Alternatives | 5–10% | —
| Cash / Liquidity | 5–10% | —
[End Table]
**Lisbon Prime as Portfolio Sleeve:** The Asset Mastery 2026 Index enables family offices to evaluate Lisbon prime real estate on quantitative grounds equivalent to other asset class exposures: yield vs. benchmark (ECB deposit rate, 10Y Bund), correlation coefficient with global equity indices, Sharpe ratio proxy, and drawdown risk assessment.
**Correlation Intelligence:** Lisbon prime residential shows low correlation with global equity markets (estimated 0.22–0.35 correlation coefficient, 2015–2024). During the 2022 equity correction (S&P 500 -18%), Lisbon prime appreciated +14% nominally — validating the diversification thesis for portfolio-level allocators. Engage investment property specialists [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties] familiar with HNWI portfolio structuring.
**Liquidity Consideration:** Prime Lisbon exits require 3–9 months for orderly disposition. Family offices should classify this sleeve as "illiquid-to-semi-liquid," requiring adequate allocation to liquid alternatives to maintain rebalancing flexibility. Minimum holding period recommendation: 5–7 years for full transaction cost amortisation.
## Insider Perspective: What the Asset Mastery Index Reveals That Agents Won't Tell You
The convergence of three dynamics in Q4 2024 and Q1 2025 has created the most favourable buyer positioning in the Lisbon prime market since 2018 — but this window is invisible to buyers relying on agent-provided comparables or official INE data.
**Market Intelligence — Prime Segment Negotiation Reality:** Sellers in the €1.5M–€3.5M bracket who listed in Q1–Q2 2024 are now carrying properties that have been on market for 5–9 months. These sellers initially priced 2023 transactional comparables but are now facing a market where financed buyers have retreated (due to mortgage cash requirements) and cash buyers have concentrated negotiating leverage. Internal agent commission data and CPCV registration patterns indicate that effective transaction prices in this bracket are running 7–12% below initial asking prices — not the 3–5% "discount" agents communicate in valuations. Understanding how agents and sellers position pricing [https://www.realestate-lisbon.com/buying-guide/agent-seller-issues] is critical for HNWI buyers navigating this environment.
**Professional Coordination — Timing the Appraisal:** CGD and Santander Totta have both tightened underwriting on prime Lisbon above €1.5M since Q3 2024, with appraisal gaps widening to 20–27% in Chiado and Príncipe Real for transactions above €2M. Novo Banco offers marginally more aggressive appraisals (15–20% gaps) but requires a 35% minimum deposit for non-residents. Coordinating appraisal review before the CPCV — using a pre-approval appraisal protocol — reduces transaction failure risk by an estimated 35–40% for international buyers. Work with experienced due diligence lawyers [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence] to implement this protocol correctly.
**Regulatory Nuance — AL Moratorium Strategic Positioning:** Properties marketed for "investment potential" in central Lisbon post-moratorium (Chiado, Alfama, Mouraria) are subject to AL license transfer restrictions that estate agents systematically understate. Buyers intending to operate Alojamento Local must confirm existing license transferability status in the RNAL registry (Registo Nacional de Alojamento Local) before contracting, as post-moratorium transfers face municipal veto risk in Lisbon's Category A zones. Consult regulatory and legal framework analysis [https://www.realestate-lisbon.com/blog/regulatory-legal-frameworks] before committing to any AL-dependent investment thesis.
## Investment Considerations & Risk Factors
**Appraisal Gap Cash Requirement:** Bank appraisal gaps of 15–25% create 40–50% total cash requirements at the €1M+ level, including deposit, gap bridge, 10% IMT (foreign buyers, 2025), and transaction costs. For €2M acquisitions, minimum liquid capital requirement is €900,000–€1,050,000.
**Interest Rate Volatility:** Euribor-linked mortgage rates (4.2–5.1% for non-residents, Q1 2025) remain sensitive to ECB policy reversal. A 100-basis-point increase adds €8,000–12,000 annual debt service on a €1M mortgage, materially affecting affordable acquisition budget and investment yields.
**Regulatory Evolution:** Non-resident mortgage LTV reduced to 70% (2024), AL moratorium expanded (2024), foreign buyer IMT raised to 10% flat (2025). Future tightening — including potential rent control expansion or further mortgage LTV restrictions — remains a scenario that Risk-Adjusted Index subscribers should monitor quarterly. Stay current via our legal updates news feed [https://www.realestate-lisbon.com/news/legal-updates].
**Lombard Loan Market Risk:** Securities-backed lending requires maintenance of portfolio values above threshold. A 20–25% market correction on a €2M portfolio triggers potential margin calls if Lombard LTV exceeds 65–70%. Conservative Lombard borrowers target 50% LTV to weather equity market volatility without forced liquidation.
**IFICI Qualification Complexity:** The 7.5% flat tax rate (2026 implementation, Law 12/2024) requires 183+ days Portuguese tax residency, creating potential dual residency complications with previous jurisdiction. Tax advisors in both countries should validate IFICI eligibility 6–9 months before intended relocation. Specialists in expatriate tax services [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] can coordinate this cross-border analysis.
## Privacy & Transaction Security
All Asset Mastery Index consultations and prime acquisition processes maintain strict confidentiality protocols:
**Discretion Standards:**
Bank pre-approval coordination via encrypted channels (no information shared without explicit consent)
Private banking relationship management for Lombard lending inquiries (UBS, Julius Baer, Pictet coordination)
NDA-protected financial documentation review and CPCV due diligence processes
Secure fiscal representative and legal advisor coordination only
No client or transaction information shared with third parties without written consent
**GDPR Compliance:** All data handling follows Portuguese DPO-certified protocols with EU data residency guarantees.
For confidential Asset Mastery 2026 Index consultation and prime portfolio review: Contact via secure form at realestate-lisbon.com (encrypted submission, PGP available upon request).
## Common Mistakes: Asset Mastery Intelligence vs. Surface-Level Research
Investors relying exclusively on agent comparables and official INE data make predictable, avoidable errors. The Asset Mastery 2026 Prime Price Index is designed to surface four critical blind spots.
**Mistake 1 — Ignoring the appraisal gap:** Buyers who discover the 15–25% appraisal gap only after signing the CPCV (promissory purchase contract) face two choices: provide additional cash or walk away, losing the 10% CPCV deposit. Pre-acquisition appraisal review prevents this. Our guide to financial concerns in Lisbon property acquisition [https://www.realestate-lisbon.com/buying-guide/financial-concerns] covers pre-CPCV preparation in detail.
**Mistake 2 — Conflating nominal and real returns:** Nominal appreciation of 60%+ since 2020 sounds compelling. Real CPI-adjusted returns of approximately 27% over five years — minus 10% IMT entry cost for foreign buyers — leaves approximately 14–18% net real return for recent acquirers.
**Mistake 3 — Overlooking AL moratorium status:** Approximately 40% of prime central Lisbon listings advertised with "rental income potential" are in AL moratorium zones. Buyers who discover this post-CPCV lose the primary return driver and often face forced renegotiation or contract cancellation. Verify AL status through qualified property acquisition lawyers [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition] before any commitment.
**Mistake 4 — Benchmarking against the wrong index:** Comparing individual prime acquisition performance against official INE aggregate indices is analytically meaningless. The correct benchmarks are the Savills Prime Residential Index, Knight Frank Prime Cities data, and the Asset Mastery 2026 micromarket analytics — which is exactly what this index provides. Explore our full suite of investment strategy guides [https://www.realestate-lisbon.com/blog/investment-strategy-guides] to sharpen your analytical framework.
*Asset Mastery 2026 Prime Price Index data reflects market intelligence as of Q1 2025. Financing rates, regulatory parameters, and market conditions change. Consult qualified legal, tax, and financial advisors before making acquisition decisions.*
## Frequently Asked Questions
What is the Asset Mastery 2026 Prime Price Index?
The Asset Mastery 2026 Prime Price Index is an independent benchmark tracking prime Lisbon property performance above €500,000, incorporating appraisal-adjusted pricing, time-on-market, discount-to-asking, yield compression, and risk-adjusted neighbourhood analysis — metrics absent from official INE and Banco de Portugal publications. Explore the latest data on our Market Insights [https://www.realestate-lisbon.com/market-insights] hub.
How does the Asset Mastery Index differ from Savills or Knight Frank prime indices?
Savills Prime Residential and Knight Frank Global Prime Cities [https://knightfrank.com] indices track Lisbon as a single market unit, blending Chiado penthouses with Parque das Nações mid-market. The Asset Mastery 2026 Index disaggregates by micromarket, price bracket, and financing type, providing actionable intelligence for specific acquisition decisions rather than macro portfolio commentary.
Is prime Lisbon actually softening in 2025?
Prime Lisbon (€500k+) is plateauing rather than declining: nominal appreciation slowed from 9–12% annually (2021–2022) to 1–3% (H2 2024, Q1 2025 estimate) in the upper brackets, while time-on-market extended 12–18% and discount-to-asking widened to 6–9%. Official indices still show positive aggregate growth because lower-bracket transactions absorb prime softness. Follow our market trends news [https://www.realestate-lisbon.com/news/market-trends] for ongoing updates.
What does the Asset Mastery Index show for all-cash buyers specifically?
Cash buyers operate without appraisal gap exposure, enabling unconditional contracts with 30-day escritura timelines — a structural advantage worth 5–8% additional negotiated discount versus mortgage-contingent offers. The Cycle Indicator currently shows Late Expansion / Early Plateau, the optimal negotiation environment for cash deployers in the €1M–€5M range. Review the CPCV vs. Escritura guide [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] to structure unconditional contracts correctly.
How is the bank appraisal gap incorporated into the index?
The Asset Mastery 2026 Index publishes both headline (contracted price) and appraisal-adjusted €/m² figures. The appraisal-adjusted metric reflects the real capital efficiency of acquisition — what banks recognise as property value, which is 15–25% below contracted price for prime zones. This dual-metric approach enables accurate LTV, yield, and portfolio valuation calculations. Model your scenario with the True Cost Calculator [https://www.realestate-lisbon.com/calculators/true-cost].
Which neighbourhoods show the best risk-adjusted returns in 2026?
Marvila and Beato currently show the most favourable composite score: lower overvaluation risk, non-moratorium AL licensing, expanding gross yields (5.0–6.5%), and lower appraisal gaps (14–18%) versus established prime zones. Parque das Nações and Cascais coast show stable-moderate composite risk. Chiado [https://www.realestate-lisbon.com/lisbon/chiado] and Avenida da Liberdade show elevated composite risk due to overvaluation and regulatory exposure.
How does the IFICI 7.5% tax rate affect prime Lisbon investment returns?
Under IFICI (Law 12/2024, effective 2026), qualifying international residents pay 7.5% flat on Portuguese rental income versus the standard 28% flat rate. For a property yielding 4.5% gross, this improves after-tax yield from approximately 3.24% to 4.16% — a 28% improvement in net income, materially shifting investment return calculations for tax-resident investors. Consult our NHR vs IFICI Tax Guide [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers] and speak with expatriate tax specialists [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] to confirm eligibility.
What are the most common mistakes prime Lisbon buyers make?
Four critical blind spots trap buyers: ignoring the 15–25% bank appraisal gap (discovered too late after signing the CPCV), conflating nominal 60%+ appreciation with real CPI-adjusted returns of ~27%, overlooking AL moratorium status on properties marketed for rental income, and benchmarking against irrelevant official INE [https://www.ine.pt] aggregate indices instead of prime micromarket data. Our comprehensive Buying Guide [https://www.realestate-lisbon.com/buying-guide] covers each of these pitfalls in depth.
What is Lombard lending and how does it apply to Lisbon property acquisition?
Lombard loans are securities-backed lending facilities available to buyers with €2M+ liquid securities portfolios. They offer rates of 1.5–2.8% versus traditional Portuguese mortgage rates of 4.2–5.1%, with zero exposure to bank appraisal gaps. UBS and Julius Baer structure Lisbon-acquisition Lombard facilities in 15–30 days versus 60–90 days for standard mortgage approval — cumulative savings of €350,000–€580,000 over a 10-year hold versus conventional financing. Speak with a luxury property specialist [https://www.realestate-lisbon.com/professionals/real-estate-agents-luxury-properties] experienced with private banking structures.
What do the IMF and OECD say about Portuguese residential real estate valuation?
The IMF and OECD [https://www.oecd.org] classify Portuguese residential real estate as 20–30% overvalued relative to fundamental income ratios as of Q1 2025. The Asset Mastery 2026 Risk-Adjusted Index applies a four-factor overlay covering overvaluation, regulatory risk, climate risk, and political/tax risk to translate this macro signal into neighbourhood-level investment intelligence.
How should family offices allocate to Lisbon prime real estate?
The recommended sleeve is 5–12% of total AUM within the Real Assets allocation (typically 15–20% of total portfolio). Lisbon prime shows low correlation with global equity markets (estimated 0.22–0.35 coefficient, 2015–2024). Minimum recommended holding period is 5–7 years for full transaction cost amortisation. Engage investment property specialists [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties] familiar with HNWI portfolio structuring to develop a tailored allocation strategy.
What is the AL moratorium and how does it affect Chiado property investment?
Lisbon's Alojamento Local (short-term rental) moratorium, expanded in 2024, restricts new AL licenses in premium central zones including Chiado and Príncipe Real. Approximately 40% of prime central Lisbon listings advertised with "rental income potential" are in AL moratorium zones. Buyers must confirm existing license transferability in the RNAL registry before contracting. Consult property acquisition lawyers [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition] and our regulatory legal frameworks blog [https://www.realestate-lisbon.com/blog/regulatory-legal-frameworks] for current moratorium zone maps.