LTV Strategies for International Buyers in Portugal 2026
By Pieter Paul Castelein
Published: May 1, 2026
Category: Investment & Strategy Guides
**
# LTV Strategies for International Buyers in Portugal 2026
Capital Preservation Intelligence: Mortgage leverage optimization for international buyers acquiring Lisbon property in the €500K–€5M range.
[Image: International buyers reviewing mortgage leverage strategies for Lisbon property acquisition in 2026]
Portuguese banks cap non-resident LTV at 60–70%, requiring 38–50% total cash (deposit plus 8–12% closing costs); fiscal residency conversion raises that ceiling to 80–90% LTV
3-month Euribor stands at 1.999% as of February 2026, with ECB deposit rate held at 2.00% since June 2025, producing all-in non-resident mortgage rates of 3.3–5.5%
Proposed flat 7.5% IMT for non-resident purchases (pending parliamentary approval, 2026) includes a two-year residency refund clause, which creates a double incentive for fiscal residency conversion
## Key Facts
• Portuguese non-residents face 60–70% LTV caps versus 80–90% for residents, a gap driven by bank risk policy, not Banco de Portugal regulation
• Lisbon's median asking price [https://www.realestate-lisbon.com/market-insights] reached €5,824/m² in 2025, with prime neighborhoods commanding €8,000–€12,000/m²
• 3-month Euribor: 1.999% as of mid-February 2026; 12-month Euribor: 2.236%
• Non-resident closing costs add 8–12% of purchase price (IMT, stamp duty, notary, legal, bank fees), bringing total cash requirement to 38–50% of property value
• Private banking Lombard structures can unlock up to 100% LTV when borrowers place 30–50% of loan value in assets under management
• Mixed-rate mortgages (fixed 5 years, then variable) represent the majority of new originations in Portugal since late 2024
• US citizens face FATCA-related reluctance from many Portuguese retail banks; specialist brokers are often essential
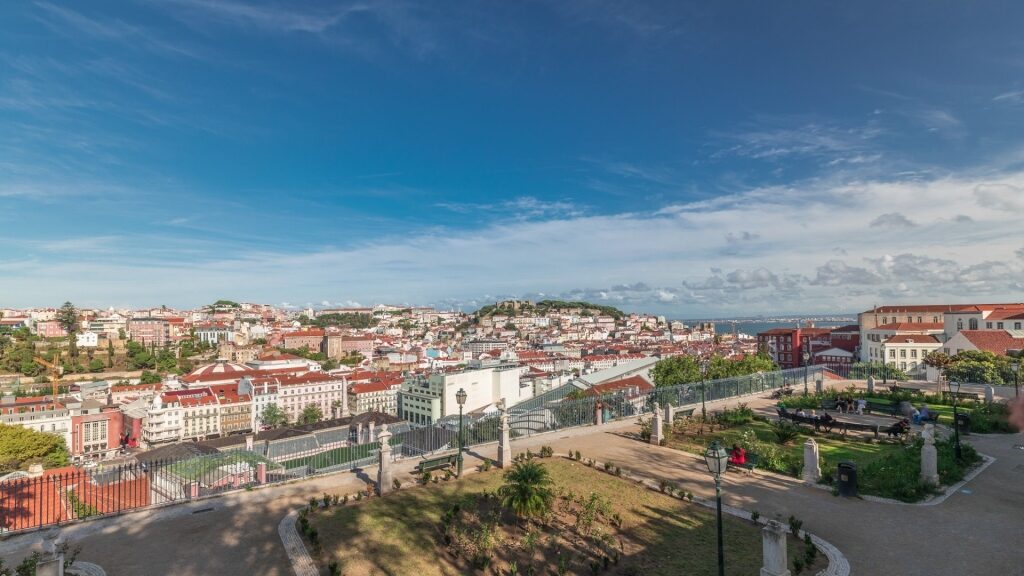
[Image: Aerial view of prime Lisbon residential neighborhoods including Príncipe Real and Estrela showing luxury property market]
## What Is the 60–70% LTV Cap and Why Do Portuguese Banks Apply It?
The Banco de Portugal's macroprudential framework that's in force since July 2018 does not distinguish between residents and non-residents. Its regulatory caps are 90% LTV for primary residences and 80% LTV for second homes or investment properties. The lower ceilings that international buyers encounter are individual bank risk policies, not statutory mandates, yet they are applied with near-universal consistency across the Portuguese banking sector.
### Regulatory Context
Four overlapping risk factors drive these internal policies. Currency risk sits at the top: a borrower earning in GBP or USD faces exchange-rate exposure that can erode repayment capacity independent of property values. Cross-border enforcement difficulty means recovering debt from a defaulting non-resident involves significant legal complexity across jurisdictions. Credit-assessment opacity reflects the limited reliability of foreign credit bureau data in Portuguese underwriting models. Finally, the property-purpose premium applies because most non-residents acquire second homes or investment properties, these categories already are carrying elevated default risk under the Bank of Portugal framework.
### Investment Consideration
The practical result for international buyers is a 30–40% deposit requirement before closing costs, which add another 8–12% of purchase price (IMT, stamp duty, notary, legal, and bank fees). Total cash required for a non-resident acquisition therefore approximates 38–50% of the property's value, demanding deliberate capital planning well in advance of any offer. Use the True Cost Calculator for Property [https://www.realestate-lisbon.com/calculators/true-cost] to model these figures against your specific purchase price.
## How Do Portuguese Banks Compare for Non-Resident LTV?
The table below reflects current broker network data for non-resident lending as of early 2026. Actual LTV depends on the individual financial profile, property location, and negotiation outcome.
[Table]
|
| Bank
| Max Non-Resident LTV
| Distinguishing Feature
| Bankinter
| Up to 80%
| Best digital platform; competitive fixed rates from ~3.6%
| BPI
| 80% (primary) / 70% (holiday)
| CaixaBank subsidiary; cross-border ease for Spanish banking clients
| Novo Banco
| 70–80%
| Strongest variable-rate spreads, some below 1% on Euribor 12M
| Santander Portugal
| 70–80%
| Longest terms (up to 40 years); global Santander relationship leverage
| Millennium BCP
| 60–75%
| Largest private bank; dedicated English-speaking international department
| CGD
| 60–70%
| Largest public bank; 23-country presence; conservative underwriting
| UCI
| Up to 70%
| Core specialist for non-residents; accepts multilingual docs; max loan €3M
| Banco CTT
| 70–75%
| Transparent fee structure; limited English support
| Private banks (via brokers)
| Up to 100%
| Requires assets under management ≥30–50% of loan value
[End Table]
Market Intelligence: Bankinter, BPI, and Novo Banco represent the current upper end of non-resident LTV at 75–80%. CGD sits at the conservative end. UCI stands apart as the only institution whose entire business model is structured around non-resident lending—offering streamlined documentation and multilingual processing, though at marginally higher rate premiums. For context, Portugal's non-resident regime is broadly comparable to Spain (~70% LTV), significantly more generous than Italy (50–60% LTV), and more equitable than France (up to 85% for EU citizens but only 50% for Americans). Explore our comparative market studies [https://www.realestate-lisbon.com/blog/comparative-market-studies] for deeper cross-border analysis.
## Bridge Financing vs. Long-Term Mortgages: When Does Speed Justify Cost?
Bridge financing (crédito ponte) is a short-term, asset-backed product designed to close a timing gap, most commonly when a buyer needs to complete a Portuguese purchase before selling property abroad or liquidating assets elsewhere. In Portugal's context, this product is niche and expensive, primarily offered by specialist international lenders rather than mainstream Portuguese banks.
### Investment Consideration
The economics are significant. Bridge loans carry interest rates starting around 1% per month (approximately 12%+ annualized), compared to 3.3–5.5% for standard non-resident mortgages. Structures are interest-only with bullet repayment at term-end, typically running 1–24 months with LTV capped at 60–65% (stretching to 75% with cross-collateral). Arrangement fees add 1–2% of the loan amount. Understanding these financial concerns [https://www.realestate-lisbon.com/buying-guide/financial-concerns] is critical before committing to any short-term structure.
[Table]
|
| Factor
| Bridge Loan
| Standard Mortgage
| Interest rate
| ~12%+ annualized
| 3.3–5.5%
| Term
| 1–24 months
| 7–30 years
| Repayment
| Interest-only + bullet
| Amortizing
| Speed to funds
| 2–4 weeks
| 6–12 weeks
| LTV
| 60–65% (up to 75%)
| 60–70% (up to 80%)
| DTI assessment
| Asset-focused
| Strict 30–35% of net income
[End Table]
Bridge financing makes strategic sense in five specific scenarios: selling a home-country property while simultaneously purchasing in Portugal; waiting for large international fund transfers or asset liquidation; buying at auction where rapid completion is mandatory; closing quickly before a standard mortgage approves (protecting a deposit under a CPCV promissory contract); and financing renovation before refinancing at improved valuation.
### Due Diligence
For most international buyers targeting a straightforward purchase, the standard long-term mortgage remains overwhelmingly preferable. Terms extend to 30 years (capped so the mortgage matures by age 75 for non-residents), with amortizing repayment structures and significantly lower all-in costs. Bridge financing should be reserved for genuine timing mismatches where the cost premium is justified by the deal's time sensitivity. The CPCV vs Escritura Guide [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] explains the legal framework protecting deposits during these transitions.
[Image: International buyer meeting with Portuguese mortgage specialist reviewing LTV options and financing structures for Lisbon property]
## How Does Residency Status Affect Borrowing Power?
Residency status is the single most consequential variable in Portuguese mortgage underwriting more impactful than nationality, income level, or bank choice. A non-resident faces 60–70% LTV; a fiscal resident accessing a primary-residence mortgage can reach 80–90% LTV. First-time buyers under 35 with Portuguese residency may qualify for 100% financing under Portugal's state guarantee scheme.
### Regulatory Context
NHR/IFICI holders who have established fiscal residency (183+ days per year, or habitual residence in Portugal) are classified as residents for mortgage purposes and access the full resident LTV grid. The tax regime itself is irrelevant to the bank, what matters is the borrower's fiscal registration status with Portuguese tax authorities. The original NHR ended for new applicants (transitional deadline March 31, 2025); its replacement, IFICI, is far narrower and limited to highly qualified professionals in innovation, research, and strategic sectors, excluding retirees and passive investors. Review our detailed NHR vs IFICI Tax Guide [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers] before committing to a residency strategy.
EU versus non-EU citizenship creates meaningful but secondary differences. EU citizens benefit from simpler NIF (Portuguese tax number) acquisition, easier bank-account opening, and marginally smoother underwriting. Non-EU citizens must appoint a fiscal representative for their NIF (cost approximately €350–550/year) and face stricter AML/KYC scrutiny. US citizens encounter FATCA-related reluctance from many retail banks, specialist brokers are often the only effective channel for American buyers. English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants] familiar with cross-border tax obligations can advise on NIF setup and residency conversion.
### Market Intelligence
How Portuguese banks assess foreign income follows conservative filters: the standard debt-service-to-income (DSTI) cap is 30–35% of net monthly income. Foreign-currency income faces a 10–20% haircut as a currency-risk buffer. Self-employment income is assessed on net profit (not gross revenue) from the most recent 2–3 years of tax filings. Rental or Airbnb income from the purchased property is not counted toward affordability and Portugal has no "buy-to-let mortgage" category.
## What Are the Five Most Effective Strategies to Maximize Leverage?
### Strategy 1: Convert to fiscal residency.
This is the highest-impact single action available to international buyers. Becoming a Portuguese tax resident by spending 183+ days in Portugal or establishing habitual residence will shift mortgage classification from non-resident (60–70% LTV) to resident (80–90% LTV for primary residence). The process involves obtaining a NIF, establishing a Portuguese address, and registering with tax authorities. Non-EU citizens can pursue a D7 visa or Digital Nomad visa as the legal residency pathway. Given the proposed 7.5% flat IMT with a two-year residency refund clause, this strategy now carries a double financial incentive. Consult expatriate tax specialists [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] to model your full worldwide income exposure before committing.
### Strategy 2: Leverage private banking and Lombard structures.
For HNW buyers unwilling or unable to establish residency, private banks accessible through specialist brokers can extend up to 100% LTV when the borrower places 30–50% of the loan value in assets under management. Variable-rate margins drop below 1%, and interest-only structures become available when net assets exceed 120% of the loan. One common arrangement: instead of paying a 30% deposit directly into the property, the equivalent sum is placed in a savings account with the lending bank, effectively cross-collateralizing the purchase while preserving liquidity.
### Strategy 3: Use specialist brokers to create bank competition.
Portuguese credit intermediation is regulated to be free for clients where brokers earn their fees from banks. Firms such as CAFIMO (€300M+ financed, 15+ bank network), Quinta Finance (25 years, BdP-registered), and Portugal Mortgage Brokers submit applications to multiple institutions simultaneously, creating competitive tension that pushes LTV upward and spreads downward. Brokers also know which institution is most receptive to specific profiles, self-employed income, US citizenship, corporate structures, knowledge that dramatically shortens the matching process. International buyer specialists [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients] on the ground in Lisbon can coordinate broker introductions as part of a broader acquisition team.
### Strategy 4: Front-load the banking relationship.
Opening a Portuguese bank account 3–6 months before applying builds transaction history that strengthens the file. Subscribing to cross-sell products (life insurance, home insurance, salary domiciliation) can reduce spreads measurably, where some banks advertise 0% spread for the first 5 years with full product bundling. Pre-approval before property search gives negotiating leverage with sellers and accelerates completion. The Mortgage Eligibility Scanner [https://www.realestate-lisbon.com/calculators/mortgage-scanner] provides a rapid initial read on your borrowing profile before engaging banks directly.
### Strategy 5: Explore home-country equity release.
Releasing equity from existing property abroad and purchasing in Portugal as a cash buyer eliminates Portuguese mortgage friction entirely with faster closing, stronger negotiating position, and no local borrowing constraints. The trade-off is foreign-currency exposure (borrowing in GBP or USD to buy in EUR) and the loss of potentially favorable Portuguese mortgage rates. For buyers with substantial home-country equity, a hybrid approach, partial equity release abroad combined with a smaller Portuguese mortgage, can optimize both leverage and flexibility. Understand the full scope of investment risks [https://www.realestate-lisbon.com/buying-guide/investment-risks] before committing to any cross-border leveraged structure.
## What Is the Mortgage Application Timeline for Non-Residents?
A non-resident mortgage in Portugal follows a 6–12 week critical path from application to completion. The timeline compresses significantly with pre-preparation.
The process begins with obtaining a NIF and opening a Portuguese bank account (same day to two weeks). Pre-approval takes 1–2 weeks and establishes a binding budget framework. Once a property is identified and a CPCV (promissory contract) signed, always with a mortgage contingency clause to protect the 10–20% deposit, the formal application triggers a 2–4 week bank review and independent property valuation (cost €300–800). Final underwriting adds 2–3 weeks, followed by a formal offer with a legally mandated 7-day reflection period. The escritura (notary deed signing) completes the purchase. Find a vetted notary [https://www.realestate-lisbon.com/notaries] well in advance to avoid scheduling delays at this critical stage.
### Due Diligence
Documentation requirements are substantial. Banks require passport, NIF, proof of address, 3–6 months of bank statements, 3 months of payslips (or 2–3 years of business financials for self-employed), home-country credit report, employer reference, complete tax returns, and proof of own capital for AML compliance. Property documents include the caderneta predial (tax register), certidão de teor (land registry certificate), and the signed CPCV. Non-EU documents may require apostille certification and certified Portuguese translation. Mandatory life insurance (covering 100% of the loan) and home/multi-risk insurance must be in place before disbursement. A qualified property acquisition lawyer [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition] should review all documentation before submission.
The cardinal rule is to start the mortgage process before identifying the property. Pre-approval transforms a speculative buyer into a confirmed one, shortens the CPCV-to-escritura window, and gives the broker maximum time to optimize terms across competing banks.
## Insider Perspective: The LTV Gap That Brokers Don't Advertise
The published LTV ceilings tell only part of the story. What experienced brokers working the Lisbon market [https://www.realestate-lisbon.com/lisbon-real-estate-neighborhoods] in 2025–2026 observe is a bifurcated landscape: banks with published non-resident caps of 70% are routinely approving 75–77% for applicants with six months of pre-established Portuguese banking history and salary domiciliation. The delta between the "advertised" cap and the negotiated approval is where specialist knowledge creates tangible financial value.
Market Intelligence: Properties in Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real] and Estrela where the buyer demographic skews heavily toward high-net-worth international clients show a pattern where sellers are increasingly willing to accept longer CPCV windows (90–120 days versus the standard 60) when buyers present bank pre-approval from Bankinter or BPI specifically. Sellers in these neighborhoods have been burned by non-resident buyers who underestimated Portuguese underwriting timelines; a pre-approval letter from a named bank with a stated LTV carries real negotiating weight.
Professional Coordination: For buyers pursuing the Lombard structure route, the sequencing matters. Engaging the private bank's wealth management division before the real estate search, not after! Private banks underwriting 90–100% LTV need 4–8 weeks to assess and approve the AuM placement structure. Attempting to layer this onto a property already under CPCV creates timeline pressure that typically results in either a worse term or a failed deal.
Regulatory Nuance: The proposed 7.5% flat IMT for non-residents, if enacted as drafted, will affect properties under approximately €600,000 most acutely and increasing tax costs versus the current progressive system. Properties above €600,000 see broadly neutral impact. Buyers near this threshold should model acquisition costs under both the current tiered system and the proposed flat rate, factoring in the two-year residency refund clause as a potential offset worth €45,000 on a €600,000 acquisition. Use the IMT Tax Calculator [https://www.realestate-lisbon.com/calculators/imt] to model both scenarios before signing any offer.
## Investment Considerations & Risk Factors
Market Volatility: Lisbon luxury property (€1M+) faces quarterly price fluctuations of 3–7% driven by interest rate changes and international buyer sentiment. National house prices reached a record €2,111/m² in Q3 2025 with 16% year-on-year growth, a pace that may not be sustainable through an extended period of stable ECB rates. Review current market trends news [https://www.realestate-lisbon.com/news/market-trends] for the latest pricing intelligence.
Holding Cost Reality: Annual ownership expenses (IMI at 0.3–0.8% annually, condominium fees, insurance, maintenance) typically range €45,000–75,000 for €2M properties, representing 2.25–3.75% of capital annually. These costs remain regardless of rental income or property appreciation. The maintenance costs guide [https://www.realestate-lisbon.com/buying-guide/maintenance-costs] provides a detailed breakdown of ongoing ownership expenses by property type.
Regulatory Evolution: Portugal's Golden Visa real estate route was closed in October 2023. The NHR regime ended for new applicants in March 2025. Short-term rental licensing (Alojamento Local) was liberalized nationally in November 2024 but Lisbon and Porto maintain local bans in central areas where AL exceeds 5% of housing stock. Future policy shifts remain possible as government balances foreign investment attraction against housing affordability concerns. Stay informed via our legal updates news [https://www.realestate-lisbon.com/news/legal-updates] section.
Exit Liquidity: Properties above €1M in Lisbon average 120–180 days to sale versus 60–90 days for mid-market segments. International buyer reliance (approximately 40% of Lisbon transactions) creates liquidity sensitivity to global economic conditions and exchange-rate movements.
Currency Exposure: Non-EU buyers face EUR/USD and EUR/GBP exchange-rate risk. A 10% currency move impacts acquisition costs by €100,000 on a €1M purchase. The 10–20% haircut that Portuguese banks apply to foreign-currency income for DSTI calculations compounds this exposure during the underwriting phase.
## Privacy & Transaction Security
All client consultations and transactions maintain strict confidentiality protocols:
Discretion Standards:
• Off-market property access via private network (no public listing exposure)
• Encrypted communication channels for all financial documentation
• NDA-protected seller negotiations and due diligence processes
• Secure title verification through vetted legal partners only
• No client information shared with third parties without explicit written consent
GDPR Compliance: All data handling follows Portuguese DPO-certified protocols with EU data residency guarantees.
## Common Due Diligence Oversights
### Underestimating Total Cash Requirements
Many international buyers model only the deposit when planning liquidity. Closing costs for non-residents such as IMT, stamp duty (0.8%), notary fees, legal fees, and bank charges add 8–12% of purchase price. On a €1M property, this means €80,000–€120,000 in addition to the deposit. The True Cost Calculator [https://www.realestate-lisbon.com/calculators/true-cost] at realestate-lisbon.com models total cash requirements under both resident and non-resident structures.
### Treating Pre-Approval as Optional
Portuguese sellers, particularly in prime Lisbon neighborhoods, have become increasingly unwilling to enter CPCV contracts with buyers who cannot demonstrate formal pre-approval. Without pre-approval, the 10–20% deposit paid under the CPCV is exposed during the underwriting phase. Mortgage contingency clauses offer protection, but their enforceability depends on the specific language, requiring experienced legal counsel specializing in due diligence [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence].
### Overlooking the Broker-Versus-Direct Bank Decision
Applying directly to one bank eliminates the competitive tension that drives LTV and spread improvements. Portuguese credit intermediaries are regulated to charge fees to banks, not borrowers, making specialist broker engagement cost-neutral for the buyer while potentially unlocking better terms, higher LTV approvals, and faster processing across a 15+ bank network.
### Misreading IFICI Eligibility
Buyers attracted by IFICI (the NHR replacement) should verify sector eligibility before committing to a fiscal residency strategy. IFICI is limited to professionals in innovation, research, and strategic sectors as defined by AICEP. Retirees and passive investors are excluded. An incorrect residency conversion that fails IFICI criteria leaves the buyer with full progressive Portuguese income tax exposure, up to 53, on worldwide income. Engage NHR and IFICI tax specialists [https://www.realestate-lisbon.com/professionals/accountants-nhr-tax-regime] before initiating any residency application.
## Strategic Implementation Steps
### Immediate Actions (Week 1–2):
• Financial Modeling: Use the Mortgage Strategy Calculator [https://www.realestate-lisbon.com/calculators/mortgage] at realestate-lisbon.com to model LTV scenarios under resident versus non-resident classification and project total acquisition costs including 2025–2026 IMT rates
• Tax Advisory: Engage a cross-border tax specialist to assess IFICI eligibility versus non-resident status and model worldwide income tax exposure under both scenarios
• NIF Application: Initiate Portuguese tax number application immediately, 4–6 week processing is required before property offers, and banking relationship pre-qualification requires an active NIF
### Short-Term Actions (Month 1–2):
• Broker Engagement: Contact a BdP-registered credit intermediary to initiate multi-bank pre-approval and identify optimal lender for the buyer's specific profile (nationality, income structure, property type)
• Portuguese Bank Account: Open account immediately to begin building transaction history; 3–6 months of history materially improves underwriting outcomes
• Lombard Assessment: If total investable assets exceed €2M, engage private banking division for Lombard structure assessment before committing to a standard mortgage path
### Pre-Purchase Actions (Month 2–4):
• Pre-Approval Confirmation: Obtain written pre-approval from at least two banks before signing any CPCV, establishing competitive leverage and timeline certainty
• Legal Counsel: Engage Portuguese lawyer [https://www.realestate-lisbon.com/real-estate-lawyers] for CPCV review, ensuring mortgage contingency clauses are properly drafted to protect deposits during underwriting
• IMT Scenario Planning: Model acquisition costs under both current progressive IMT and proposed 7.5% flat rate; factor in two-year residency refund clause eligibility
## Frequently Asked Questions
What is the maximum LTV available to non-residents in Portugal in 2026?
The highest standard LTV available to non-residents from Portuguese retail banks is currently 80%, offered by Bankinter and BPI for primary residence purchases. The majority of banks cap non-resident LTV at 70–75%. Private banking Lombard structures can reach 100% LTV when the borrower places 30–50% of the loan value in assets under management with the lending institution. Use the Mortgage Eligibility Scanner [https://www.realestate-lisbon.com/calculators/mortgage-scanner] to assess which LTV tier your profile qualifies for.
How does becoming a Portuguese tax resident change mortgage access?
Fiscal residency established by spending 183+ days in Portugal or registering habitual residence reclassifies the borrower from non-resident (60–70% LTV) to resident (80–90% LTV for primary residence) for mortgage underwriting purposes. The bank's analysis focuses on fiscal registration status, not the specific tax regime (NHR, IFICI, or standard). First-time buyers under 35 who establish residency may access 100% financing under the state guarantee scheme.
What are current mortgage rates for non-residents in Portugal?
As of February 2026, with 3-month Euribor at 1.999% and the ECB deposit rate at 2.00%, all-in variable mortgage rates for non-residents range approximately 3.3–4.5% (Euribor plus bank spreads of 1.0–2.0%). Fixed rates across various terms range 3.5–4.5%. Mixed-rate products (fixed for 5 years, then variable) have become the most popular structure and offer initial rates of 2.7–3.5%.
Can US citizens obtain mortgages in Portuguese banks?
US citizens face significant friction with Portuguese retail banks due to FATCA compliance requirements. Several major retail banks decline American applicants. Specialist brokers with established relationships at FATCA-compliant institutions, and private banking channels accessible through intermediaries, represent the most effective path for American buyers. Expect higher documentation requirements and longer processing timelines regardless of channel. International buyer agents [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients] with US client experience can provide broker referrals suited to your profile.
What is bridge financing and when does it make sense for Lisbon property buyers?
Bridge financing (crédito ponte) is a short-term, interest-only loan (1–24 months) that closes a timing gap, for example when a buyer needs to complete in Portugal before selling property elsewhere. Rates start around 12% annualized versus 3.3–5.5% for standard mortgages, making bridge financing viable only when the deal's time sensitivity justifies the cost premium. Specialist international lenders (not Portuguese retail banks) provide this product.
What closing costs should non-residents budget for a Lisbon property purchase?
Non-resident closing costs typically represent 8–12% of the purchase price. Primary components are IMT (property transfer tax: currently progressive up to 7.5% for non-residents, potentially becoming a flat 7.5% under pending legislation), stamp duty (0.8%), notary and land registry fees (approximately 0.5%), legal fees (0.5–1.0%), and bank arrangement and valuation fees (0.3–0.8%). The True Cost Calculator [https://www.realestate-lisbon.com/calculators/true-cost] at realestate-lisbon.com models these figures against specific purchase prices.
How long does the mortgage process take for non-residents in Portugal?
The typical timeline from initial application to escritura (notary deed completion) is 6–12 weeks. Pre-approval takes 1–2 weeks. Formal bank review and property valuation after CPCV signing requires 2–4 weeks. Final underwriting and offer issuance adds 2–3 weeks, followed by the mandatory 7-day reflection period. Buyers who begin the process before identifying a property—obtaining pre-approval and NIF in advance—can compress the post-CPCV timeline to 6–8 weeks.
What are the five most effective strategies to maximize LTV in Portugal?
The five strategies are: (1) Convert to fiscal residency to raise LTV from 60–70% to 80–90% for primary residence; (2) Leverage private banking and Lombard structures for up to 100% LTV; (3) Use specialist brokers to create bank competition and drive better terms; (4) Front-load the banking relationship by opening a Portuguese account 3–6 months before applying; (5) Explore home-country equity release for a cash purchase or hybrid approach eliminating local borrowing constraints.
How does IFICI affect fiscal residency strategy for mortgage borrowers?
IFICI (the NHR replacement) is far narrower than the original NHR and limited to highly qualified professionals in innovation, research, and strategic sectors, excluding retirees and passive investors. The bank's mortgage classification only depends on fiscal registration status, not on IFICI eligibility. However, buyers who incorrectly assume IFICI eligibility risk full progressive Portuguese income tax exposure of up to 53% on worldwide income. Consult NHR/IFICI tax specialists [https://www.realestate-lisbon.com/professionals/accountants-nhr-tax-regime] before initiating any residency conversion.
What is the LTV gap that brokers don't typically advertise?
Banks with published non-resident caps of 70% are routinely approving 75–77% for applicants with six months of pre-established Portuguese banking history and salary domiciliation. This delta between the advertised cap and the negotiated approval is where specialist knowledge creates tangible financial value. In prime neighborhoods like Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real], sellers are increasingly requiring pre-approval letters from named banks with stated LTV before entering CPCV negotiations.