Portuguese Real Estate Paradigm: Capital Preservation Analysis
By Pieter Paul Castelein
Published: March 7, 2026
Category: Market Intelligence & Analysis
**
# Portuguese Real Estate Paradigm: Capital Preservation Analysis
Last Updated: February 9, 2026
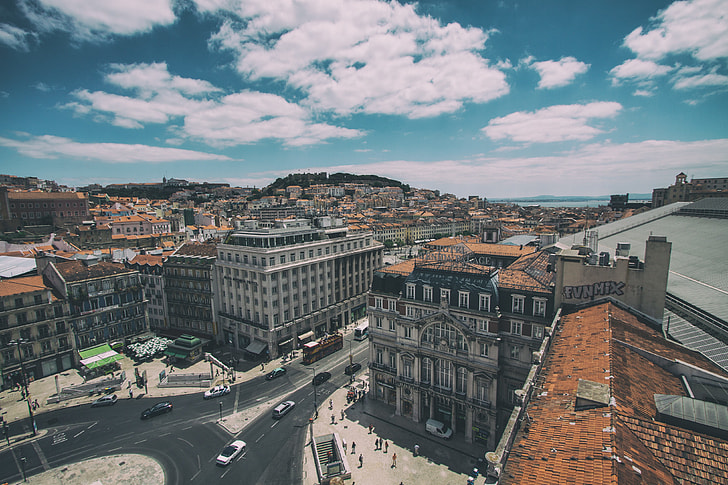
[Image: Lisbon waterfront skyline showing modern and historic architecture representing the 2026 real estate market transformation]
## Value Box
**Capital Preservation Intelligence:** Portuguese property market structural transformation analysis for €650K-€3M international buyers.
• Lisbon residential assets exceeded €6,000/m² threshold in January 2026, representing 120% nominal appreciation since 2015 and foreign buyer premium of 62% over domestic transactions
• National rental market surged 16% year-over-year while existing contracts capped at 2.24% adjustment coefficient under NRAU regulations, creating regulatory arbitrage opportunity
• Non-resident IMT tax [https://www.realestate-lisbon.com/calculators/imt] restructured to flat 7.5% rate versus progressive domestic scale, with Euribor stabilization at 3.22% average mortgage rates [https://www.realestate-lisbon.com/calculators/mortgage] down from 2023 peak of 4.65%
## Key Facts: Market Fundamentals January 2026
• **Lisbon median price:** €6,065/m² for high-demand residential (€650,000 average Greater Lisbon transaction)
• **National rent acceleration:** 16% year-over-year versus 11.5% sales price growth
• **Foreign buyer premium:** International transactions average €2,415/m² versus domestic €1,794/m²
• **Gross rental yields:** 3.2-4.1% in prime Lisbon areas after transaction cost adjustment
• **Supply deficit:** 28,000 units licensed annually versus 200,000 in early 2000s peak
• **Labor shortage:** 90,000 construction worker deficit constraining new inventory
• **ECB deposit rate:** Stabilized at 2.00% after 2023-2024 tightening cycle
• **Portugal GDP projection:** 2.2% growth in 2026, supported by PRR fund disbursement
## Executive Summary: From Speculative Momentum to Strategic Positioning
The Portuguese real estate market entered 2026 having completed a fundamental transition from recovery-phase speculation to mature capital preservation asset class. Three concurrent signals define this structural shift: Lisbon's breach of the €6,000/m² psychological threshold, a 16% national rental surge creating regulatory arbitrage opportunities, and record transaction volumes in the high-end segment despite Golden Visa real estate pathway elimination in 2023-2024.
This convergence reflects perfect supply inelasticity meeting sustained international demand [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients]. The market no longer follows cyclical patterns but exhibits characteristics of Tier 1 European investment cities where domestic affordability constraints become structurally decoupled from pricing mechanisms.
For portfolio managers allocating €650,000 to €3,000,000 in European residential assets, Portugal presents a bifurcated opportunity: prime capital preservation in established districts with 3-4% yields, or strategic positioning in regeneration corridors offering 17-32% annual appreciation with infrastructure-driven anticipation premiums.
[Image: Lisbon neighborhood comparison map showing price per square meter across different districts including prime areas and emerging regeneration zones]
## The €6,000/m² Threshold: Psychological and Economic Milestone
January 2026 marked Lisbon's entry into the league of premium European capitals when median asking prices for high-demand residential assets settled at €6,065 per square meter. This milestone represents the culmination of 120% nominal appreciation since 2015 and signals the market's transition from emerging to established investment destination.
Recent analysis of Lisbon's record-breaking price surge [https://www.realestate-lisbon.com/news/market-trends/lisbon-leads-record-breaking-property-price-surge-in-early-2026-what-investors-need-to-know] demonstrates this threshold breach coincides with Greater Lisbon average purchase prices reaching €650,000, reflecting market dominance by institutional investors [https://www.realestate-lisbon.com/professionals/real-estate-agents-luxury-properties] and high-net-worth international buyers operating outside local affordability constraints.
### Internal Market Segmentation and Value Migration
The Lisbon metropolitan area [https://www.realestate-lisbon.com/lisbon-real-estate-neighborhoods] exhibits pronounced internal divergence where prime districts maintain stable premiums while emerging zones experience hyper-growth driven by infrastructure spillover and urban regeneration mandates.
**Prime District Stability:** Santo António parish, encompassing Avenida da Liberdade, commands €6,800-€10,000/m² with ultra-prime new construction exceeding €12,000/m². These areas deliver capital preservation rather than aggressive appreciation, attracting family offices and institutional buyers prioritizing stability over growth.
**Regeneration Corridor Acceleration:** The eastward capital migration toward Marvila [https://www.realestate-lisbon.com/lisbon/marvila] and Beato produced 32% year-over-year appreciation as these formerly industrial zones transition to technology hubs and luxury residential corridors. This represents the highest growth rate in the Lisbon metropolitan area and offers strategic positioning opportunities for investors with 5-10 year holding periods.
### Neighborhood Performance Matrix January 2026:
[Table]
|
| District/Neighborhood
| Median Price (€/m²)
| Annual Growth
| Primary Investment Driver
| Santo António / Av. Liberdade
| €8,200 – €10,000+
| 4.2%
| Capital preservation, ultra-luxury
| Chiado [https://www.realestate-lisbon.com/lisbon/chiado] / Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real]
| €7,500 – €9,500
| 3.8%
| Scarcity premium, tourism infrastructure
| Parque das Nações
| €6,000 – €6,300
| 17.0%
| Modern infrastructure, family demographics
| Marvila / Beato
| €2,500 – €4,500
| 32.0%
| Urban regeneration, tech sector migration
| Benfica
| €3,500 – €5,000
| 17.0%
| Domestic middle class, supply gap arbitrage
| Avenidas Novas
| €3,500 – €6,000
| 8.5%
| Centrality, institutional rental demand
[End Table]
### Turn-Key Premium and Post-Pandemic Requirements
Newly constructed properties command 15-25% premiums over existing stock, driven by mandatory energy efficiency standards (Class A/B certification), high-capacity fiber infrastructure, and dedicated home-office spaces reflecting post-pandemic lifestyle migration patterns.
Investors increasingly prioritize properties requiring minimal renovation given acute labor shortages and construction cost inflation plaguing the Portuguese building sector. This turn-key preference creates bifurcated pricing where renovation-ready properties trade at significant discounts to move-in condition assets despite comparable square meterage.
## The 16% Rental Surge: Regulatory Arbitrage and Yield Dynamics
While property sale prices sustained steady appreciation, January 2026 witnessed aggressive rental market acceleration with national rents surging 16% year-over-year to €1,450 monthly average. Portugal's rental market heating with 16% surge [https://www.realestate-lisbon.com/news/market-trends/portugal-s-real-estate-market-heats-up-rents-soar-16-in-january-2026-lisbon-prices-hit-new-highs] reveals Lisbon specifically hit €1,800 average, creating significant imbalance between rental costs and local purchasing power.
This 16% growth outpaced the 11.5% national increase in sales prices, a dynamic typically signaling either impending correction or structural transition toward rental-dominated urban society where homeownership becomes progressively inaccessible to middle-class households.
### The 2.24% Coefficient Regulatory Paradox
A critical tension defines the 2026 rental market: the divide between existing lease agreements and new contracts under the New Urban Lease Regime (NRAU). The official rent adjustment coefficient for 2026 was set at 1.0224, permitting landlords to increase existing rents by maximum 2.24% based on Consumer Price Index (CPI) excluding housing for the 12 months preceding August 2025.
This 2.24% cap applies exclusively to ongoing contracts. Properties returning to market after vacancy enable landlords to set prices reflecting the broader 16% market surge, effectively front-loading potential future regulatory constraints. Furthermore, landlords who have not adjusted rents in the previous three years can apply cumulative coefficients, resulting in one-time increases exceeding 11% for existing tenants.
**Regulatory Arbitrage Opportunity:** This creates a bifurcated rental market where:
• Existing contracts adjust at 2.24% annually under NRAU protection
• New contracts price at market rates 16% above prior-year baselines
• Properties held vacant during appreciation cycles can reset at full market pricing
For investors, this suggests strategic value in acquiring properties with existing below-market leases where planned vacancy and repositioning can capture the regulatory spread.
### Rental Yield Compression and Capital Appreciation Focus
Despite double-digit rental growth, faster capital value appreciation in Lisbon compressed gross rental yields [https://www.realestate-lisbon.com/calculators/rental-yield] to 3.2-4.1% in prime areas. This low-yield environment confirms investors no longer chase immediate cash flow but view Lisbon residential assets as safe-haven instruments for long-term capital appreciation.
**Yield Calculation Incorporating Transaction Costs:**
Gross Yield = (Annual Rental Income / (Purchase Price + Transaction Costs)) × 100
With transaction costs (IMT, Stamp Duty, Notary) averaging 7-10% of purchase price, an investor acquiring a €650,000 apartment in Lisbon requires minimum annual rent of €27,300 to achieve modest 4% gross yield before taxes and maintenance.
This yield compression reflects market maturity where capital preservation and appreciation potential supersede income generation as primary investment objectives [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties].
[Image: Infographic showing IMT tax rate comparison between domestic and non-resident buyers across different property value brackets in Portugal]
## International Buyer Profile: The 62% Foreign Premium
The international investment profile in Portugal reached unprecedented maturity in 2026 following the 2023-2024 removal of real estate investment options from the Golden Visa program [https://www.realestate-lisbon.com/guides/golden-visa-alternatives-in-lisbon-a-2025-buyers-guide]. This policy shift successfully dampened speculative flipping without collapsing broader market fundamentals. Lisbon property prices exceeding €6,000/m² records [https://www.realestate-lisbon.com/news/market-trends/lisbon-property-prices-hit-new-record-in-january-2026-exceeding-6-000-m] document the market transition to lifestyle-driven buyer cohorts from United States, United Kingdom, and Northern Europe.
### Quantifying the Foreign Premium
January 2026 data reveals a staggering foreign buyer premium in the Lisbon market. International buyers paid 62% more than domestic buyers for residential property on average. While domestic transactions in first half 2025 averaged €1,794/m², international buyers paid €2,415/m². By January 2026, this gap likely widened as foreign demand concentrated on high-specification modern apartments in prime coastal and historic zones.
This premium reflects fundamental differences in buyer psychology and capital allocation:
• **Domestic buyers:** Income-constrained, mortgage-dependent, prioritize price per square meter
• **International buyers:** Capital preservation-focused, cash or foreign financing, prioritize quality and location over absolute pricing
### Tax and Residency Framework Evolution
The legislative landscape for international buyers underwent fundamental reshaping. The original Non-Habitual Resident (NHR) regime was replaced by "NHR 2.0" (IFICI - Incentive for Scientific Research and Innovation) [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers], which restricts benefits to high-value professionals in science, technology, and academia. This shift funnels demand into urban centers like Lisbon and Porto where these professionals can integrate into existing economic clusters.
The 2026 State Budget introduced a flat 7.5% IMT (Property Transfer Tax) for non-resident buyers of residential property, intended to cool high-end market activity while generating revenue for affordable housing initiatives. This contrasts with the progressive scale used for domestic primary residences:
### IMT Rate Structure Comparison 2026:
[Table]
|
| Property Value (€)
| Domestic Primary Residence
| Non-Resident/Second Home
| Up to €106,346
| 0% (Exempt)
| 7.5%
| €106,346 – €142,618
| 2.0%
| 7.5%
| €142,618 – €194,458
| 5.0%
| 7.5%
| €194,458 – €330,500
| 7.0%
| 7.5%
| €330,500 – €660,982
| 8.0%
| 7.5%
| €660,982 – €1,150,853
| 6.0%
| 7.5%
| Above €1,150,853
| 7.5%
| 7.5%
[End Table]
For international buyers in the €650,000-€1,500,000 range, this flat rate simplifies tax planning but increases acquisition costs by approximately 0.5-1.5% versus previous progressive structures.
## Macroeconomic Resilience: Euribor Stabilization and Growth Fundamentals
The continued property price surge operates within a remarkably stable macroeconomic backdrop. After punishing interest rate hikes during 2023-2024, the European Central Bank pivoted toward neutral stance with deposit rates stabilizing around 2.00% by early 2026.
### Mortgage Market Normalization
Euribor stabilization—specifically 3-month and 6-month indices—brought unprecedented clarity to Portuguese mortgage markets [https://www.realestate-lisbon.com/buying-guide/financial-concerns]. Borrowing costs for new home loans stabilized at 3.22% average, a significant reduction from 2023 peak of 4.65%.
Variable-rate mortgages continue dominating the market though structures have become more sophisticated. Banks increasingly offer "mixed-rate" products providing fixed rates for initial 2-10 years before transitioning to Euribor-linked variable rates. For international investors, Portuguese banks typically offer loan-to-value (LTV) ratios of 60-70%, while domestic residents can access 80-90% in certain government-backed programs for young buyers.
### GDP Growth and Infrastructure Investment
Portugal's economy is projected to grow 2.2% in 2026, outperforming many Eurozone peers. This growth is heavily supported by peak disbursement of EU Recovery and Resilience Plan (PRR) funds directed into large-scale infrastructure projects. Most significant for real estate sector include:
• **Lisbon Metro Red Line extension to Alcântara:** Creating localized anticipation premiums
• **Porto Metro Ruby Line:** Generating corridor-specific appreciation patterns
• **National housing construction incentives:** 6% VAT rate on new construction for properties valued up to €648,000
These infrastructure investments create predictable appreciation patterns along transportation corridors, offering strategic positioning opportunities for investors with medium-term horizons.
## The Supply-Side Crisis: Structural Bottleneck Dynamics
While demand remains robust, the Portuguese market is fundamentally constrained by chronic lack of new inventory. Analysts identify a "decade of under-building" as primary cause of current price levels. In early 2000s, approximately 200,000 new homes were licensed annually. By 2024, this plummeted to just 28,000 units.
### Construction Labor Deficit and Cost Inflation
The construction sector [https://www.realestate-lisbon.com/constructors] in 2026 faces a deficit exceeding 90,000 workers. This labor shortage, combined with elevated energy and material costs, made new construction slow and expensive. Developers naturally pivoted toward high-margin luxury projects to absorb these costs, leaving profound under-supply of affordable middle-market housing.
Average construction cost per square meter continued rising in 2026, creating situations where even with government incentives like 6% VAT rate on new construction, developers struggle to bring units to market at price points accessible to average Portuguese families.
### Legislative Response: Simplex and Construir Portugal
In response to supply crisis, the government implemented "Simplex for Urban Licensing" and broader "Construir Portugal" strategy including:
**VAT Reduction:** VAT on new construction [https://www.realestate-lisbon.com/buying-guide/new-builds-risks] reduced from 23% to 6% for properties valued up to €648,000
**Land Reclassification:** Reclassifying rural land for urban use, provided at least 70% reserved for affordable public housing
**Licensing Streamlining:** Reducing administrative deadlines and increasing developer and technical professional responsibility to speed project starts
Despite these efforts, the "Empty Housing" paradox remains significant challenge. In Lisbon, thousands of units remain vacant because owners, often risk-averse elderly landlords distrust the legal environment or find tax burden of selling or renting at market rates economically irrational.
[Image: Map of Portugal highlighting regional property price growth with Azores, Madeira, Porto, and emerging secondary cities marked with growth percentages]
## Regional Hotspots: Beyond the Lisbon-Algarve Axis
As Lisbon prices reached record highs, both domestic and international capital sought value in secondary cities and autonomous regions. The 2026 market is characterized by polycentric growth patterns.
### The Azores and Madeira Surge
Autonomous regions experienced the most dramatic volatility in early 2026. Madeira witnessed a 21.4% monthly rent increase in January, while São Miguel in the Azores recorded staggering 50% year-over-year growth in rental values. Property prices in the Azores jumped 19.8% year-over-year, leading national rankings for appreciation.
This is driven by combination of extremely limited supply and sudden surge in interest from North American "lifestyle seekers" pursuing remote, nature-oriented residency options.
### The Rise of the North: Porto, Braga, and Coimbra
Porto remains highly attractive alternative to Lisbon with median sale prices around €2,950/m², offering 40% discount compared to central Lisbon. The city's rental market is stabilizing with 3% year-over-year increase in January 2026, following double-digit gains in previous years.
Secondary cities like Coimbra and Setúbal saw largest price accelerations in 2025-2026 as families and young professionals were displaced from Lisbon metropolitan area. Coimbra witnessed 28.9% annual house price increase, reflecting growing status as residential and educational hub.
### Regional Performance Matrix January 2026:
[Table]
|
| Region/Municipality
| Avg. Sale Price (€)
| Monthly Change
| Annual Change
| Cascais [https://www.realestate-lisbon.com/cascais/real-estate-agents]
| €1,350,000
| +12.5%
| +22.7%
| Calheta (Madeira)
| €950,000
| +5.6%
| +18.8%
| Loulé (Algarve)
| €813,200
| N/A
| +36.7%
| Oeiras [https://www.realestate-lisbon.com/oeiras/real-estate-agents]
| €725,000
| +3.6%
| +11.5%
| Lisbon
| €720,000
| +5.9%
| +16.1%
| Porto
| €420,000
| -2.3%
| +7.7%
| Coimbra
| €290,000
| N/A
| +28.9%
| Leiria
| €337,000
| N/A
| +20.4%
[End Table]
## Insider Perspective: Strategic Positioning in Infrastructure Corridors
**Market Intelligence:** Properties within 400 meters of planned Lisbon Metro Red Line extension stations in Alcântara are trading at €5,200-5,800/m² as of January 2026, representing a 12-18% discount to established Chiado pricing despite comparable build quality and square meterage. This gap is expected to compress by 40-60% following station completion in Q4 2027, based on historical patterns observed along Green Line extension to Telheiras (2017-2019).
Marvila's transformation from industrial zone to tech hub has created micro-market segmentation where properties within 200 meters of planned Hub Criativo do Beato command premiums of €800-1,200/m² over comparable units five blocks away. This premium has widened 32% since Q1 2025 as international buyers from Berlin and Amsterdam tech sectors prioritize walkability to coworking infrastructure.
**Professional Coordination:** For €1M+ Lisbon transactions, coordinate your Portuguese lawyer (advogado) [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition] and fiscal representative before making offers. Pre-cleared NIF (tax identification number) applications and AIMA (immigration agency) residency paperwork reduce escritura (deed signing) [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] timelines from 120 days to 75-85 days. This timeline compression provides negotiating leverage in competitive bidding situations where sellers prioritize transaction certainty.
Engage structural engineers [https://www.realestate-lisbon.com/professionals/civil-engineers-structural-engineering] for pre-purchase building inspections [https://www.realestate-lisbon.com/professionals/home-inspectors-pre-purchase-inspections] on properties constructed pre-1980, particularly in Alfama [https://www.realestate-lisbon.com/lisbon/alfama], Mouraria [https://www.realestate-lisbon.com/lisbon/mouraria], and Graça [https://www.realestate-lisbon.com/lisbon/graca] parishes. Lisbon's seismic risk and aging infrastructure create material undisclosed liability risks. Budget €3,000-5,000 for comprehensive structural assessment [https://www.realestate-lisbon.com/professionals/home-inspectors-structural-inspections] versus standard habitability certificate review.
**Regulatory Nuance:** Lisbon building permits approved in 2024 include mandatory solar installations under 2023 municipal ordinance, adding €15,000-25,000 to new construction budgets but improving ESG (Environmental, Social, Governance) credentials for institutional buyers and enhancing asset value for European Taxonomy-aligned investment funds.
Cascais municipality [https://www.realestate-lisbon.com/cascais/pdm] introduced stricter AL (Alojamento Local - short-term rental) licensing requirements in December 2025, limiting new registrations to properties with dedicated parking and minimum 60m² footprint. This creates artificial scarcity for compliant properties and premium pricing for grandfathered AL licenses in the €1M+ segment.
## Investment Considerations & Risk Factors
**Market Volatility:** Lisbon luxury property (€1M+) experiences quarterly price fluctuations of 3-7% driven by interest rate changes and international buyer sentiment shifts. Q3 2025 witnessed 4.2% adjustment in prime Cascais listings as ECB rates stabilized. Portfolio managers should model 5-10% annual valuation variance for marked-to-market accounting purposes.
**Holding Cost Reality:** Annual property ownership expenses (IMI property tax, condominium fees, insurance, maintenance) typically range €45,000-75,000 for €2M properties, representing 2.25-3.75% of capital annually. These costs remain regardless of rental income generation or appreciation. Budget an additional 1.5-2.0% annually for unexpected repairs and regulatory compliance updates.
**Regulatory Evolution:** Portugal's Golden Visa, NHR programs, and AL licensing underwent significant changes during 2023-2025. Future policy shifts remain possible as government balances foreign investment attraction against housing affordability concerns and social stability objectives. Monitor parliamentary discussions on rental price controls and foreign buyer restrictions.
**Exit Liquidity:** Properties exceeding €1M in Lisbon average 120-180 days to sale versus 60-90 days for mid-market segments. International buyer reliance (18-22% of transactions) creates liquidity sensitivity to global economic conditions, currency fluctuations, and geopolitical risk perceptions. Structure acquisitions with minimum 5-year holding periods to avoid forced sales during market contractions.
**Currency Exposure:** Non-EU buyers face EUR/USD and EUR/GBP exchange rate risk throughout acquisition and holding periods. A 10% currency move impacts acquisition costs by €100,000 on a €1M purchase. Consider hedging strategies or natural currency matching where rental income aligns with home-country expenses.
## Privacy & Transaction Security
All client consultations and transactions maintain strict confidentiality protocols essential for high-net-worth international buyers:
**Discretion Standards:**
• Off-market property access via private network with no public listing exposure
• Encrypted communication channels for all financial documentation transmission
• NDA-protected seller negotiations and due diligence processes [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence]
• Secure title verification through vetted legal partners exclusively
• No client information shared with third parties without explicit written consent
• Beneficial ownership structures coordinated with international tax advisors
**GDPR Compliance:** All data handling follows Portuguese DPO-certified protocols with EU data residency guarantees. Transaction records maintained on encrypted servers with multi-factor authentication access controls.
## Socio-Economic Impact: Displacement and Public Sentiment
The record-breaking price surge precipitated severe socio-economic crisis. In 2025 survey, 43.4% of Portuguese residents identified housing crisis as the country's biggest issue. The "transnational gentrification" of Lisbon and Porto led to direct displacement of low-income, long-time residents, a process linked to adverse health impacts, ontological insecurity, and residential alienation.
### The Dual Displacement Mechanism
**Price-Out Effect:** Market rents averaging €11-20/m² in Lisbon are incompatible with median Portuguese salary levels, forcing younger generations and middle-class families to migrate to "second line" suburban municipalities like Almada, Loures, or Seixal. This creates extended commute burdens and family separation patterns.
**Lending Barriers:** Despite falling interest rates, strict lending controls (LTV and debt-to-income ratios) mean only those with significant existing equity or high foreign incomes can secure financing for properties in desirable central neighborhoods. First-time buyers are effectively excluded from prime districts.
### Political Response and Social Tension
Late 2025 and early 2026 witnessed hundreds of protestors in downtown Lisbon demanding rent controls and aggressive legislative intervention. Public sentiment is increasingly hostile toward "financialization" of housing where homes are treated as investment assets rather than fundamental rights.
The 2026 State Budget faces intense scrutiny to deliver affordable housing promises, with European Commission also preparing an "Affordable Housing Plan" for spring 2026 presentation. Investors should monitor political developments for potential regulatory impacts on rental income, capital gains taxation, and foreign ownership restrictions.
[Image: Chart showing strategic investment opportunities in Portugal including regeneration hubs, infrastructure corridors, and regional value plays with expected return timelines]
## Strategic Investment Opportunities 2026
For portfolio managers, the 2026 Portuguese property market represents transition from "high-growth speculation" to "stable, long-term positioning." While effortless double-digit appreciation across all segments has ended, market fundamentals remain robust due to unyielding supply deficit.
### High-Conviction Opportunities
**Regeneration Hubs:** Neighborhoods like Marvila in Lisbon and Campanhã in Porto offer significant upside potential as they benefit from multi-year urban renewal projects. Target properties within 400-meter radius of planned infrastructure improvements with 5-7 year holding horizons.
**The Anticipation Premium Strategy:** Investing along corridors of new metro lines (Red Line extension in Lisbon, Ruby Line in Porto) provides predictable appreciation paths. Historical data from previous extensions suggests 40-60% gap compression between peripheral and established districts within 24 months of station completion.
**Silver Coast Value Play:** Coastal towns like Nazaré and São Martinho do Porto offer yields of 4-6% and prices significantly below Algarve comparables, appealing to growing community of remote workers and retirees. Target turnkey properties requiring minimal renovation given construction labor constraints.
**Tax-Efficient Rental Housing:** Leveraging 10% IRS (income tax) rate for "moderate rent" properties can provide stable, lower-tax income streams for domestic and resident landlords. This requires rents set below market rates in exchange for favorable tax treatment, suitable for long-term capital appreciation strategies.
### Critical Risk Factors
**Political and Policy Risk:** Potential for aggressive rent controls or restrictions on short-term rentals (AL) as government faces mounting social pressure. Monitor parliamentary discussions and municipal ordinances for regulatory changes affecting income generation capacity.
**Construction Risk:** Project delays and cost overruns due to labor shortages make off-plan investing [https://www.realestate-lisbon.com/off-plan] riskier than previous cycles. Require completion guarantees, construction insurance, and developer financial stability verification before committing capital to pre-construction projects.
**Affordability Ceiling:** In certain prime districts, prices may have reached "affordability ceiling" where even international demand cannot sustain further rapid growth without significant improvement in rental yields or economic fundamentals. Chiado and Santo António districts show characteristics of price maturity with sub-5% annual appreciation expected.
## FAQ: Strategic Questions for Portfolio Managers
What drives the 62% foreign buyer premium in Lisbon?
International buyers prioritize capital preservation, location quality, and modern specifications over price-per-square-meter optimization that constrains domestic buyers. Foreign purchasers typically acquire with cash or foreign-currency financing, removing mortgage affordability constraints. Additionally, international buyers concentrate in prime districts where scarcity premiums are highest, skewing average transaction prices upward.
How does the 2.24% rental adjustment cap create investment opportunities?
The NRAU regulatory framework caps existing contract adjustments at 2.24% while permitting market-rate pricing for new contracts. Investors can acquire properties with below-market leases, wait for natural tenancy turnover, then reset rents at full market rates capturing the regulatory spread. This strategy works best in high-demand neighborhoods with strong tenant turnover patterns.
What is the impact of NHR 2.0 (IFICI) on real estate demand?
NHR 2.0 restricts tax benefits to high-value professionals in science, technology, and academia, funneling demand into urban centers like Lisbon and Porto where these professionals integrate into economic clusters. This creates sustained demand pressure in specific neighborhoods near universities, research institutions, and tech hubs while reducing speculative buyer interest in resort areas.
How should non-EU buyers structure acquisitions given currency risk?
Consider: 1) Natural hedging where euro rental income offsets home-country expenses, 2) Currency forward contracts to lock exchange rates at acquisition, 3) Financing in euros to match asset and liability currencies, 4) Diversified currency portfolio approach where Portuguese property represents one component of multi-currency wealth allocation. Consult international tax advisors [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] on optimal beneficial ownership structures.
What transaction timeline should investors expect in Lisbon?
Standard transactions require 90-120 days from offer acceptance to escritura (deed signing). This includes: NIF application (2-3 weeks), opening Portuguese bank account (1-2 weeks), mortgage approval if applicable (4-6 weeks), due diligence and legal review (3-4 weeks), CPCV (promissory contract) signing, and final escritura coordination. Expedited timelines of 75-85 days are possible with pre-cleared documentation and experienced legal representation [https://www.realestate-lisbon.com/english-speaking-lawyers].
How does the flat 7.5% IMT rate for non-residents affect acquisition costs?
For properties in the €650,000-€1,500,000 range, the flat 7.5% rate increases total acquisition costs by approximately 0.5-1.5% versus previous progressive structures. This is offset by simplified tax planning and predictable budgeting. Properties exceeding €1,150,853 face identical 7.5% rates for both residents and non-residents, eliminating differential treatment at ultra-high price points.
What gross rental yields should investors target in Lisbon?
Prime central districts (Chiado, Santo António) deliver 3.2-4.1% gross yields reflecting capital preservation focus rather than income generation. Emerging neighborhoods (Marvila, Beato) offer 4.5-5.5% yields with higher appreciation potential but increased vacancy risk. The Silver Coast and secondary cities provide 4.5-6.0% yields with lower capital appreciation but stronger cash flow profiles. Target minimum 4.0% gross yields after transaction cost adjustment for balanced portfolios. Use our ROI & Rental Yield Calculator [https://www.realestate-lisbon.com/calculators/investment-analyzer] for detailed projections.
How does the construction labor shortage impact investment strategies?
The 90,000-worker deficit makes off-plan projects riskier with frequent delays and cost overruns. Prioritize: 1) Turnkey properties requiring minimal renovation, 2) Developers with proven completion track records, 3) Projects with construction insurance and completion guarantees, 4) Existing properties over new construction in supply-constrained markets. Budget 15-25% premiums for move-in-ready properties versus renovation projects.
What are the key opportunities in the 2026 Portuguese real estate market?
High-conviction opportunities include: Regeneration hubs like Marvila in Lisbon and Campanhã in Porto offering significant upside from multi-year urban renewal projects; infrastructure corridor investments along new metro lines (Red Line extension, Ruby Line) providing predictable appreciation paths; Silver Coast value plays in coastal towns like Nazaré offering 4-6% yields below Algarve pricing; and tax-efficient rental housing leveraging 10% IRS rate for moderate rent properties providing stable lower-tax income streams. Explore off-plan opportunities in Marvila [https://www.realestate-lisbon.com/off-plan/lisbon/marvila] for strategic positioning.
What are the critical risks for investors in the 2026 Portuguese property market?
Critical risk factors include: Political and policy risk with potential for aggressive rent controls or AL licensing restrictions; construction risk with project delays and cost overruns due to labor shortages making off-plan investing riskier; affordability ceiling in prime districts where prices may have reached limits where even international demand cannot sustain rapid growth; and exit liquidity challenges with €1M+ properties averaging 120-180 days to sale creating sensitivity to global economic conditions. Review our investment risks guide [https://www.realestate-lisbon.com/buying-guide/investment-risks] for comprehensive analysis.
How has the Golden Visa program change affected the market?
The 2023-2024 removal of real estate investment options from the Golden Visa program successfully dampened speculative flipping without collapsing broader market fundamentals. The market transitioned to lifestyle-driven buyer cohorts from United States, United Kingdom, and Northern Europe. International buyers now pay 62% more than domestic buyers on average, with foreign transactions averaging €2,415/m² versus domestic €1,794/m², reflecting fundamental differences in buyer psychology and capital allocation priorities.
Which regional markets offer the best value outside Lisbon?
Porto remains highly attractive with median prices around €2,950/m², offering 40% discount compared to central Lisbon. Secondary cities like Coimbra witnessed 28.9% annual price increases reflecting growing status as residential and educational hubs. The Azores experienced 19.8% year-over-year appreciation driven by limited supply and North American lifestyle seeker demand. Madeira saw 21.4% monthly rent increases in January 2026. Coastal towns on the Silver Coast offer yields of 4-6% with prices significantly below Algarve comparables.
## Synthesis: The Perfect Inelasticity Market
The three core market signals identified—Lisbon's €6,000/m² threshold breach, 16% rental surge, and sustained foreign buyer premiums are not isolated phenomena but visible symptoms of a market reaching "perfect inelasticity." The 16% rent surge represents market attempts to adjust to massive 120% house price increases since 2015, while the €6,000/m² record confirms Lisbon's transition into Tier 1 European investment city league alongside Madrid and Paris.
Together, these data points demonstrate Portugal is no longer a "recovery" market but a "premium" one. The narrative for 2026 is a country grappling with its own success: a destination that attracted global capital and lifestyle seekers but has yet to solve fundamental housing challenges for its domestic population.
For portfolio managers allocating €650,000 to €3,000,000 in European residential assets, the Portuguese real estate market in 2026 requires sophisticated analysis, focus on "lasting value," and keen awareness of socio-political tensions that will shape the next decade of development. The days of effortless double-digit appreciation across all segments have ended, but market fundamentals [https://www.realestate-lisbon.com/market-insights] remain robust due to unyielding supply deficit, macroeconomic stability, and sustained international demand from capital preservation-focused buyers.
Strategic positioning in infrastructure corridors, regeneration hubs, and tax-efficient rental housing offers compelling risk-adjusted returns for investors with medium to long-term horizons and tolerance for regulatory evolution uncertainty.
© 2026 RealEstate-Lisbon.com. All rights reserved.
Home [https://www.realestate-lisbon.com/] | Blog [https://www.realestate-lisbon.com/blog] | Market Insights [https://www.realestate-lisbon.com/market-insights] | Tools & Calculators [https://www.realestate-lisbon.com/calculators]
ce simplified but higher acquisition costs. Professional business aesthetic with Por