Portugal Housing Inventory Falls for Seventh Consecutive Quarter: Lisbon Holds Resilient While Porto Supply Drops 21%
By Pieter Paul Castelein
Published: October 15, 2026
Category: market-trends
### Portugal Housing Inventory Falls for Seventh Consecutive Quarter: Lisbon Holds Resilient While Porto Supply Drops 21%
In a critical trend for **Portugal**'s prime residential property sector, nationwide housing inventory available for purchase contracted by **4%** year-on-year in the third quarter of 2026. Authoritative market data published by **idealista** underscores that available residential supply has now shrunk across seven consecutive quarters, establishing a prolonged period of structural scarcity that directly influences pricing dynamics and acquisition strategies for cross-border investors.
### Key Takeaways
• ✓ Portuguese residential inventory dropped 4% year-on-year in Q3 2026, marking seven unbroken quarters of supply contraction
• ✓ Lisbon municipal stock demonstrated notable resilience with only a 3% dip, while the wider Lisbon district expanded by 1%
• ✓ Porto experienced a steep 21% decline in urban listings, reflecting acute inventory shortages in the northern capital
• ✓ Sustained supply bottlenecks strengthen asset values across prime metropolitan corridors and highlight strategic opportunities in peripheral municipalities
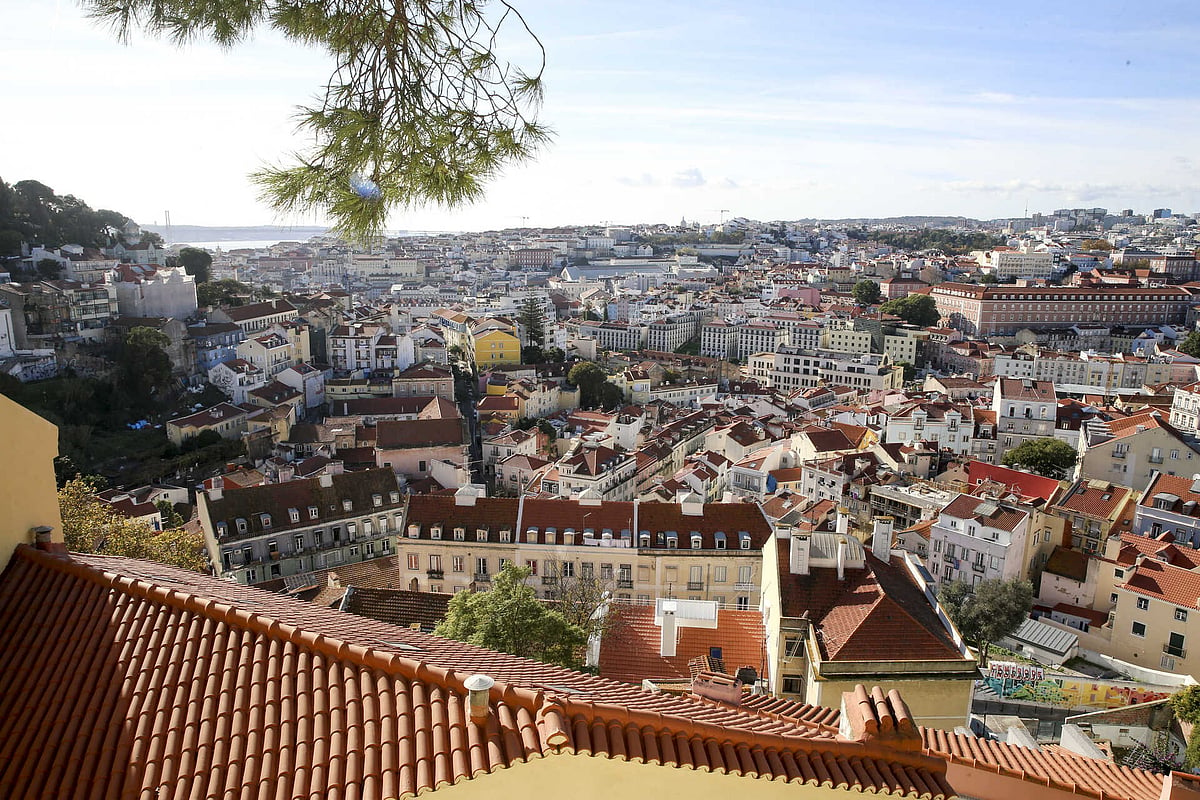
The quarterly findings highlight significant geographical divergence between Portugal's two primary economic centers. Municipal **Lisboa** demonstrated remarkable stability during the summer quarter, registering an inventory contraction of only 3%. This resilience indicates that transaction turnover in central capital neighborhoods has maintained a healthier equilibrium of listings relative to other metropolitan areas. Crucially for foreign buyers exploring the Lisbon neighborhoods guide [https://www.realestate-lisbon.com/lisbon-real-estate-neighborhoods], the broader Lisbon district managed to post a slight 1% expansion in overall stock, buoyed by new completions and secondary listings across peripheral municipalities.
By contrast, the northern capital of **Porto** faced an aggressive 21% reduction in available residential listings within its urban core, while the wider Porto district contracted by 11%. Island markets experienced even steeper declines, with **Funchal** in Madeira suffering a national high inventory drop of 33%, followed by a 23% regional plunge across the island. The Algarve's flagship district of **Faro** saw stock diminish by 9%, matching declines in Aveiro. These figures confirm that inventory depletion remains concentrated within jurisdictions that command sustained international interest and demographic influx.
Meanwhile, inland district capitals recorded counter-cyclical inventory growth, driven by lower transactional velocity rather than major building booms. Supply expanded substantially in **Vila Real** (+34%), **Guarda** (+25%), and **Bragança** (+18%). While these regional centers offer lower acquisition thresholds, international capital remains predominantly focused on coastal and metropolitan hubs where liquidity, rental demand, and capital appreciation prospects remain robust.
## Market Implications for Investors
The prolonged seven-quarter inventory contraction reinforces key fundamentals across the Portuguese housing sector, serving as an unambiguous market signal that asset values in core locations remain well-protected against broad market corrections. Investors consulting current market insights [https://www.realestate-lisbon.com/market-insights] will recognize that chronic supply shortages continue to counterbalance macroeconomic shifts, sustaining price floors across prime residential segments.
For international buyers targeting central Lisbon districts such as Chiado [https://www.realestate-lisbon.com/lisbon/chiado], Baixa [https://www.realestate-lisbon.com/lisbon/baixa], and Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real], the modest 3% inventory dip confirms that quality residential stock continues to be absorbed swiftly by lifestyle purchasers and wealth-preservation capital. The localized 1% inventory gain across the broader Lisbon district points to growing buyer dispersion toward adjoining municipalities such as Cascais [https://www.realestate-lisbon.com/cascais/real-estate-agents], Oeiras [https://www.realestate-lisbon.com/oeiras/real-estate-agents], and Sintra [https://www.realestate-lisbon.com/sintra/real-estate-agents], where infrastructure connectivity and international schools support strong family relocations.
In Porto, the severe 21% supply contraction poses acute execution challenges for purchasers, where competition for turn-key apartments in central Foz do Douro and historic quarters frequently leads to compressed negotiation windows. To safeguard acquisition metrics, a growing number of foreign buyers are cross-referencing asking prices against independent fair price indicators [https://www.homeos.pt/comprar/preco/preco-justo/] before entering negotiations, ensuring offers remain grounded in verified registry data rather than speculative asking valuations.
Furthermore, inventory depletion directly impacts the private rented sector. As residential sales listings remain restricted, prospective tenants face tighter vacancy rates, supporting yields for buy-to-let investors. Foreign capital assessing income potential should evaluate specialized investment properties agents [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties] and leverage the rental yield calculator [https://www.realestate-lisbon.com/calculators/rental-yield] to project net returns across varied micro-locations.
## Idealista Market Intelligence Context
The comprehensive market analysis conducted by **idealista** tracks listing volumes across thousands of active agency portfolios and private listings nationwide. Historical benchmarking reveals that Portugal last registered a positive replenishment of national housing stock in the third quarter of 2024, when inventory expanded by a marginal 2.5%. Since that inflection point, available listings contracted by 11% in Q3 2025 and an additional 4% in Q3 2026.
This persistent shrinkage underscores structural bottlenecks within the development supply chain. Despite progressive regulatory adjustments aimed at accelerating municipal permitting, project completion timelines remain extended, preventing new construction from matching annual absorption rates in high-demand municipal corridors.
## Portuguese Residential Supply Dynamics
Understanding the root causes of Portugal's housing shortage is essential for international stakeholders constructing medium- to long-term investment theses. The national inventory squeeze is shaped by interconnected structural and behavioral drivers:
• **New Build Delivery Lag**: Regulatory permitting cycles and contractor capacity continue to limit delivery volumes, encouraging buyers to examine vetted off-plan developments [https://www.realestate-lisbon.com/off-plan] to secure modern residential stock ahead of completion
• **Mortgage Lock-in Behavior**: Existing property owners holding low-rate fixed mortgages increasingly defer asset disposals, starving the secondary resale market of quality family homes
• **Strong International Demand**: Steady inflows of lifestyle buyers, retirees, and remote professionals continue to absorb available listings in prime coastal and metropolitan centers
• **Regional Supply Mismatch**: New listing growth is concentrated in low-demand interior districts such as Vila Real and Guarda, whereas economic engines like Lisbon and Porto face sustained deficits
For purchasers seeking to bypass secondary market shortages, examining off-plan inventory across expanding corridors such as Marvila [https://www.realestate-lisbon.com/off-plan/lisbon/marvila], Parque das Nações [https://www.realestate-lisbon.com/off-plan/lisbon/parque-das-nacoes], or South Bay alternatives in Almada [https://www.realestate-lisbon.com/off-plan/almada] represents an effective pathway to secure newly delivered units built to modern energy and seismic standards.
When assessing off-plan opportunities, investors should structure payments prudently using the dedicated off-plan payment calculator [https://www.realestate-lisbon.com/calculators/off-plan] and review development risks highlighted in the new builds risks guide [https://www.realestate-lisbon.com/buying-guide/new-builds-risks] to ensure complete alignment with project delivery milestones.
## Investment Considerations
Navigating an inventory-constrained real estate environment requires disciplined preparation and dedicated local professional representation. Foreign buyers must move away from generic online browsing toward structured sourcing models, collaborating directly with experienced English-speaking real estate agents [https://www.realestate-lisbon.com/english-speaking-agents] who maintain access to off-market portfolios and upcoming listings.
Financial structuring is equally decisive in competitive transaction settings. Modeling complete transaction overheads—including IMT, stamp duty, and registration charges—using the IMT tax calculator [https://www.realestate-lisbon.com/calculators/imt] and true cost calculator [https://www.realestate-lisbon.com/calculators/true-cost] ensures liquidity is calibrated before bidding. Consulting qualified English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants] helps international buyers optimize asset holding structures and evaluate applicable tax regimes.
Legal due diligence must never be compromised under market pressure. Engaging dedicated English-speaking real estate lawyers [https://www.realestate-lisbon.com/english-speaking-lawyers] to scrutinize property documentation, review the land registry (Certidão do Registo Predial), and structure the Promissory Contract (CPCV) safeguards capital against unlicensed additions or encumbrances, as detailed in our guide on legal issues in property acquisitions [https://www.realestate-lisbon.com/buying-guide/legal-issues].
## Looking Ahead
The outlook for Portugal's housing sector remains defined by constrained inventory and robust structural demand. While municipal master plan updates and urban regeneration projects gradually increase pipeline volume, delivery timelines will prevent an immediate surge in completed housing supply across tier-one districts.
For global investors and expats, market conditions underscore the defensive value of quality Portuguese real estate. Well-located properties in Lisbon and established peripheral hubs will continue to offer resilience against volatility, reinforced by enduring international lifestyle appeal and structural scarcity. For comprehensive advisory on navigating property acquisitions and developments across Portugal, contact realestate-lisbon.com [https://www.realestate-lisbon.com/].