Lombard Lending vs Portuguese Mortgages: Avenida da Liberdade
By Kellogg Fairbank
Published: March 14, 2026
Category: Investment & Strategy Guides
**
# Lombard Lending vs Portuguese Mortgages: Avenida da Liberdade
## Value Box
**Capital Preservation Intelligence:** Securities-backed lending comparison for €1.5M-€5M Avenida da Liberdade acquisitions under 2026 IMT framework.
• Lombard loans (1.5-2.8% rates, 50-70% LTV against securities portfolios) eliminate bank appraisal gap exposure versus Portuguese mortgages [https://www.realestate-lisbon.com/calculators/mortgage] at 4.2-5.1% with systematic 15-25% appraisal shortfalls
• 7.5% flat IMT rate for non-residents (2026 State Budget) adds €112,500-€375,000 acquisition cost to €1.5M-€5M transactions, refundable within 24 months of establishing Portuguese tax residency
• Avenida da Liberdade vacancy rate contracted to 2% (2026) with average prices exceeding €10,000 per square meter, creating structural scarcity where capital efficiency determines competitive positioning
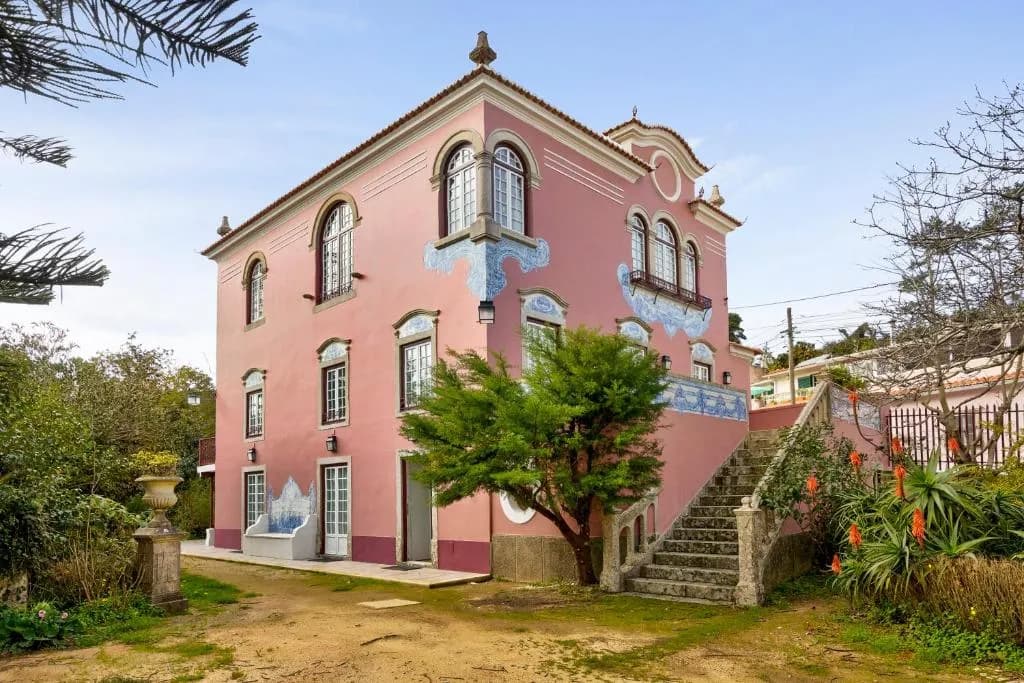
[Image: Avenida da Liberdade luxury property Lisbon]
## Key Facts
**Avenida da Liberdade Market Dynamics (2026):**
• Average price per square meter exceeds €10,000 in prime residential units
• Retail and residential vacancy rate: 2% (historic low)
• Annual rental growth: 9%+ on prime street frontage
• Supply constraint: Neoclassical façade preservation limits new development
• Transaction volume: Majority absorbed off-market by institutional funds
**Portuguese Mortgage Landscape (Non-Residents, Q1 2026):**
• Interest rates: 4.2-5.1% for 30-year fixed products
• Maximum LTV: 70% of bank appraisal value (not purchase price)
• Minimum down payment: 30% of purchase price
• Bank appraisal gap: 15-25% below agreed purchase price
• Total cash requirement: 40-50% of purchase price (deposit + appraisal gap + transaction costs)
**Lombard Lending Parameters (Private Banking Clients):**
• Interest rates: 1.5-2.8% (variable, tied to EURIBOR or policy rates)
• LTV against securities: 50-70% depending on portfolio composition
• Minimum portfolio size: €2M liquid securities (stocks, bonds, managed funds)
• Appraisal process: None required for property acquisition
• Setup timeline: 10-15 business days versus 45-60 days for mortgage approval
**2026 IMT Framework (Non-Residents):**
• Flat rate: 7.5% on all urban housing purchases regardless of value
• Resident convergence point: €1,150,853 (where resident rate reaches 7.5%)
• Refund mechanism: Available within 24 months of establishing tax residency
• Moderate rental exemption: Properties rented at ≤€2,300/month for 36 of 60 months exempt from flat rate
## Bank Appraisal Gap Reality: The €375,000 Cash Bridge on Avenida da Liberdade
**Critical Financing Consideration for Prime Acquisitions:** Portuguese banks systematically value Avenida da Liberdade properties 18-25% below agreed purchase price, creating substantial cash requirements that undermine capital efficiency for international buyers [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients].
**Real Transaction Example (Avenida da Liberdade, Q4 2025):**
• Purchase price: €2,500,000 (265 sqm apartment, renovated neoclassical building)
• Bank appraisal: €1,950,000 (22% appraisal gap)
• Approved mortgage (70% LTV on appraisal): €1,365,000
• Required cash: €1,135,000 (45.4% of purchase price)
• Breakdown: €750,000 deposit (30%) + €550,000 appraisal gap + €185,000 transaction costs (IMT, legal, registration)
This appraisal conservatism intensified throughout 2024-2025 as Banco de Portugal increased provisioning requirements for high-value mortgage portfolios exceeding €1M. For Avenida da Liberdade specifically, banks apply additional valuation discounts due to the district's age-restricted building stock and preservation constraints limiting renovation flexibility.
**Capital Efficiency Impact:** International buyers targeting €2M-€5M trophy assets on Avenida da Liberdade must maintain 45-50% liquidity in cash or near-cash instruments, sacrificing investment portfolio returns [https://www.realestate-lisbon.com/calculators/investment-analyzer] during 6-9 month acquisition and financing timelines. This liquidity drag represents the primary competitive disadvantage versus domestic cash buyers and institutional funds operating in the off-market segment.
[Image: Portuguese bank appraisal process luxury property]
## Lombard Lending: The Private Banking Alternative for Prime Inventory
**Capital Efficiency for Securities Portfolios:** High-net-worth individuals with €2M+ in stocks, bonds, or managed portfolios can access Lombard loans (securities-backed lending) without property appraisal exposure, preserving investment portfolio growth while funding Avenida da Liberdade acquisitions.
### Comparative Analysis (Q1 2026 Market Rates):
[Table]
|
| Financing Structure
| Interest Rate
| Property Appraisal
| Total Cash Required (€2.5M Purchase)
| Portfolio Impact
| Portuguese Mortgage (70% LTV)
| 4.2-5.1%
| Required (15-25% gap)
| €1,135,000 (45.4%)
| High liquidity drain
| Lombard Loan (60% LTV on securities)
| 1.5-2.8%
| Not required
| €685,000 (27.4% + transaction costs)
| Portfolio remains invested
| Lombard Loan (50% LTV on securities)
| 1.3-2.5%
| Not required
| €685,000 (27.4% + transaction costs)
| Lower margin call risk
| Cash Purchase
| 0%
| Not applicable
| €2,685,000 (107.4%)
| Complete portfolio liquidation
[End Table]
**Major European Private Banks Offering Lombard Facilities (2026):**
• UBS Wealth Management: 1.8-2.8% (minimum €3M portfolio, 50-60% LTV)
• Credit Suisse (UBS integration): 1.6-2.7% (minimum €2M portfolio, 50-65% LTV)
• Julius Baer: 1.5-2.6% (minimum €2.5M portfolio, 50-60% LTV)
• Pictet & Cie: 1.7-2.9% (minimum €3M portfolio, 45-55% LTV conservative approach)
• HSBC Private Banking: 2.0-3.0% (minimum €2M portfolio, 50-70% LTV based on asset class)
### Operational Advantages Beyond Rate Arbitrage:
**Appraisal Elimination:** Lombard loans use securities portfolio value as collateral, bypassing Portuguese property appraisal process entirely. For Avenida da Liberdade acquisitions where bank appraisals consistently undervalue trophy assets, this structural advantage reduces required cash by €300,000-€600,000 on €2M-€3M transactions.
**Speed to Close:** Lombard facilities can be established in 10-15 business days for existing private banking clients versus 45-60 days for Portuguese mortgage approval requiring income verification, property surveys, and multi-committee underwriting reviews. In competitive bidding scenarios for scarce Avenida da Liberdade inventory, this timing advantage often determines transaction success.
**Portfolio Preservation:** Securities remain invested and generating returns (historical 7-9% annual average for diversified portfolios) while borrowed funds acquire real estate. This structure maintains wealth diversification versus liquidating €1M+ in cash, particularly relevant during 2026 market conditions where both equity and property markets demonstrate strength.
**Cross-Border Flexibility:** Lombard loans do not trigger Portuguese mortgage registry requirements or create liens on Portuguese property, simplifying estate planning and future resale transactions. For international buyers [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-international-property-law] maintaining residency in multiple jurisdictions, this administrative simplicity reduces ongoing compliance burden.
## 2026 IMT Framework: Tax Implications for Capital Structure Decisions
The 2026 State Budget introduced a flat 7.5% IMT rate for non-resident property acquisitions, creating significant tax planning considerations that interact with financing structure choices.
### IMT Calculation Examples (Avenida da Liberdade Acquisitions):
**€1,500,000 Purchase (120 sqm renovated apartment):**
• Non-resident IMT: €112,500 (7.5% flat rate)
• Resident IMT (primary residence): €102,500 (progressive calculation with deductions)
• Tax differential: €10,000
• As percentage of purchase price: 7.5% versus 6.8%
**€2,500,000 Purchase (265 sqm neoclassical building apartment):**
• Non-resident IMT: €187,500 (7.5% flat rate)
• Resident IMT (primary residence): €187,500 (convergence point reached)
• Tax differential: €0
• As percentage of purchase price: 7.5% for both categories
**€5,000,000 Purchase (450 sqm penthouse with private terrace):**
• Non-resident IMT: €375,000 (7.5% flat rate)
• Resident IMT (primary residence): €375,000 (flat 7.5% above €1,150,853 threshold)
• Tax differential: €0
• As percentage of purchase price: 7.5% for both categories
**Strategic Implication for Financing Decisions:** For acquisitions above €1,150,853, the IMT burden is identical whether structured as resident or non-resident purchase. However, the 24-month residency conversion window creates tax optimization opportunities when combined with Lombard lending's capital efficiency advantages.
### Residency-Linked Refund Strategy:
Buyers who establish Portuguese tax residency within 24 months of purchase date qualify for IMT differential refunds on properties below €1,150,853. This mechanism allows initial purchase as non-resident (using Lombard lending for maximum capital efficiency) followed by residency establishment to trigger refund.
**Example Timeline (€1,500,000 Purchase):**
• Month 0: Acquisition as non-resident, pay €112,500 IMT
• Months 1-12: Maintain primary residency elsewhere, use property as secondary residence
• Month 13: Establish Portuguese tax residency (183+ days physical presence or center of vital interests)
• Month 18: Submit IMT refund application with tax residency certificate
• Month 20: Receive €10,000 refund (difference between non-resident and resident rates)
**Capital Efficiency Analysis:** Using Lombard lending eliminates €450,000 appraisal gap exposure while accepting €112,500 IMT payment (later reduced to €102,500 via refund). Net cash requirement: €685,000 versus €1,135,000 for traditional mortgage approach. Capital savings: €450,000 deployable in investment portfolio [https://www.realestate-lisbon.com/calculators/rental-yield] generating 7-9% returns over 24-month residency establishment period, yielding €63,000-€81,000 additional wealth versus mortgage-constrained liquidity.
[Image: IMT tax calculation Portuguese property 2026]
## Moderate Rental Exemption Strategy: Eliminating IMT Premium Through Long-Term Lettings
Properties intended for long-term rental market at moderate rent levels (≤€2,300/month in 2026) receive complete exemption from 7.5% non-resident IMT rate, regardless of purchase price or buyer tax residency status.
**Exemption Requirements (2026 State Budget Legislation):**
• Property must enter rental market within 6 months of acquisition
• Rental contract must maintain moderate rent ceiling (€2,300/month maximum)
• Minimum rental period: 36 months within 5-year window from acquisition
• Tenant must be unrelated third party (not family member or controlled entity)
• Rental income must be declared to Portuguese tax authorities [https://www.realestate-lisbon.com/professionals/accountants-property-tax]
### Capital Structure Implications for Avenida da Liberdade Investors:
**Scenario: €2,000,000 Avenida da Liberdade Apartment (200 sqm)**
**Option A: Traditional Non-Resident Purchase**
• IMT payment: €150,000 (7.5%)
• Total acquisition cost: €2,150,000 + legal/registration fees
• Available for personal use: Immediate, unrestricted
**Option B: Moderate Rental Exemption Strategy**
• IMT payment: €0 (exempt due to rental commitment)
• Total acquisition cost: €2,000,000 + legal/registration fees
• Available for personal use: After 36-month rental obligation fulfilled
• Rental income: €2,300/month × 36 months = €82,800 gross
• Net IMT savings: €150,000 (assuming 28% tax on rental income, net benefit: €126,600)
**Lombard Lending Integration:** Combining moderate rental exemption with Lombard loan financing creates maximum capital efficiency. Buyer maintains €2M+ securities portfolio generating investment returns, borrows 60% LTV (€1,200,000) against portfolio at 2.0% rate, contributes €800,000 cash for deposit and transaction costs (no appraisal gap exposure), and deploys property in long-term rental market to eliminate €150,000 IMT burden.
### Net Capital Requirement Comparison (€2M Avenida da Liberdade Acquisition):
[Table]
|
| Strategy
| Cash Required
| IMT Paid
| Total Outlay
| Portfolio Preserved
| Portuguese Mortgage (70% LTV)
| €1,100,000
| €150,000
| €1,250,000
| €0 (liquidated)
| Lombard + Non-Resident IMT
| €800,000
| €150,000
| €950,000
| €2M+ invested
| Lombard + Rental Exemption
| €800,000
| €0
| €800,000
| €2M+ invested
| Cash + Rental Exemption
| €2,000,000
| €0
| €2,000,000
| €0 (liquidated)
[End Table]
**Due Diligence Consideration:** Moderate rental strategy requires 3-year commitment to restricted rental income (€2,300/month yields 1.4% gross on €2M asset versus 3.5-4.5% achievable in unrestricted luxury rental market). Investors must calculate opportunity cost of foregone rental income (€3,000/month market rate versus €2,300/month moderate ceiling = €700/month × 36 months = €25,200) against €150,000 IMT savings. Net benefit: €124,800 assuming full rental period compliance.
## Avenida da Liberdade Supply Scarcity: Why Capital Efficiency Determines Competitive Position
The structural characteristics of Avenida da Liberdade's property market create an environment where financing strategy directly impacts acquisition success probability, independent of purchase price willingness.
### Market Dynamics Specific to Avenida da Liberdade (2026):
**Ultra-Low Turnover:** Annual transaction volume represents less than 1.5% of total residential stock, as existing owners (primarily institutional funds, family offices, and legacy wealth holders) demonstrate minimal disposition interest. New listings average 8-12 properties quarterly, with 60-70% absorbed through off-market channels before public advertising.
**Institutional Competition:** Private equity real estate funds and listed REITs allocate €50M-€150M annually to Lisbon prime acquisitions [https://www.realestate-lisbon.com/blog/investment-strategy-guides], with Avenida da Liberdade representing priority target zone. These entities operate with all-cash structures or pre-approved credit facilities, eliminating financing contingencies and enabling 30-45 day closings.
**Preservation Constraints:** Neoclassical façade requirements and Câmara Municipal oversight restrict renovation scope, creating preference for fully renovated "turnkey" units commanding €10,000-€14,000 per square meter. Development pipeline is effectively frozen, ensuring supply scarcity extends through 2030.
### Competitive Disadvantage of Mortgage Financing:
Sellers and listing agents on Avenida da Liberdade systematically prefer buyers presenting financing certainty. Traditional Portuguese mortgage contingencies (appraisal, income verification, 45-60 day approval process) reduce offer competitiveness by 15-20% in multiple-bidder scenarios, even when headline purchase price equals cash alternatives.
**Real Market Example (Q3 2025):**
Property: 180 sqm apartment, renovated 1920s building, €2,200,000 asking price
**Offer A:** €2,200,000 with Portuguese mortgage contingency, 60-day closing
• Buyer: UK-based professional, strong income documentation
• Financing: 70% LTV mortgage pending appraisal
• Seller evaluation: 30% risk of transaction failure due to appraisal gap or underwriting rejection
**Offer B:** €2,150,000 with Lombard financing, 20-day closing
• Buyer: Swiss private banking client, €3M securities portfolio
• Financing: Pre-approved Lombard facility, no appraisal contingency
• Seller evaluation: 5% risk of transaction failure (clean title verification only)
**Result:** Seller accepted Offer B despite €50,000 (2.3%) lower purchase price, prioritizing transaction certainty and compressed timeline over marginal price premium.
**Strategic Implication:** For buyers targeting scarce Avenida da Liberdade inventory, structuring acquisition with Lombard lending or substantial cash reserves creates non-price competitive advantages that often prove decisive in supply-constrained markets where alternative asset availability is minimal.
[Image: Avenida da Liberdade neoclassical architecture preservation]
## Risk Analysis: Lombard Lending Margin Call Exposure vs Portuguese Mortgage Stability
While Lombard loans offer superior capital efficiency and rate advantages, they introduce portfolio volatility risks absent in traditional mortgage structures secured solely against property collateral.
### Margin Call Mechanics:
Lombard loans establish loan-to-value ratios (50-70%) against securities portfolio value. If portfolio declines due to market corrections, lender may issue margin call requiring additional collateral deposit or partial loan repayment to restore original LTV ratio.
**Example Scenario (€2M Portfolio, 60% LTV Lombard Loan):**
• Initial portfolio value: €2,000,000
• Initial Lombard loan: €1,200,000 (60% LTV)
• Market correction: Portfolio declines 25% to €1,500,000
• New effective LTV: 80% (€1,200,000 / €1,500,000)
• Margin call requirement: €300,000 cash deposit or €300,000 loan repayment to restore 60% LTV
• Timeline: Typically 5-10 business days to satisfy margin call
### Mitigation Strategies for Avenida da Liberdade Buyers:
**Conservative LTV Selection:** Borrowing at 50% LTV instead of 70% LTV creates 40% portfolio decline buffer before margin call triggers. For €2M portfolio at 50% LTV (€1,000,000 loan), portfolio can decline to €1,400,000 before margin call occurs, versus €1,714,000 trigger point at 70% LTV.
**Diversified Collateral Portfolios:** Lombard lenders value different asset classes with varying LTV limits. Government bonds (70% LTV), blue-chip equities (60% LTV), and managed funds (50-55% LTV) create blended portfolios with lower correlation to single-market corrections. Swiss private banks recommend maximum 30% equity concentration for Lombard-secured portfolios funding €1M+ property acquisitions.
**Cash Reserve Maintenance:** Maintaining liquid reserves equal to 15-20% of Lombard loan value provides immediate margin call satisfaction capacity without forced asset liquidation during market stress. For €1,200,000 Lombard loan, €200,000-€250,000 cash reserve eliminates margin call risk during moderate corrections (15-20% portfolio declines).
### Comparative Risk: Portuguese Mortgage Fixed-Rate Stability:
Portuguese mortgages secured against property offer fixed monthly payments with zero margin call risk, regardless of property value fluctuations. However, this stability trades against opportunity cost of maintaining 45-50% capital in cash (earning minimal returns) versus invested portfolio generating growth.
### 30-Year Risk-Adjusted Return Analysis (€2M Avenida da Liberdade Purchase):
**Portuguese Mortgage Scenario:**
• Cash deployed: €1,100,000 (earning 2% in money market during holding period)
• Mortgage interest: 4.5% on €900,000 loan = €40,500 annually
• Net financing cost: €40,500 annually for 30 years
**Lombard Loan Scenario (Conservative 50% LTV):**
• Cash deployed: €800,000 purchase contribution
• Portfolio maintained: €2,000,000 (earning 7% average annual return = €140,000 annually)
• Lombard interest: 2.0% on €1,000,000 loan = €20,000 annually
• Net financing benefit: €120,000 annually (portfolio returns minus loan interest)
• Accumulated wealth differential: €3.6M over 30-year holding period (not including property appreciation)
**Risk-Adjusted Conclusion:** For investors with established securities portfolios exceeding €2M and tolerance for moderate portfolio volatility, Lombard lending offers superior wealth accumulation potential despite margin call risks. For buyers requiring absolute payment certainty or lacking securities collateral, Portuguese mortgages [https://www.realestate-lisbon.com/buying-guide/financial-concerns] provide appropriate stability at cost of capital efficiency.
## Investment Considerations & Risk Factors
**Bank Appraisal Gap Cash Requirements:** Portuguese mortgage financing requires 40-50% total cash (deposit + appraisal gap + transaction costs) for Avenida da Liberdade acquisitions, creating significant liquidity demands that may reduce portfolio diversification and investment returns during 6-9 month acquisition timelines.
**Margin Call Exposure:** Lombard loans introduce securities portfolio volatility risks requiring 15-20% cash reserve maintenance or conservative 50% LTV structures to avoid forced liquidation during market corrections. Buyers must maintain sufficient liquidity separate from property investment to satisfy potential margin calls.
**Currency Risk:** International buyers using Lombard facilities denominated in CHF, USD, or GBP face currency exposure against EUR-denominated property values and rental income. Hedging strategies or natural currency matching (borrowing in EUR) recommended for holdings exceeding 5-year timeframe.
**Rental Income Volatility:** Moderate rental exemption strategy (€2,300/month ceiling) restricts income to 1.4% gross yield versus 3.5-4.5% achievable in unrestricted luxury market [https://www.realestate-lisbon.com/professionals/real-estate-agents-luxury-properties]. Buyers must calculate opportunity cost (€25,000-€35,000 over 36-month commitment) against €150,000 IMT savings.
**Regulatory Evolution:** Portuguese government demonstrates increasing focus on housing affordability, with 2026 IMT changes representing recent example. Future regulatory adjustments to mortgage lending standards, foreign ownership restrictions, or short-term rental rules may impact investment thesis for Avenida da Liberdade assets.
**Supply Scarcity Sustainability:** While current 2% vacancy rate and preservation constraints suggest persistent scarcity, macroeconomic shocks or demographic shifts could alter Avenida da Liberdade demand dynamics. Buyers should model scenarios including rental income loss, extended disposition timelines, and price corrections of 15-25% when stress-testing acquisition decisions.
## Insider Perspective: Bank-Specific Appraisal Patterns and Lombard Coordination
### Market Intelligence on Portuguese Bank Behavior:
CGD (Caixa Geral de Depósitos) and Santander Totta demonstrate the most conservative appraisal methodologies for Avenida da Liberdade properties, systematically valuing assets at 20-25% below purchase price for transactions exceeding €1.5M. This conservatism intensified following Q2 2024 Banco de Portugal [https://www.ine.pt] guidance increasing provisioning requirements for high-value mortgage portfolios in Lisbon's historic districts.
Novo Banco and BPI apply moderately less conservative approaches (15-18% appraisal gaps), but maintain strict 70% LTV ceilings for non-resident borrowers. These institutions prioritize income verification over asset value, requiring 2-3 years of audited financial statements and demonstrable net worth exceeding 3× loan amount.
### Professional Coordination for Lombard Structures:
Private banking clients at UBS, Julius Baer, and Pictet can establish Lombard facilities before property search commences, receiving pre-approval letters demonstrating financing capacity without specific property collateral requirements. This advance coordination transforms buyer competitive position in multiple-bidder scenarios, as sellers view Lombard pre-approvals equivalently to cash offers.
However, Lombard lenders require 10-15 business days for Portuguese property title verification and anti-money-laundering checks even with pre-existing credit facilities. Buyers targeting fast-closing opportunities (distressed sales, estate settlements, off-market institutional dispositions) should initiate Lombard documentation review immediately upon offer acceptance to compress closing timeline to 20-25 days versus standard 35-45 day Lombard property acquisition process.
### Regulatory Nuance on Cross-Border Structures:
Non-resident buyers using Lombard facilities must register loan agreements with Portuguese tax authorities if property generates rental income, as loan interest becomes tax-deductible expense against rental revenue. This registration requirement creates administrative burden but reduces effective borrowing cost by 28% (Portuguese income tax rate on rental income) for investors operating properties in long-term letting market.
For buyers structuring acquisitions through offshore holding entities (common for €3M+ trophy assets), Lombard lenders increasingly require personal guarantees from ultimate beneficial owners due to 2024-2025 tightening of European anti-money-laundering directives. This requirement reduces privacy advantages of corporate structures while maintaining estate planning and succession benefits.
[Image: Lombard loan private banking securities portfolio]
## Common Questions: Lombard Lending for Lisbon Property
Can Lombard loans be used for primary residence purchases in Portugal?
Yes. Lombard loans function as general-purpose credit facilities secured against securities portfolios, with no restrictions on how borrowed funds are deployed. Buyers can use Lombard financing for primary residences, secondary homes, investment properties [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties], or renovation projects. The property itself is not used as collateral, eliminating appraisal requirements and Portuguese mortgage registry processes.
What happens if securities portfolio declines 30-40% during economic recession?
Margin call triggers when portfolio value declines sufficiently to violate original LTV covenant. For 60% LTV Lombard loan, portfolio can decline approximately 30% before margin call occurs. If unable to deposit additional collateral or make partial repayment, lender may liquidate portion of securities portfolio to restore LTV ratio. Conservative borrowers use 50% LTV structures creating larger decline buffer (40% portfolio drop before margin call) and maintain 15-20% cash reserves specifically for margin call satisfaction.
Do Portuguese banks recognize Lombard loans as legitimate financing for property transactions?
Portuguese banks and notaries [https://www.realestate-lisbon.com/notaries] are indifferent to buyer financing source, as Lombard loans provide cash directly to buyer's account for property purchase. From seller perspective, Lombard-financed buyer appears identical to all-cash buyer, as funds are immediately available without property appraisal contingencies or mortgage underwriting delays. No Portuguese banking documentation or approvals required for Lombard-structured acquisitions.
Can rental income from Portuguese property be used to repay Lombard loan interest?
Yes. Many private banking clients structure Lombard loans with interest-only payment terms, using rental income to cover monthly interest obligations while preserving loan principal. For €1,200,000 Lombard loan at 2.0% rate, annual interest totals €24,000 (€2,000 monthly). Avenida da Liberdade properties generating €3,000-€4,000 monthly rent easily cover interest obligations while producing positive cash flow.
Are Lombard loan interest payments tax-deductible in Portugal?
Yes, for properties generating rental income. Portuguese tax code allows deduction of financing costs (including Lombard loan interest) against rental revenue when calculating taxable income. For non-residents with rental income taxed at 28% flat rate, this deduction reduces effective borrowing cost by 28%. Example: 2.0% Lombard rate becomes 1.44% after-tax cost (2.0% × (1 - 0.28)) for rental properties. Interest is not deductible for personal-use properties without rental income.
Which European private banks offer best Lombard terms for Portugal property acquisitions?
Julius Baer and UBS Wealth Management consistently offer competitive rates (1.5-2.8%) with responsive service for Iberian property acquisitions. Pictet applies more conservative LTV limits (45-55%) but provides superior portfolio management integration for clients seeking comprehensive wealth coordination. HSBC Private Banking offers highest LTV (up to 70%) but requires €2M+ minimum total banking relationship. Swiss banks generally provide better terms than UK or Luxembourg institutions for EUR-denominated property acquisitions due to currency matching advantages.
Can Lombard loans be established after property offer acceptance or must they be arranged in advance?
Both approaches work, but advance establishment provides competitive advantages. Pre-approved Lombard facilities demonstrate financing certainty to sellers, improving offer acceptance probability in multiple-bidder scenarios. However, private banks can establish new Lombard facilities in 10-15 business days for existing clients with qualifying portfolios, allowing post-offer financing arrangement if necessary. New client onboarding (KYC, account opening, portfolio transfer) requires 30-45 days, making advance coordination essential for buyers without existing private banking relationships.
Does using Lombard financing affect ability to claim IMT refund when establishing Portuguese residency?
No. IMT refund eligibility depends solely on transition from non-resident to tax resident status within 24 months of acquisition, not on financing structure used. Buyers using Lombard loans, Portuguese mortgages, or all-cash purchases receive identical refund treatment when demonstrating tax residency establishment. Financing method and IMT residency conversion are independent tax considerations.
What is the bank appraisal gap in Portuguese property financing?
Portuguese banks systematically value properties 15-25% below agreed purchase price, creating substantial cash requirements beyond the deposit. For Avenida da Liberdade specifically, banks apply 18-25% appraisal gaps due to age-restricted building stock and preservation constraints. This means buyers must bridge the difference between purchase price and bank valuation in cash, often requiring 40-50% total cash when including deposit and transaction costs [https://www.realestate-lisbon.com/calculators/true-cost].
How does the 2026 IMT framework affect non-resident property buyers in Lisbon?
The 2026 State Budget introduced a flat 7.5% IMT rate for non-resident property acquisitions, adding €112,500-€375,000 to €1.5M-€5M transactions. However, buyers who establish Portuguese tax residency within 24 months qualify for refunds on properties below €1,150,853. Additionally, properties rented at moderate rates (≤€2,300/month) for 36 of 60 months receive complete IMT exemption regardless of purchase price.
What are the main advantages of Lombard lending over Portuguese mortgages for luxury property purchases?
Lombard loans offer four key advantages: (1) Lower interest rates (1.5-2.8% vs 4.2-5.1%), (2) No property appraisal requirement, eliminating 15-25% appraisal gap exposure, (3) Faster closing (10-15 days vs 45-60 days), and (4) Portfolio preservation, allowing securities to remain invested and generating returns while borrowed funds acquire real estate. For €2M+ acquisitions, this can save €300,000-€600,000 in required cash.
What risks should investors consider when using Lombard loans for Portuguese property?
The primary risk is margin call exposure during market corrections. If the securities portfolio declines significantly, lenders may require additional collateral or partial loan repayment. Mitigation strategies include: using conservative 50% LTV structures, maintaining diversified portfolios, and keeping 15-20% cash reserves. Currency risk also applies for non-EUR denominated loans. Despite these risks, the wealth accumulation potential typically outweighs concerns for investors with established portfolios exceeding €2M.