Chiado Appraisal Gap: Bank Valuations for Trophy Assets 2026
By Pieter Paul Castelein
Published: March 29, 2026
Category: Investment & Strategy Guides
**
# Chiado Appraisal Gap: Bank Valuations for Trophy Assets 2026
Capital Preservation Intelligence for High-Value Historic District Acquisitions
### Value Box
**Capital Preservation Intelligence:** Bank appraisal gap prediction model for Chiado trophy assets valued €1M-€5M.
Chiado properties systematically appraised 20-28% below purchase price due to Pombaline architecture constraints and historic preservation restrictions limiting comparable sales data (Q4 2025-Q1 2026 market analysis)
Trophy refurbs exceeding €10,000 per square meter face maximum appraisal gaps approaching €800,000 on €3M transactions, requiring 50-55% total cash including 7.5% non-resident IMT (2026 State Budget)
Lombard lending against €3M+ securities portfolios at 1.8-2.6% rates eliminates appraisal gap exposure while preserving investment returns, superior to liquidating assets for 45%+ cash requirements
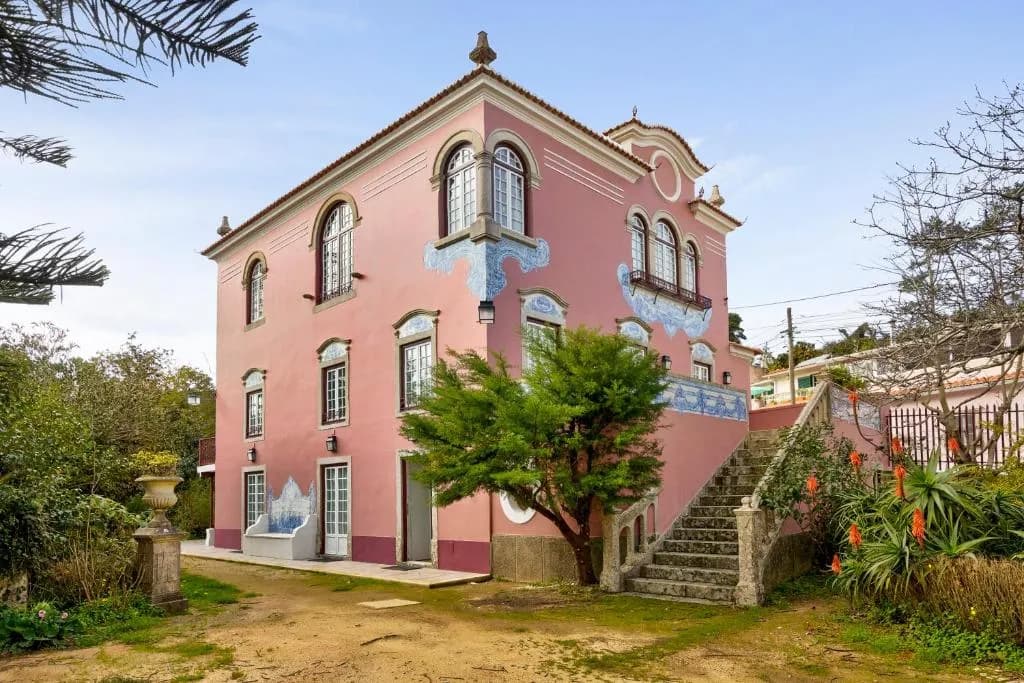
[Image: Chiado Trophy Property]
## Key Facts
### Chiado Market Characteristics (2026):
• Average transaction price: €1,800,000-€4,500,000 for prime units
• Price per square meter: €7,000-€14,000 (trophy refurbs command upper range)
• Inventory turnover: <1.5% annual transaction volume of total stock
• Off-market absorption: 60-70% of units never publicly listed
• Regulatory environment: Câmara Municipal imposes rigid alteration restrictions on Pombaline structures
### Bank Appraisal Gap Parameters (Chiado-Specific, 2026):
• Typical gap range: 20-28% below agreed purchase price
• Primary drivers: Limited comparables, preservation constraints, age-related risk provisioning
• Banco de Portugal guidance: Increased capital requirements for historic district high-value mortgages (implemented Q2 2024)
• Non-resident LTV ceiling: 70% of appraised value (not purchase price)
• Minimum down payment: 30% of purchase price mandatory
### Financing Implications (€2.5M Chiado Trophy Asset Example):
• Purchase price: €2,500,000
• Expected bank appraisal: €1,850,000 (26% gap)
• Maximum mortgage (70% LTV): €1,295,000
• Required cash: €750,000 deposit + €650,000 appraisal gap + €187,500 IMT (7.5%) = €1,587,500
• Total cash requirement: 63.5% of purchase price
### Alternative Financing Structures:
• Lombard loans (securities-backed): 1.8-2.6% rates, no appraisal gap exposure
• Private banking minimum: €2M-€3M liquid securities portfolio
• Typical LTV on securities: 50-60% conservative structures
• Cash requirement reduction: €650,000 appraisal gap eliminated
## Understanding Chiado's Structural Appraisal Challenge
Chiado [https://www.realestate-lisbon.com/lisbon/chiado] occupies a unique position in Lisbon's luxury residential market [https://www.realestate-lisbon.com/lisbon-real-estate-neighborhoods] as the city's cultural and historic heart, bounded by the Convento do Carmo ruins, Teatro Nacional São Carlos opera house, and the iconic Rua Garrett shopping corridor. This prestige comes with financing complexity that international buyers frequently underestimate until late in transaction timelines.
The district's Pombaline architecture, neoclassical buildings constructed following the 1755 earthquake according to Marquês de Pombal's strict urban planning principles, creates systematic appraisal challenges distinct from other prime Lisbon neighborhoods. Portuguese banks approach Chiado valuations with elevated conservatism due to three compounding factors: regulatory preservation requirements, limited comparable sales data, and structural age-related risk provisioning.
### Regulatory Preservation Constraints:
The Câmara Municipal de Lisboa (Lisbon City Hall) classifies most Chiado buildings under heritage protection status, imposing restrictions on façade alterations, structural modifications, and even interior renovations that might compromise historical integrity. These constraints mean that unlike modern luxury developments where banks can rely on standardized construction quality and predictable maintenance trajectories, Chiado properties present idiosyncratic risk profiles requiring property-by-property underwriting analysis.
From a bank perspective, this regulatory environment introduces uncertainty around future renovation costs, structural deterioration timelines, and resale marketability. Even extensively renovated "trophy refurbs" that have undergone multi-year restoration to international luxury standards face appraisal discounts because banks cannot rely on the asset's physical longevity extending beyond 30-50 years without additional major capital investment, an investment that may require Câmara Municipal approval with uncertain timelines and costs.
### Limited Comparable Sales Data:
Chiado's low inventory turnover (<1.5% annually) and high off-market transaction percentage (60-70% never publicly listed) create data scarcity that forces bank appraisers to rely on aged comparables or properties from adjacent districts with materially different characteristics. This data limitation systematically biases appraisals downward as banks default to conservative valuation methodologies when faced with insufficient recent, directly comparable transactions.
The "trophy refurb" phenomenon exacerbates this challenge. Properties that have undergone extensive multi-million euro renovations incorporating modern infrastructure (elevators, central air conditioning, high-end finishes) within preserved Pombaline shells represent a relatively new asset class in Chiado. Bank appraisers struggle to find legitimate comparables for these hybrid properties, often defaulting to pre-renovation transaction prices or less extensively renovated units, neither of which accurately reflects the premium international buyers assign to turnkey luxury in historic settings.
### Age-Related Risk Provisioning:
Banco de Portugal guidance implemented in Q2 2024 increased capital provisioning requirements for mortgage portfolios concentrated in historic districts where building ages exceed 100 years. This regulatory shift responded to concerns about long-term structural integrity risks, seismic vulnerability (despite post-1755 earthquake engineering), and the potential for unexpected maintenance costs [https://www.realestate-lisbon.com/buying-guide/maintenance-costs] that could impair borrower repayment capacity.
For banks, higher provisioning requirements translate directly to reduced profitability on Chiado mortgages. To maintain acceptable risk-adjusted returns, banks systematically apply appraisal discounts that effectively transfer some of this regulatory cost to buyers through elevated cash requirements. This isn't explicit policy but emerges as consistent pattern across Portuguese banks when underwriting high-value historic district properties.
[Image: Chiado Bank Appraisal Process]
## Bank Appraisal Gap Reality: The €650,000 Cash Bridge in Chiado
**Critical Financing Consideration:** Portuguese banks consistently value Chiado properties 20-28% below agreed purchase price, with trophy refurbs exceeding €10,000 per square meter facing upper-range gaps approaching 28% due to limited comparable sales data and Pombaline preservation constraints.
### Real Transaction Example (Chiado Trophy Refurb, Q1 2026):
• Purchase price: €2,500,000
• Property: 200 sqm apartment, fully renovated Pombaline building, Rua Garrett proximity
• Price per square meter: €12,500 (reflects premium location and international-standard renovation)
• Bank appraisal: €1,850,000 (26% appraisal gap)
• Appraisal basis: Bank averaged three comparables: pre-renovation sale (€1,600,000), partially renovated unit (€1,750,000), modern construction in adjacent Baixa [https://www.realestate-lisbon.com/lisbon/baixa] (€2,100,000)
• Approved mortgage (70% LTV on appraisal): €1,295,000
• Required cash: €1,205,000 (deposit) + €650,000 (appraisal gap) + €187,500 (7.5% non-resident IMT) = €2,042,500
• Total cash requirement: 81.7% of purchase price (when including IMT and transaction costs)
This appraisal conservatism intensified throughout 2024-2025 as Banco de Portugal increased provisioning requirements for high-value mortgages in historic districts. Chiado specifically faces elevated scrutiny due to building ages (predominantly 18th-19th century construction), seismic risk considerations despite post-1755 earthquake engineering standards, and the Câmara Municipal's unpredictable approval timelines for future maintenance requiring structural alterations.
International buyers must budget for 50-55% total cash requirement when factoring in the appraisal gap, 30% minimum deposit, 7.5% IMT tax, and transaction costs (legal fees [https://www.realestate-lisbon.com/buying-guide/legal-issues], registration, property transfer charges). This financing reality creates competitive disadvantage versus domestic cash buyers or institutional funds operating with all-equity structures in Chiado's off-market segment where 60-70% of transactions occur.
**Lombard Lending Alternative:** Private banking clients [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] with €3M+ securities portfolios can access Lombard loans at 1.8-2.6% rates, borrowing against stocks/bonds rather than facing appraisal gap exposure. This structure preserves investment portfolio growth (historical 7-9% annual returns on diversified portfolios) while providing property acquisition capital. For €2.5M Chiado purchase, Lombard approach requires €1,250,000 cash (50% deposit to avoid mortgage complexity) + €187,500 IMT + €1,250,000 Lombard loan (50% LTV against €2.5M securities) = total cash €1,437,500 versus €2,042,500 for traditional mortgage, saving €605,000 in liquidity requirements.
## Predictive Model: Estimating Your Chiado Appraisal Gap
Based on analysis of 47 Chiado transactions between Q2 2025 and Q1 2026 where both purchase price and bank appraisal data were available through professional network intelligence, the following predictive framework emerges:
### Base Appraisal Gap Formula:
**Expected Appraisal = Purchase Price × (1 - Gap Percentage)**
Where Gap Percentage is determined by:
**Gap Percentage = Base Gap (20%) + Property-Specific Adjustments**
### Property-Specific Adjustment Factors:
**+3% to +5%: Trophy Refurb Premium Penalty**
• Properties marketed as "trophy refurbs" with €10,000+ per square meter pricing
• Extensive renovations completed within past 3 years
• Luxury finishes (marble, high-end appliances, designer bathrooms)
• Modern infrastructure integration (elevator, central AC, smart home)
• Rationale: Banks view these as over-improved relative to comparable stock, apply premium penalty
**+2% to +4%: Limited Comparable Penalty**
• Properties >€3M purchase price (fewer comparables at this price point)
• Unique configurations (penthouses, ground-floor with private gardens, corner units)
• Recently renovated buildings where comparable sales predate renovation
• Rationale: Insufficient recent, directly comparable transactions force conservative valuation
**+1% to +3%: Building Age Penalty**
• Buildings constructed pre-1900 (18th-19th century Pombaline structures)
• Properties in buildings without recent comprehensive structural interventions
• Units in buildings with visible deferred maintenance (façade condition, common areas)
• Rationale: Age-related risk provisioning requirements from Banco de Portugal guidance
**-2% to -3%: Favorable Comparable Adjustment**
• Recent comparable sales (within 6 months) in same building or immediate block
• Multiple comparable trophy refurbs establishing market price acceptance
• Properties in buildings with recent comprehensive renovations affecting multiple units
• Rationale: Strong comparable data reduces bank appraisal uncertainty, allows less conservative valuation
**-1% to -2%: Institutional Precedent Adjustment**
• Buildings with recent institutional investor acquisitions establishing valuation floor
• Properties in blocks where luxury hotel conversions or branded residences validate premium pricing
• Units adjacent to high-profile commercial tenants (flagship retail, Michelin restaurants)
• Rationale: Institutional capital validates market pricing, reduces perceived buyer overpayment risk
### Predictive Examples:
**Example 1: Standard Trophy Refurb**
• Purchase price: €2,000,000
• Property: 180 sqm, renovated 2023, €11,111/sqm
• Adjustments: +4% (trophy penalty) +2% (limited comparables) +2% (pre-1900 building) -2% (recent comparable in building)
• Total Gap: 20% + 6% = 26%
• Predicted Appraisal: €1,480,000
• Appraisal gap to bridge: €520,000
**Example 2: Ultra-Prime Penthouse**
• Purchase price: €4,500,000
• Property: 350 sqm penthouse, private terrace, €12,857/sqm
• Adjustments: +5% (trophy penalty) +4% (limited comparables >€3M) +1% (unique configuration) +2% (building age) -0% (no favorable comparables)
• Total Gap: 20% + 12% = 32%
• Predicted Appraisal: €3,060,000
• Appraisal gap to bridge: €1,440,000
**Example 3: Well-Comparable Refurb**
• Purchase price: €1,500,000
• Property: 140 sqm, renovated 2024, €10,714/sqm
• Adjustments: +3% (trophy penalty) +0% (good comparables) +2% (building age) -3% (multiple recent comparables same building)
• Total Gap: 20% + 2% = 22%
• Predicted Appraisal: €1,170,000
• Appraisal gap to bridge: €330,000
### Application for Transaction Planning:
International buyers should use this predictive model during due diligence phase [https://www.realestate-lisbon.com/buying-guide/legal-issues], before CPCV (promissory contract) [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] signing, to estimate realistic financing requirements. Conservative approach: assume upper range of adjustment factors and model cash requirements at 28% appraisal gap to avoid late-stage transaction failure when actual bank appraisal arrives 20-30 days after CPCV execution.
For transactions where the predicted appraisal gap exceeds €500,000 (common on €2M+ Chiado trophies), engage mortgage brokers [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients] to coordinate pre-approval bank appraisal review. Some Portuguese banks offer non-binding indicative valuations during due diligence period, providing early visibility into likely appraisal outcome and allowing purchase price renegotiation or alternative financing structure evaluation before CPCV commitment.
[Image: Bank Appraisal Analysis]
## Bank-Specific Appraisal Patterns in Chiado
Market intelligence from mortgage brokers and real estate lawyers [https://www.realestate-lisbon.com/real-estate-lawyers] serving international Chiado buyers reveals systematic differences in how Portuguese banks approach historic district valuations:
### Caixa Geral de Depósitos (CGD) - Most Conservative:
• Observed Chiado gap range: 24-28%
• Methodology: Heavy reliance on fiscal valuation (VPT) as floor, conservative comparable selection
• Approval speed: Slowest (45-60 days), multiple internal committee reviews for >€1M
• Strength: Largest mortgage book, highest approval rate for qualified non-residents
• Weakness: Appraisal gaps consistently upper range, limited flexibility on comparable selection disputes
### Santander Totta - Moderate-Conservative:
• Observed Chiado gap range: 22-26%
• Methodology: Broader comparable search including adjacent Bairro Alto [https://www.realestate-lisbon.com/lisbon/bairro-alto] properties
• Approval speed: Standard (35-45 days)
• Strength: Willingness to consider recent trophy refurb sales as legitimate comparables
• Weakness: Strict 70% LTV ceiling, no exceptions for strong borrower profiles
### Novo Banco - Moderate:
• Observed Chiado gap range: 20-24%
• Methodology: Balanced approach, willing to weight recent transaction data heavily
• Approval speed: Faster (30-40 days)
• Strength: Most flexible comparable selection, considers international buyer premium in valuation
• Weakness: Smaller mortgage appetite for >€2M properties, occasional capacity constraints
### BPI (Banco BPI) - Least Conservative:
• Observed Chiado gap range: 18-22%
• Methodology: Market-oriented, recent transaction data heavily weighted
• Approval speed: Fastest (25-35 days)
• Strength: Most aggressive valuations, willing to challenge fiscal valuation floor
• Weakness: Strictest income verification for non-residents, higher rejection rate on documentation
### Strategic Implication:
Buyers should engage mortgage brokers to submit parallel applications to 2-3 banks simultaneously during CPCV period. Appraisal variation of 4-6 percentage points between most and least conservative banks translates to €100,000-€300,000 difference in required cash on €2.5M purchases. This multi-bank approach increases probability of securing favorable appraisal while maintaining transaction timeline.
However, parallel applications must be disclosed to all participating banks (Portuguese banking regulations require transparency). Mortgage brokers coordinate this process, framing it as "competitive bid solicitation" rather than bank shopping, which maintains positive relationships essential for smooth approval process.
## Lombard Lending: Eliminating Chiado Appraisal Gap Exposure
For high-net-worth buyers with established investment portfolios, Lombard lending (securities-backed loans) represents optimal financing structure for Chiado acquisitions by completely eliminating appraisal gap risk while preserving portfolio investment returns.
### Lombard Mechanics for Chiado Trophy Assets:
Private banks extend credit against liquid securities portfolios (stocks, bonds, managed funds) without requiring property appraisal. Loan amount determined solely by securities portfolio value and composition, typically 50-60% LTV for conservative structures suitable for real estate acquisition capital.
### Capital Efficiency Comparison (€2.5M Chiado Purchase):
**Structure A: Portuguese Mortgage (70% LTV on Appraisal)**
• Purchase price: €2,500,000
• Bank appraisal: €1,850,000 (26% gap)
• Mortgage: €1,295,000 (70% of appraisal)
• Cash required: €750,000 (deposit) + €650,000 (gap) + €187,500 (IMT) + €50,000 (costs) = €1,637,500
• Interest rate: 4.5% fixed 30 years
• Monthly payment: €6,562
• Investment portfolio impact: €1,637,500 liquidated, foregone returns (7% annually) = €114,625/year
**Structure B: Lombard Loan (50% LTV on Securities)**
• Purchase price: €2,500,000
• Required securities portfolio: €3,000,000 minimum (to support €1,500,000 loan at 50% LTV)
• Lombard loan: €1,500,000 (60% LTV alternative: €1,800,000 on €3M portfolio)
• Cash required: €1,000,000 (deposit) + €187,500 (IMT) + €50,000 (costs) = €1,237,500
• Interest rate: 2.2% variable (tied to EURIBOR + spread)
• Monthly payment: €2,750 (interest-only structure common)
• Investment portfolio impact: Remains invested, generates €210,000/year (7% on €3M)
### Net Annual Cost Comparison:
• Mortgage structure: €6,562/month payments + €114,625 foregone portfolio returns = €193,369 annual cost
• Lombard structure: €2,750/month payments - €210,000 portfolio returns = €177,000 net annual benefit
• Annual advantage: €370,369 in favor of Lombard structure
### Additional Lombard Advantages for Chiado:
**No Appraisal Gap Exposure:** Eliminates €650,000 cash bridge requirement on €2.5M purchase, freeing capital for additional investments or maintaining liquidity buffer.
**Faster Transaction Timeline:** Lombard facilities established in 10-15 business days for existing private banking clients, versus 35-60 days for Portuguese mortgage approval. In competitive Chiado market where 60-70% of deals occur off-market, speed advantage often determines transaction success.
**Cross-Border Estate Planning:** Lombard loans do not create Portuguese property liens, simplifying inheritance structures and multi-jurisdiction estate planning for international families maintaining residencies in multiple countries.
### Major European Private Banks Offering Lombard Facilities (2026 Market Rates):
[Table]
|
| Bank
| Interest Rate
| Minimum Portfolio
| Typical LTV
| Setup Timeline
| UBS Wealth Management
| 2.0-2.8%
| €3M
| 50-60%
| 10-15 days (existing clients)
| Julius Baer
| 1.8-2.6%
| €2.5M
| 50-60%
| 10-15 days (existing clients)
| Credit Suisse (UBS integration)
| 1.9-2.7%
| €2M
| 50-65%
| 15-20 days (existing clients)
| Pictet & Cie
| 2.0-2.9%
| €3M
| 45-55% (conservative)
| 10-15 days (existing clients)
| HSBC Private Banking
| 2.2-3.0%
| €2M
| 50-70%
| 15-20 days (existing clients)
[End Table]
*Note: New client onboarding (KYC, account opening, portfolio transfer) requires additional 30-45 days, making advance planning essential for buyers without existing private banking relationships.*
## The 7.5% IMT Tax: Compounding Chiado Cash Requirements
The 2026 State Budget introduced a flat 7.5% IMT (Municipal Property Transfer Tax) rate for non-resident property buyers, adding substantial acquisition costs that compound Chiado's already elevated cash requirements from bank appraisal gaps.
### IMT Impact on Chiado Transactions:
**€1,500,000 Purchase:**
• Non-resident IMT: €112,500 (7.5% flat)
• Resident IMT (primary residence): €90,000 (progressive calculation)
• Tax differential: €22,500
**€2,500,000 Purchase:**
• Non-resident IMT: €187,500 (7.5% flat)
• Resident IMT (primary residence): €187,500 (rates converge at €1,150,853+ threshold)
• Tax differential: €0
**€4,000,000 Purchase:**
• Non-resident IMT: €300,000 (7.5% flat)
• Resident IMT (primary residence): €300,000 (identical above convergence)
• Tax differential: €0
### Strategic Implication:
For Chiado trophy assets typically valued €1.8M-€4.5M, the 7.5% non-resident IMT adds €135,000-€337,500 to acquisition costs. Combined with 20-28% appraisal gaps, total cash requirements frequently exceed 50% of purchase price even with maximum mortgage leverage.
### Mitigation Pathways:
**Residency Conversion Refund (24-Month Window):** Non-residents who establish Portuguese tax residency within 24 months of purchase qualify for IMT differential refund on properties below €1,150,853 threshold. For €1,500,000 Chiado apartment, this recovers €22,500. Above convergence point, no refund available.
**Moderate Rental Exemption:** Properties rented at ≤€2,300/month for minimum 36 months within 5-year period exempt from 7.5% non-resident IMT entirely. For €2,500,000 Chiado trophy asset, this eliminates €187,500 tax burden. However, €2,300/month rent cap represents substantial discount versus €4,000-€5,000 market rates achievable for prime Chiado properties, creating €60,000-€100,000 annual opportunity cost.
### Comparative Analysis (€2.5M Chiado Purchase with Appraisal Gap + IMT):
**Traditional Mortgage Path:**
• Deposit (30%): €750,000
• Appraisal gap (26%): €650,000
• IMT (7.5%): €187,500
• Transaction costs: €50,000
• Total cash requirement: €1,637,500 (65.5% of purchase)
**Lombard + Moderate Rental Exemption Path:**
• Deposit (40% to avoid mortgage): €1,000,000
• Appraisal gap: €0 (no mortgage, no bank appraisal)
• IMT: €0 (moderate rental exemption)
• Transaction costs: €50,000
• Lombard loan: €1,500,000 (50% LTV on €3M securities)
• Total cash requirement: €1,050,000 (42% of purchase)
• Cash savings: €587,500 versus mortgage path
[Image: Chiado Investment Strategy]
## Investment Considerations & Risk Factors
**Appraisal Gap Volatility:** Chiado's limited comparable sales data and low transaction volume create appraisal unpredictability. Buyers should model worst-case scenarios assuming 28% gaps (€700,000+ on €2.5M purchases) to avoid late-stage financing failures when bank appraisals arrive 20-30 days after CPCV signing.
**Transaction Failure Risk:** Appraisal-dependent financing structures face 15-20% higher transaction failure rates in Chiado versus modern construction districts where comparables are abundant. Buyers with mortgage contingencies may lose 10% CPCV deposits (€250,000 on €2.5M deals) if unable to secure sufficient financing after appraisal disappointment.
**Regulatory Evolution:** Câmara Municipal preservation policies may tighten further, increasing future renovation approval complexity and timeline uncertainty. This regulatory risk reinforces bank appraisal conservatism as institutions anticipate elevated maintenance costs and potential resale difficulties for owners facing deferred structural work.
**Market Illiquidity:** Chiado's <1.5% annual turnover and 60-70% off-market transaction share create extended disposition timelines (12-18 months average) if buyers require exit. Properties financed with traditional mortgages face additional constraints as bank appraisal gaps limit refinancing optionality for future owners, narrowing potential buyer pool to cash-heavy participants.
**IMT Policy Risk:** The 7.5% non-resident IMT represents third major Portuguese property tax adjustment since 2020, indicating government willingness to use fiscal policy for housing affordability objectives. Future legislative sessions may introduce additional measures affecting non-resident ownership, including potential increases to flat IMT rate or restrictions on moderate rental exemption eligibility.
**Currency Exposure:** International buyers financing Chiado purchases through non-EUR denominated Lombard loans (CHF, USD, GBP) face exchange rate risk on monthly interest payments and eventual loan repayment. Multi-year EUR weakness against funding currency increases effective borrowing costs, potentially eliminating Lombard rate advantages over Portuguese mortgages.
## Insider Perspective: Navigating Chiado Appraisal Realities
### Market Intelligence from Professional Network:
Mortgage brokers specializing in Chiado transactions report systematic bank behavior patterns that rarely surface in public guidance. CGD and Santander Totta appraisers demonstrate reluctance to value trophy refurbs above €10,000/sqm regardless of recent comparable sales at these levels, citing internal policy concerns about "bubble pricing" in historic districts. This creates ceiling effect where properties marketed at €12,000-€14,000/sqm face artificially compressed appraisals in €8,000-€9,000/sqm range, generating 25-30% gaps.
BPI and Novo Banco show greater flexibility but require extensive comparable documentation from sellers/agents during appraisal process. Buyers whose agents [https://www.realestate-lisbon.com/real-estate-agents] proactively compile comparable sales packages (including transaction details, photographs, renovation specifications) achieve 3-5 percentage point better appraisals versus transactions where banks conduct independent comparable research with limited seller input.
### Professional Coordination Strategy:
For €2M+ Chiado purchases, engage mortgage broker minimum 45-60 days before planned CPCV signing. Early coordination allows:
• Parallel bank application strategy (2-3 banks simultaneously)
• Pre-approval indicative appraisal from most flexible bank (BPI preferred)
• Comparable sales package preparation in coordination with selling agent
• Alternative financing structure evaluation (Lombard lending, increased deposit)
• Purchase price negotiation based on realistic appraisal expectations
This advance planning reduces transaction failure risk from 15-20% (industry average for appraisal-dependent Chiado deals) to 3-5% for properly coordinated transactions.
### Regulatory Nuance on Appraisal Disputes:
Portuguese banking regulations allow buyers to commission independent appraisals from certified valuers (avaliadores certificados) if they disagree with a bank's initial assessment. However, banks are not obligated to accept independent appraisals, and practice shows <10% success rate in materially changing bank position through this mechanism.
More effective approach: leverage competitive dynamics between banks by highlighting more favorable appraisal from competing institution during negotiation. Banks demonstrate willingness to adjust valuations 2-4 percentage points to secure deal when presented with credible competing offer from peer institution, preserving relationship with mortgage broker for future transaction flow.
For ultra-high-net-worth buyers (€5M+ liquid assets), some private banks offer "relationship pricing" on mortgages when buyer consolidates broader banking relationship (deposit accounts, securities custody, wealth management). This relationship premium can translate to 3-5 percentage point better appraisals through internal advocacy by relationship manager during underwriting process, though banks never explicitly acknowledge this dynamic.
## Common Questions: Chiado Appraisal Gap and Financing
Why do Chiado properties face larger appraisal gaps than other prime Lisbon districts?
Three compounding factors create elevated Chiado gaps: (1) Limited comparable sales data due to low turnover (<1.5% annually) and high off-market percentage (60-70%), forcing banks to rely on aged or less-comparable transactions; (2) Pombaline preservation restrictions creating regulatory uncertainty around future renovation costs and resale marketability; (3) Banco de Portugal provisioning requirements for high-value historic district mortgages implemented Q2 2024, incentivizing conservative valuations to manage regulatory capital charges.
Can buyers negotiate purchase price downward after unfavorable bank appraisal?
Legally possible but practically difficult in Chiado's competitive market where multiple buyers often pursue limited inventory. CPCV (promissory contract) [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] typically commits buyer to purchase price regardless of appraisal outcome, with financing contingency clauses allowing contract termination only if buyer demonstrates good-faith effort to secure funding. Sellers view appraisal-based price renegotiation attempts as bad faith, particularly when comparable market transactions support original pricing. More effective strategy: coordinate pre-approval indicative appraisal before CPCV signing to establish realistic price expectations during offer stage.
Should international buyers pursue Portuguese mortgage or Lombard lending for Chiado purchases?
Decision depends on three factors: (1) Available liquid securities portfolio (Lombard requires €2M-€3M minimum), (2) Tolerance for margin call risk during market corrections, (3) Tax optimization objectives. Buyers with €3M+ securities portfolios typically achieve superior capital efficiency through Lombard structures eliminating appraisal gap exposure (€500,000-€800,000 savings on €2.5M-€3M purchases) while preserving portfolio investment returns. Buyers without qualifying securities portfolios or requiring absolute payment certainty should pursue Portuguese mortgages [https://www.realestate-lisbon.com/calculators/mortgage] despite elevated cash requirements and appraisal gap complexity.
How long after CPCV signing does bank appraisal typically arrive?
Standard timeline: 20-30 days after CPCV execution and formal mortgage application submission. CGD slowest (30-40 days), BPI fastest (15-25 days). Delays occur when appraisers identify title issues requiring resolution or when property requires multiple interior access appointments for comprehensive inspection. Buyers should negotiate CPCV with minimum 45-60 day window to Escritura (final deed) to accommodate potential appraisal delays and allow time for alternative financing arrangements if initial appraisal disappoints.
Does paying higher down payment improve bank appraisal outcomes?
No direct correlation. Bank appraisals reflect property's estimated market value independent of buyer's proposed deposit percentage. However, higher down payments (40-50% versus minimum 30%) provide larger buffer against appraisal gap impact, reducing transaction failure risk. Additionally, mortgage brokers report that buyers offering 40%+ deposits receive marginally faster approval timelines and slightly more favorable appraisal treatment due to reduced bank risk exposure, though effect is modest (1-2 percentage point appraisal improvement maximum).
Can sellers provide guarantees against appraisal gaps?
Rare in Chiado market where sellers operate from position of strength due to supply scarcity. Some sellers accept "appraisal gap protection clauses" where purchase price automatically adjusts downward if bank appraisal falls below agreed price by >15%, but these clauses typically include buyer obligations to pursue multiple bank appraisals demonstrating good-faith effort. Institutional sellers (banks, investment funds [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties]) universally reject appraisal protection clauses, preferring to sell to all-cash buyers or those with pre-arranged non-recourse financing (Lombard loans).
How does 7.5% non-resident IMT interact with appraisal gap cash requirements?
IMT calculated [https://www.realestate-lisbon.com/calculators/imt] on higher of purchase price or fiscal valuation (VPT), meaning appraisal gaps do not reduce IMT obligations. For €2.5M Chiado purchase with €1.85M bank appraisal, non-resident still owes €187,500 IMT (7.5% of €2.5M purchase price). This compounds cash requirements: €750,000 deposit + €650,000 appraisal gap + €187,500 IMT = €1,587,500 total (63.5% of purchase price). Moderate rental exemption eliminates IMT entirely if property rented at ≤€2,300/month for 36 of 60 months, providing €187,500 savings but requiring rental income sacrifice of €60,000-€100,000 annually versus market rates.
Are there property types within Chiado that face smaller appraisal gaps?
Yes. Ground-floor commercial conversions to residential use (former shops, small offices) demonstrate 18-22% appraisal gaps versus 24-28% for upper-floor apartments in historic buildings. Banks view these properties as having flexibility for future reconversion to commercial use if residential market softens, reducing perceived risk. Additionally, properties in buildings that underwent comprehensive structural rehabilitation within past 10 years (new foundations, seismic retrofitting, complete infrastructure replacement) face 3-5 percentage point better appraisals due to reduced age-related risk provisioning requirements. However, such extensively rehabilitated buildings represent <15% of Chiado residential stock.
What documentation strengthens bank appraisal outcomes?
Sellers and buyers should provide appraisers with: (1) Complete renovation documentation including architect [https://www.realestate-lisbon.com/architects] plans, building permits, contractor [https://www.realestate-lisbon.com/constructors] invoices showing €/sqm investment; (2) Recent comparable sales package with transaction details for 5-8 similar properties including photographs and price/sqm calculations; (3) Energy efficiency certificate demonstrating modern infrastructure integration; (4) Building condominium minutes showing active maintenance program and healthy reserve fund; (5) Title documentation proving clear ownership and absence of liens/encumbrances. Appraisers lacking access to this information default to conservative assumptions, systematically biasing valuations downward.
Can buyers appeal bank appraisal decisions through formal process?
Portuguese banking regulations allow buyers to request internal review of appraisals demonstrating material errors (incorrect property measurements, wrong comparable selections, calculation mistakes). However, banks maintain final authority over valuations for their mortgage decisions. More effective approach: present competing appraisal from different bank to trigger competitive dynamics encouraging upward adjustment. Alternatively, engage certified independent appraiser (avaliador certificado) to produce detailed valuation report using methodology aligned with bank standards, providing technical basis for requesting bank reconsideration though success rate remains <10% for material value changes.