Lisbon vs European Capitals 2026: Portfolio Allocation Analysis
By Pieter Paul Castelein
Published: March 21, 2026
Category: Comparative Market Studies
**
# Lisbon vs European Capitals 2026: Portfolio Allocation Analysis
Last Updated: February 11, 2026
## Value Box
**Capital Preservation Intelligence:** Lisbon vs European prime residential markets comparative analysis for €1M-€10M international portfolio diversification.
• Lisbon projects 4.0-5.9% price appreciation (2026) versus Paris/London <1.9% amid non-dom tax reforms and regulatory uncertainty
• Portuguese debt-to-GDP falling to 89% (2026) from 97.9% (2023) versus EU average fiscal deterioration establishes sovereign stability premium
• International buyers pay 143% premium over domestic prices in Lisbon prime districts, creating decoupled €10,000-12,500/m² tier immune to local affordability pressures
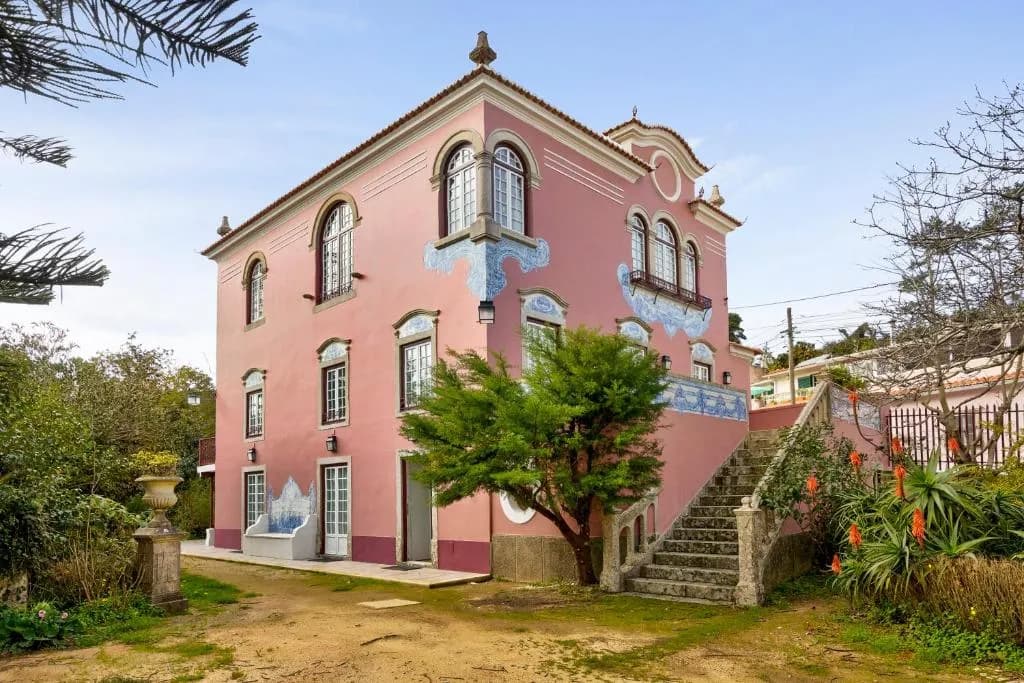
[Image: Lisbon luxury real estate cityscape]
## Key Facts
• **Lisbon 2026 Forecast:** 4.0-5.9% prime residential appreciation outpaces Madrid (4.0-5.9%), Milan (2.0-3.9%), Dublin (4.0-5.0%), and significantly exceeds Paris/London (<1.9%)
• **Sovereign Risk Profile:** Portugal debt-to-GDP declining to 89% (2026) versus eurozone average stagnation; 2.0-2.2% GDP growth forecast versus 1.6% EU average
• **Tax Arbitrage Window:** Lisbon 7.5% flat IMT for non-residents [https://www.realestate-lisbon.com/calculators/imt] (with residency exemptions) versus UK non-dom abolition and French wealth tax exposure
• **Market Decoupling Evidence:** International buyers in Lisbon €1.5M+ segment pay 143% premium, establishing separate pricing tier from domestic market constraints
• **Capital Velocity:** Lisbon €1M+ properties average 120-180 day sale cycles versus 60-90 days mid-market; Paris/London ultra-prime face extended liquidity in 2026
• **Regulatory Stability Score:** Lisbon moderate risk (rent controls) versus London high risk (non-dom reform), Paris high risk (fiscal policy), Dublin high risk (affordability backlash)
• **Safe Haven Validation:** Portugal ranks 7th Global Peace Index; US investor search volume for Portuguese residency increased 150% since 2021
• **Yield Compression Reality:** Lisbon prime gross yields 3.2-4.3% reflect capital preservation priority over income generation among HNWI buyer cohort
## European Prime Residential Market Landscape 2026
The European luxury residential sector in 2026 reflects a fundamental bifurcation between markets offering capital preservation and those navigating political uncertainty. Global prime residential indices showed moderate 0.7% growth in H1 2025, yet Lisbon's luxury segment achieved 2.4% lift, signaling Mediterranean advantage in attracting international wealth migration.
### Macroeconomic Divergence Patterns
Portuguese fiscal consolidation stands in stark contrast to broader European trends. National debt-to-GDP ratio declining from 97.9% (2023) to projected 89% (2026) demonstrates structural deleveraging absent in comparable markets. This trajectory occurs alongside 2.0-2.2% GDP growth forecast (2026), exceeding eurozone average projections by 40 basis points.
Inflationary stabilization at 2% aligns with ECB targets, providing a predictable environment for long-term asset valuations. For luxury real estate [https://www.realestate-lisbon.com/professionals/real-estate-agents-luxury-properties] specifically, this enables transition from double-digit post-pandemic appreciation to sustainable 4-6% annual growth in prime central locations.
### Comparative Sovereign Stability
[Table]
|
| Country
| 2026 Debt/GDP Forecast
| 2026 GDP Growth
| Inflation Trajectory
| Political Risk Level
| Portugal
| 89.0-90.4%
| 2.0-2.2%
| 2.0-2.1%
| Moderate-Low
| Spain
| ~95% (est.)
| 2.1% (est.)
| 2.3% (est.)
| Moderate
| France
| ~110% (est.)
| 1.1% (est.)
| 2.2% (est.)
| Moderate-High
| UK
| ~98% (est.)
| 1.3% (est.)
| 2.5% (est.)
| Moderate-High
| Ireland
| ~45%
| 3.5% (est.)
| 2.0% (est.)
| High (Affordability)
[End Table]
Portuguese fiscal discipline creates a sovereign stability premium increasingly valued by institutional investors and family offices conducting European portfolio allocation reviews.
## Price Appreciation Forecasts: The Mediterranean Advantage
The 2026 prime residential forecast matrix reveals clear winners in capital preservation strategies. Lisbon positions alongside Madrid and Stockholm as top-tier appreciation markets, while traditional wealth hubs Paris and London face structural headwinds.
[Image: European capital cities comparison chart]
### Comparative City Performance Analysis
[Table]
|
| City
| 2026 Prime Forecast
| Primary Demand Driver
| Regulatory Environment
| Safe Haven Score
| **Lisbon**
| **4.0-5.9%**
| Capital Preservation / Safety
| Moderate (Rent Controls)
| 7th Global Peace Index
| **Madrid**
| 4.0-5.9%
| American Wealth Inflow
| Low
| Comparable to Lisbon
| **Stockholm**
| ~6.0%+
| Domestic Tech Wealth
| Moderate
| High
| **Dublin**
| 4.0-5.0%
| Tech Sector Employment
| High (Affordability Backlash)
| Moderate
| **Milan**
| 2.0-3.9%
| Economic Diversification
| Moderate
| Moderate
| **Paris**
| <1.9%
| Cultural Magnetism
| High (Wealth Tax/Fiscal)
| Moderate-High
| **London**
| <1.9%
| Global Hub Status
| High (Non-Dom Abolition)
| Moderate
[End Table]
### Critical Insight: Regulatory Tax as Growth Inhibitor
Paris and London underperformance in 2026 directly correlates with policy uncertainty. UK abolition of non-domiciled tax status eliminates century-old wealth attraction mechanism, forcing international HNWIs to reassess London positioning. French wealth tax exposure and political volatility similarly constrain prime segment growth.
Conversely, Lisbon and Madrid benefit from relative regulatory stability. While Portugal's 7.5% flat IMT for non-residents represents standardization rather than punitive taxation, critical exemptions exist for those achieving tax residency [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] within two years or committing to moderate-rent market participation.
## The Lisbon Value Proposition: Quantified Competitive Advantages
### Scarcity Premium in Historic Core
Avenida da Liberdade and Chiado [https://www.realestate-lisbon.com/lisbon/chiado] districts demonstrate pricing power absent in comparable European markets. Properties regularly exceed €10,000/m² with ultra-prime penthouses reaching €12,500/m². This scarcity is structural, not cyclical.
Pombaline architecture restrictions and UNESCO heritage designations create absolute supply constraints. Unlike Paris Haussmann-era buildings where the regulatory environment permits conversion, Lisbon's historic fabric limits new development capacity. This scarcity-authenticity nexus ensures international buyer premium remains sustainable.
### International Premium Decoupling
The 143% premium international buyers [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients] pay over domestic purchasers in Lisbon's €1.5M+ segment creates a functionally separate market. This decoupling means prime assets trade as global wealth preservation instruments rather than local property, similar to London Mayfair or Paris 6th arrondissement dynamics but at 30-40% discount to those entry points.
For context: €2M Chiado duplex acquisition by international HNWI occurs in a market where a domestic equivalent buyer would pay €823,000. This gap sustains high absolute pricing despite domestic affordability constraints, as buyer pool composition shifts toward internationally sourced capital.
## Tax and Regulatory Framework Comparison
### Transaction Cost Analysis
[Table]
|
| Market
| Non-Resident Acquisition Tax
| Capital Gains Treatment
| Annual Holding Costs
| Residency Pathway
| Lisbon
| 7.5% IMT (residency exemption available)
| 28% (non-resident)
| €45,000-75,000 (€2M property)
| NHR 2.0 / D7 Visa
| Madrid
| 6-11% ITP (regional variation)
| 19-26%
| €35,000-60,000 (€2M property)
| Golden Visa via investment
| Paris
| 5.8% (incl. notary) + Wealth Tax risk
| 19-34.5% progressive
| €60,000-95,000 (€2M property)
| Complex/restrictive
| London
| 17-19% SDLT (non-resident surcharge)
| 28% + non-dom changes
| £50,000-80,000 (€2M equiv.)
| Tier 1 Investor (suspended)
| Dublin
| 1-2% stamp duty
| 33%
| €40,000-65,000 (€2M property)
| €1M investment visa
[End Table]
### Strategic Tax Arbitrage Window
Portugal's NHR 2.0 regime [https://www.realestate-lisbon.com/professionals/accountants-nhr-tax-regime] narrows eligibility to high-value professionals in innovation, science, and technical fields, imposing a 20% flat tax on employment income. While this restricts retiree influx compared to original NHR, it professionalizes the buyer pool toward younger, mobile HNWIs.
Critical advantage: Two-year residency window allows non-residents to purchase at 7.5% IMT, then achieve tax residency (183+ days annually or principal residence establishment) to qualify for progressive IMT refund. This creates an arbitrage opportunity versus immediate resident purchase requirements in competing markets.
### Moderate-Rent Commitment Alternative
Properties committed to the moderate-rent market (≤€2,300/month) for a minimum three years receive IMT exemption. For €1.5-2M properties, this represents €112,500-150,000 tax saving in exchange for guaranteed rental income stream and residency pathway qualification.
This mechanism is absent in Madrid, Paris, London frameworks, where speculative holding or short-term luxury rental represents primary non-resident strategy.
## Risk-Adjusted Return Framework
### Volatility and Liquidity Considerations
Lisbon €1M+ properties demonstrate quarterly price fluctuations of 3-7% driven by interest rate changes and international buyer sentiment. Q3 2025 experienced 4.2% adjustment in prime Cascais listings as ECB rates stabilized, indicating sensitivity to monetary policy shifts.
Exit liquidity averages 120-180 days versus 60-90 days for mid-market segments. This extended timeline reflects international buyer reliance (18-22% of transactions) and due diligence [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence] complexity for cross-border wealth preservation acquisitions.
Comparative context: London ultra-prime similarly faces extended liquidity in 2026 due to non-dom reform uncertainty. Paris benefits from domestic wealth consolidation but faces political risk premium. Madrid offers comparable liquidity to Lisbon with stronger domestic buyer support.
### Holding Cost Reality
Annual ownership expenses for €2M Lisbon property typically range €45,000-75,000, representing 2.25-3.75% of capital. Components include:
• IMI (property tax): 0.3-0.8% of fiscal value (€6,000-16,000)
• Condominium fees: €200-600/month (€2,400-7,200 annually)
• Insurance: €1,500-3,000
• Maintenance reserve: €10,000-25,000
• Utilities (if maintained): €3,000-8,000
These costs remain constant regardless of rental income or appreciation, creating negative carry for non-rented assets. However, HNWI capital preservation strategy typically accepts 2-4% annual holding cost as insurance premium against currency devaluation or geopolitical instability in primary residence jurisdictions.
## Safe Haven Thesis Validation
[Image: Portuguese coastal luxury property]
### Geopolitical Stability Metrics
Portugal's 7th position in Global Peace Index reflects absence of terrorist threat, low crime rates, and political neutrality. For HNWIs conducting global risk diversification, this "peace premium" represents non-financial ROI increasingly valued post-2020.
US-based investor surge (150% increase in Portuguese residency search volume since 2021) demonstrates strategic hedging against domestic political volatility and healthcare cost exposure. These buyers view Lisbon as a lifestyle risk diversification tool, not merely real estate investment.
### The Mobile Wealth Phenomenon
Millennials account for nearly half of future wealth relocators globally, prioritizing quality of life, political stability, and digital infrastructure over traditional financial centers. Lisbon's positioning as European tech hub (Web Summit legacy, startup visa programs) attracts this demographic in ways Paris or London cannot replicate due to cost-of-living differentials.
Critical data point: International buyers in Lisbon €1.5M+ segment are 62% self-employed or business owners versus 38% traditional employment, indicating entrepreneurial wealth migration rather than corporate relocation patterns.
## Branded Residences and Operational Real Estate Trend
### The Standardization Premium
Branded residences near Avenida da Liberdade (Karl Lagerfeld project, NAU Residences) offer quality assurance mechanisms reducing perceived foreign investment risk. These developments provide:
• BREEAM environmental certification
• Professional property management and concierge
• Artistic curation and design consistency
• Rental program infrastructure
• Exit liquidity enhancement through brand recognition
For international HNWIs unfamiliar with Portuguese construction standards or property management norms, branded residences eliminate information asymmetry. This standardization commands 15-25% premium over comparable non-branded units but reduces total cost of ownership through operational efficiency.
### Comparative Branded Supply
London and Paris feature mature branded residence markets (Four Seasons, Bulgari, Armani) with €3,000-5,000/m² brand premium. Lisbon's emerging branded sector offers early-stage entry at €1,500-2,500/m² incremental cost, representing relative value arbitrage for equivalent amenity packages.
Madrid similarly develops a branded pipeline, while Stockholm and Dublin lag in luxury lifestyle infrastructure development.
## Emerging Growth Frontiers: Tactical Alpha Opportunities
### Marvila Regeneration Case Study
While Avenida da Liberdade and Chiado represent defensive capital preservation, Marvila [https://www.realestate-lisbon.com/off-plan/lisbon/marvila] offers tactical growth exposure. 2026 prices range €3,500-5,500/m² with 6-8%+ appreciation forecast driven by:
• Tech sector expansion (proximity to Parque das Nações)
• Urban regeneration investment
• Riverfront development
• Cultural institution placement
For portfolio allocation, Marvila represents 20-30% growth sleeve balancing 70-80% core Chiado/Liberdade holdings. This barbell strategy captures stability premium while maintaining appreciation optionality.
### Comparative Regeneration Plays
Madrid's Arganzuela and Paris's 13th arrondissement offer similar regeneration exposure but at 40-60% higher entry points. Dublin Docklands completed its regeneration cycle, now priced at mature levels. Stockholm lacks comparable urban renewal opportunities due to geographic constraints.
Lisbon's regeneration arbitrage window remains open due to delayed international discovery of secondary districts, though 2026-2028 represents likely inflection as tech sector visibility increases.
## Currency and Cross-Border Considerations
### EUR Exposure Analysis
Non-EU buyers face currency risk on both acquisition and exit. 10% EUR/USD or EUR/GBP movement impacts €1M purchase by €100,000. However, diversification benefits offsets this risk for portfolios concentrated in USD or GBP assets.
2026 EUR stability (post-ECB rate normalization) provides a more predictable environment than 2022-2024 volatility. Forward hedging strategies available through Portuguese banks for acquisition financing, though typically requiring 40-50% down payment for non-residents.
### Repatriation and Exit Planning
Portugal maintains no capital controls, enabling unrestricted profit repatriation. This contrasts with certain emerging market Golden Visa jurisdictions imposing conversion restrictions or exit taxation.
Critical consideration: Tax residency establishment (183+ days annually) subjects worldwide income to Portuguese taxation but enables participation in EU/EEA tax treaty network, potentially reducing total tax burden for globally diversified HNWIs.
## Insider Perspective: Cross-Border Acquisition Dynamics
**Market Intelligence:** Chiado properties within Rua Garrett to Largo do Carmo corridor command €1,800-2,400/m² premium over equivalent specifications three blocks toward Bairro Alto [https://www.realestate-lisbon.com/lisbon/bairro-alto]. This micro-location premium widened 31% since Q1 2024 as international buyers prioritize walkability to luxury retail (Hermès, Louis Vuitton flagships) and Tagus River view corridors. Buyers accepting Calçada do Sacramento locations (250m distance) access 18-22% discount for functionally identical heritage buildings.
**Professional Coordination:** For €1M+ cross-border acquisitions, engagement sequence determines timeline efficiency. Optimal structure: (1) Secure NIF and open Portuguese bank account minimum 45 days pre-offer, (2) Engage fiscal representative [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] with cross-border experience simultaneously with lawyer selection [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition], (3) Pre-clear AIMA residency pathway eligibility if Golden Visa fund route or D7 visa intended. This coordination reduces escritura timeline from standard 120-140 days to 75-95 days, critical for currency hedging window management.
**Regulatory Nuance:** Lisbon municipal building permits approved 2024-2025 include mandatory solar panel installations and EPC "A" energy efficiency targets (2023 municipal ordinance updates). While adding €18,000-30,000 to rehabilitation budgets, these requirements improve institutional buyer ESG credentials and future-proof against EU taxonomy alignment mandates. Properties certified pre-2024 may face retrofit requirements upon resale, creating valuation discount of 8-12% versus compliant inventory.
**Comparative Advantage:** Madrid offers similar cross-border process efficiency but lacks Lisbon's English-language professional infrastructure depth. Paris and London provide superior professional ecosystems but at 2-3x service cost (legal fees €8,000-15,000 Lisbon versus €25,000-45,000 Paris/London for €2M transaction). Dublin matches Lisbon efficiency but smaller luxury inventory limits portfolio diversification within the single market.
## Investment Considerations & Risk Factors
**Market Volatility:** Lisbon luxury property (€1M+) faces quarterly price fluctuations of 3-7% driven by ECB interest rate changes and international buyer sentiment shifts. Q3 2025 saw 4.2% adjustment in prime Chiado and Cascais listings as rates stabilized. Properties priced above €3M demonstrate higher volatility (5-9% quarterly swings) due to narrower buyer pool and longer sales cycles.
**Regulatory Evolution:** Portugal's Golden Visa [https://www.realestate-lisbon.com/guides/golden-visa-alternatives-in-lisbon-a-2025-buyers-guide] (real estate pathway discontinued October 2023), NHR regime (replaced by NHR 2.0/IFICI in 2024), and Alojamento Local licensing (increasingly restricted 2023-2025) demonstrate policy dynamism. Future changes remain possible as the government balances foreign investment attraction against domestic housing affordability pressures. 2026 municipal elections may shift rental market regulation.
**Comparative Regulatory Risk:** While Lisbon rates "moderate" risk, London faces "high" classification due to non-dom abolition and potential wealth tax discussions. Paris is similarly "high risk" with wealth tax exposure and political uncertainty. Madrid offers a "low" regulatory environment but lacks Lisbon's established international buyer infrastructure. Dublin "high risk" due to affordability crisis driving potential foreign buyer restrictions.
**Exit Liquidity Constraints:** €1M+ properties average 120-180 days to sale versus 60-90 days mid-market segments. International buyer reliance (18-22% of luxury transactions) creates sensitivity to global economic conditions, currency movements, and cross-border wealth migration patterns. Properties exceeding €2.5M may require 180-270 days for buyer identification and due diligence completion.
**Currency Exposure:** Non-EU buyers face EUR/USD and EUR/GBP exchange rate risk throughout the holding period. 10% currency move impacts €2M acquisition by €200,000 on exit. While diversification benefits exist for USD/GBP-heavy portfolios, hedging strategies increase transaction complexity and cost (typically 1.5-2.5% of transaction value for 2-year forward contracts).
**Holding Cost Reality:** Annual expenses (IMI, condominium, insurance, maintenance) represent 2.25-3.75% of capital for €2M properties (€45,000-75,000 annually). These costs remain regardless of rental income or appreciation, creating negative carry for non-rented assets. Rental yield compression (3.2-4.3% gross) means holding costs often exceed rental income after vacancy, management fees, and maintenance.
## Privacy & Transaction Security
All client consultations and transactions maintain strict confidentiality protocols:
**Discretion Standards:**
• Off-market property access via private network (no public listing exposure prior to client interest)
• Encrypted communication channels (Signal, Telegram, PGP email) for all financial documentation
• NDA-protected seller negotiations and due diligence processes with vetted legal partners only
• Secure title verification through Conservatória do Registo Predial with lawyer-mediated access
• No client information shared with third parties without explicit written consent
• Anonymous viewing arrangements for ultra-high-profile individuals
**Cross-Border Security:** Portuguese banking privacy regulations comply with EU GDPR standards while maintaining stronger confidentiality protections than certain EU jurisdictions. Beneficial ownership registration requirements (2020 EU directive) apply but include privacy safeguards for legitimate commercial structures.
**GDPR Compliance:** All data handling follows Portuguese DPO-certified protocols with EU data residency guarantees. Client files stored on EU-based encrypted servers with annual third-party security audits.
## Strategic Portfolio Allocation Framework
### Core-Satellite Strategy for European Exposure
Optimal HNWI positioning combines defensive Lisbon core holdings with tactical European satellite positions:
**Core Allocation (60-70%):** Lisbon Chiado/Avenida da Liberdade [https://www.realestate-lisbon.com/lisbon/lapa] €1.5-3M properties providing capital preservation, safe haven exposure, and moderate appreciation (4-6% annually)
**Satellite Growth (20-30%):** Lisbon Marvila or Madrid emerging districts offering higher appreciation potential (6-8%+) with increased volatility
**Satellite Diversification (10-20%):** Stockholm or Milan for Nordic/Southern European geographic diversification and alternative regulatory exposure
This framework balances stability (Portuguese fiscal consolidation, safe haven status) with growth optionality and currency diversification.
### Time Horizon Considerations
**3-5 Year Hold:** Focus on branded residences with strong rental infrastructure and professional management to minimize operational burden during medium-term holding
**5-10 Year Hold:** Prioritize historic core Chiado/Lapa properties where scarcity premium compounds and international buyer base deepens
**10+ Year Legacy:** Consider off-plan ultra-prime developments [https://www.realestate-lisbon.com/off-plan] (€3M+) where architectural significance and location scarcity create generational wealth preservation assets
## Practical Implementation: The 90-Day Acquisition Timeline
For international buyers conducting comparative European market analysis, Lisbon offers streamlined acquisition process:
**Days 1-30:**
• Engage Portuguese lawyer [https://www.realestate-lisbon.com/english-speaking-lawyers] and fiscal representative with cross-border experience
• Obtain NIF (tax identification number) and open Portuguese bank account
• Conduct preliminary property viewings (typically 8-12 properties per visit)
• Review AIMA residency pathway eligibility if relevant
**Days 31-60:**
• Submit formal offer with 10% deposit to escrow
• Conduct technical due diligence (structural survey, energy certificate verification, title search)
• Finalize financing arrangements (if leveraged acquisition; non-residents typically 40-50% down payment)
• Draft promissory contract (CPCV) with lawyer review
**Days 61-90:**
• Complete escritura (title deed signing) at notary [https://www.realestate-lisbon.com/notaries]
• Register property at Conservatória do Registo Predial
• Establish utilities, condominium registration, insurance
• Engage property management if non-resident ownership
This 90-day timeline assumes no complications and international buyer pre-preparation (NIF, banking). Extended timelines (120-150 days) occur when buyers initiate process without advance coordination.
## Conclusion: Lisbon's Sustainable Competitive Advantage
The 2026 European prime residential landscape reveals clear bifurcation between markets offering capital preservation stability (Lisbon, Madrid, Stockholm) and those navigating political uncertainty (Paris, London). Lisbon's combination of fiscal consolidation, safe haven status, and structural supply scarcity in its historic core establishes sustainable competitive advantage for HNWI portfolio allocation.
Critical differentiation factors include: 143% international buyer premium creating decoupled pricing tier, 7th Global Peace Index ranking validating safe haven thesis, declining debt-to-GDP trajectory (89% by 2026), and regulatory environment offering residency pathways without punitive taxation.
For €1M-€10M international capital preservation strategies, Lisbon represents optimal risk-adjusted positioning within the European residential asset class. The market has successfully transitioned from Golden Visa-dependent speculation to fundamental value proposition based on quality of life, political stability, and structural scarcity.
The forward outlook remains positive with a 4.0-5.9% appreciation forecast (2026) supported by international wealth migration patterns, limited inventory expansion in historic districts, and professionalization of the buyer pool toward younger, mobile HNWIs seeking lifestyle risk diversification.
## Common Mistakes: Cross-Border Acquisition Pitfalls
**Underestimating Total Acquisition Timeline:** International buyers frequently assume 60-day close possible; realistic timeline requires 90-120 days minimum with proper advance preparation (NIF, banking, legal engagement). Rushed transactions increase legal risk and reduce negotiation leverage.
**Neglecting Currency Hedging Strategy:** Failure to address EUR exposure on €1M+ transactions creates unmanaged €100,000+ risk per 10% currency movement. Forward contracts or structured hedging should be arranged during the offer stage, not post-acceptance.
**Ignoring Holding Cost Impact on Returns:** €2M property with €60,000 annual expenses and 3.5% rental yield produces negative carry pre-appreciation. Many buyers underestimate condominium fees (€300-600/month luxury buildings), IMI (0.3-0.8%), and maintenance reserves, assuming rental income covers ownership costs.
**Misunderstanding NHR 2.0 Eligibility:** Assuming automatic qualification for 20% flat tax without verifying eligible professional categories (innovation, R&D, specific technical fields). Many retirees or passive investors discover ineligibility post-purchase, facing standard progressive taxation up to 48%.
**Selecting Properties Based on Tourist Familiarity:** Buyers focusing on Baixa [https://www.realestate-lisbon.com/lisbon/baixa] or Alfama [https://www.realestate-lisbon.com/lisbon/alfama] due to tourist exposure miss higher-value Lapa, Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real], or Avenidas Novas [https://www.realestate-lisbon.com/off-plan/lisbon/avenidas-novas] opportunities offering superior resident experience and appreciation potential. Tourist districts often command premium without commensurate investment merit.
**Inadequate Due Diligence on Energy Certificates:** Pre-2024 properties lacking EPC "A" or "B" ratings face retrofit requirements upon resale (2023 municipal ordinances), creating 8-12% valuation discount. Buyers should verify compliance or budget €18,000-30,000 upgrade costs.
**Over-Reliance on Short-Term Rental Projections:** Alojamento Local licensing restrictions (increasingly limited new licenses 2023-2025) make short-term rental assumptions risky. Properties should be evaluated on long-term rental yield or capital appreciation, not Airbnb income projections.
**Failing to Coordinate Service Providers:** Engaging lawyer, fiscal representative, and property manager sequentially rather than simultaneously extends timeline 30-45 days and increases coordination risk. Optimal structure requires parallel engagement with clear communication protocols.
## Frequently Asked Questions
How does Lisbon's 4-6% appreciation forecast compare to traditional wealth preservation assets in 2026?
Lisbon prime residential (4.0-5.9% forecast) exceeds European sovereign bonds (2-3% yields), matches diversified equity indices (5-7% historical), and outperforms Paris/London luxury property (<1.9%). For wealth preservation, Lisbon offers superior risk-adjusted returns versus fixed income with tangible asset backing and safe haven diversification benefits. Gold (traditional preservation asset) provides zero yield; Lisbon generates potential rental income (3.2-4.3% gross yield) plus appreciation.
What specific tax residency requirements qualify non-residents for IMT exemption or refund?
Portuguese tax residency requires either (1) 183+ days physical presence in Portugal during tax year, or (2) establishment of principal residence in Portugal (habitual dwelling test) with Portuguese-sourced income or family ties. Non-residents purchasing at 7.5% IMT can achieve residency within two years to claim progressive IMT refund. Alternative: Commit property to moderate-rent market (≤€2,300/month) for minimum three years to receive IMT exemption regardless of residency status.
How does the 143% international buyer premium in Lisbon sustain without domestic market support?
Premium sustainability derives from market decoupling: €1.5M+ segment functions as a global asset class (similar to London Mayfair) where international buyers (35% of transactions) compare Lisbon to Paris, London, Geneva rather than Portuguese domestic market. Structural scarcity in Chiado/Avenida da Liberdade (UNESCO restrictions, Pombaline architecture limits) prevents supply response to price signals. International HNWIs prioritize safe haven characteristics, quality of life, and capital preservation over yield optimization, accepting premium pricing for limited inventory.
What currency hedging strategies work best for €2M+ cross-border acquisitions in the current environment?
Forward contracts (12-24 month terms) lock exchange rates at 1.5-2.5% of transaction value, suitable for buyers with defined purchase timeline. Structured options (collars, knock-in forwards) provide downside protection while maintaining upside participation at 2-4% cost. Portuguese banks offer EUR-denominated mortgages (40-50% LTV for non-residents) effectively hedging 40-50% of currency exposure. Optimal strategy: Forward contract for down payment, mortgage for balance, creating blended hedge with manageable costs.
How do Lisbon holding costs compare to other European capitals on percentage basis?
Lisbon €2M property: 2.25-3.75% annual (€45,000-75,000) including IMI, condominium, insurance, maintenance. Comparable markets: Paris 3.0-4.75% (higher condominium fees, wealth tax risk), London 2.5-4.0% (council tax, service charges), Madrid 1.75-3.0% (lower IBI rates), Stockholm 2.0-3.5%. Lisbon sits mid-range but offers a superior appreciation forecast (4-6%) versus Paris/London (<2%), improving net return profile. Critical factor: Rental yield compression (3.2-4.3%) means holding costs often exceed rental income, requiring acceptance of negative carry for capital preservation strategy.
What constitutes moderate rent qualification for IMT exemption and does it make financial sense?
Moderate rent defined as monthly rent ≤€2,300 (subject to municipal updates) for minimum three-year commitment. For €1.5M property (typical €5,000/month market rent), this represents 54% below-market pricing. However, €112,500 IMT saving (7.5% of €1.5M) plus guaranteed tenant and residency pathway qualification often justifies discount. Financial break-even calculation: €2,300 monthly (€27,600 annually) versus market €5,000 (€60,000 annually) creates €32,400 annual opportunity cost; IMT savings recovered in 3.5 years. Optimal for buyers prioritizing residency pathway over maximized rental income.
Is Lisbon liquidity risk (120-180 day sales cycle for €1M+) acceptable for portfolio diversification?
Extended liquidity represents trade-off for capital preservation benefits and appreciation potential. Comparable ultra-prime markets (London Mayfair, Paris 6th, Geneva) demonstrate similar 90-180 day cycles for €1M+ properties. Key mitigation: Maintain €1M+ Lisbon allocation at 15-25% of total real estate portfolio, ensuring sufficient liquid assets (equities, bonds, cash) for unexpected liquidity needs. Lisbon's advantage: No capital controls enable unrestricted repatriation once sale completes, unlike certain emerging market jurisdictions with conversion restrictions.
How does Marvila regeneration opportunity compare to similar European emerging districts?
Marvila (€3,500-5,500/m², 6-8% appreciation forecast) offers a comparable entry point to Madrid Arganzuela (€4,200-6,200/m²) but 35% below Paris 13th arrondissement (€5,500-7,500/m²). Risk-adjusted advantage: Lisbon overall market stability (fiscal consolidation, safe haven status) provides downside protection while Marvila captures tech sector expansion upside. Optimal allocation: 20-30% portfolio satellite position balancing 70-80% core Chiado/Lapa holdings. Dublin Docklands completed regeneration cycle (now €6,500-9,000/m²), demonstrating maturation trajectory but higher current entry cost.
Why are Paris and London underperforming Lisbon in 2026 prime residential forecasts?
Paris and London underperformance (<1.9% forecast) directly correlates with policy uncertainty. UK abolition of non-domiciled tax status eliminates century-old wealth attraction mechanism, forcing international HNWIs to reassess London positioning. French wealth tax exposure and political volatility similarly constrain prime segment growth. Lisbon benefits from relative regulatory stability with 7.5% flat IMT for non-residents (with residency exemptions) and declining debt-to-GDP ratio (89% by 2026), establishing sovereign stability premium.
What makes Chiado and Avenida da Liberdade premium sustainable long-term?
Scarcity is structural, not cyclical. Pombaline architecture restrictions and UNESCO heritage designations create absolute supply constraints. Unlike Paris Haussmann-era buildings where regulatory environment permits conversion, Lisbon's historic fabric limits new development capacity. This scarcity-authenticity nexus ensures international buyer premium remains sustainable. Properties regularly exceed €10,000/m² with ultra-prime penthouses reaching €12,500/m², driven by international buyers paying 143% premium over domestic purchasers.
How does Portugal's fiscal consolidation affect real estate investment outlook?
Portuguese debt-to-GDP declining from 97.9% (2023) to projected 89% (2026) demonstrates structural deleveraging absent in comparable markets. This trajectory occurs alongside 2.0-2.2% GDP growth forecast (2026), exceeding eurozone average by 40 basis points. Fiscal discipline creates sovereign stability premium increasingly valued by institutional investors and family offices conducting European portfolio allocation reviews. Inflationary stabilization at 2% provides predictable environment for long-term asset valuations.
What professional coordination reduces cross-border acquisition timelines?
Optimal structure: (1) Secure NIF and open Portuguese bank account minimum 45 days pre-offer, (2) Engage fiscal representative with cross-border experience simultaneously with lawyer selection, (3) Pre-clear AIMA residency pathway eligibility if Golden Visa fund route or D7 visa intended. This coordination reduces escritura timeline from standard 120-140 days to 75-95 days, critical for currency hedging window management. Sequential rather than parallel engagement extends timeline 30-45 days unnecessarily.