Lisbon's Express Rentals: The Market Moving at Lightning Speed
By Mihail Talev
Published: July 31, 2025
Category: Real Estate Market Insights
**
# Lisbon's Express Rentals: The Market Moving at Lightning Speed
Updated: February 2026
[Image: Aerial view of Avenida da Liberdade, Lisbon — ultra-prime real estate corridor for international family offices and HNWIs in 2026]
### Capital Preservation Intelligence
Lisbon 2026 market analysis for €1M–€10M international capital allocators, Family Offices, and transatlantic wealth migration.
• NHR 2.0 (IFICI) provides a 20% flat income tax rate for 10 years; eligibility requires Portuguese-registered company activity under qualifying CAE codes effective January 2024
• Ultra-prime properties (€4M+) on Avenida da Liberdade transact 60–70% off-market via SPV share deals, avoiding IMT and Stamp Duty costs that otherwise exceed 7–8% of purchase price
• Lisbon prime office and residential yields at 4.75% (2025/2026) maintain a 75–100 basis point spread over Paris (4.00%) and London West End (3.75%), per historical transaction data
### Key Facts
Golden Visa fund entry requires €500,000 minimum in CMVM-regulated venture capital funds as of October 2023 law
Lapa palace shells acquired at €4,000–€6,000/sqm trade finished at €12,000–€16,000/sqm after museum-quality restoration
Prime Lisbon rentals in Chiado and Príncipe Real are let within 10–25 days in 2026, with sight-unseen offers standard
Branded residences command a 20–30% premium over comparable non-branded luxury stock
The 2026 rent adjustment coefficient is capped at 2.24% for continuing contracts under Portuguese law
UK non-domiciled wealth faces 40% IHT on global assets; Portugal levies zero inheritance tax for direct family on territorial assets
## The Post-Golden Visa Landscape: From Property to Structured Capital
The legislative termination of the residential real estate route for the Golden Visa (ARI) in October 2023 reshuffled the capital formation logic of the Lisbon market. By 2026, the adjustment is complete. The Golden Visa is no longer a property transaction, it is a private equity allocation strategy.
### Regulatory Context
CMVM-regulated investment funds now serve as the primary vehicle for immigration-linked capital. The dominant structure, exemplified by the Mercan Group and comparable institutional platforms, positions the investor as a mezzanine lender rather than a direct equity risk-taker. Capital is deployed into funds financing the operating companies (OpCos) of hospitality developments or logistics parks, qualifying under the 2023 law's “capitalization of commercial entities” provision without conveying direct residential property rights.
### Market Intelligence
The fund landscape has bifurcated into two distinct risk profiles. “Capital Preservation” funds offer a fixed yield of approximately 2–3% net plus a buyback agreement at maturity (typically 6–7 years, engineered to coincide with the citizenship eligibility timeline). These treat the investment as a residency bond with a modest coupon. “Industrial & Innovation” funds targeting renewable energy infrastructure, hydrogen, or IT seek 10–15% IRR without buyback guarantees, appealing to investors who treat residency as a secondary benefit.
### Investment Consideration
For US investors, fund selection requires PFIC (Passive Foreign Investment Company) due diligence. Funds that provide a PFIC Annual Information Statement enable a Qualified Electing Fund (QEF) election, generating a tax treatment analogous to a US partnership and avoiding the punitive excess distribution regime. “American-friendly” fund managers explicitly market this reporting capability as a differentiator. Fund selection criteria in 2026 should center on the manager's track record of exits, underlying asset quality, and PFIC reporting compliance [https://www.realestate-lisbon.com/professionals/accountants-golden-visa-accounting] rather than return projections alone.
[Image: NHR 2.0 IFICI tax planning and wealth structuring for high-net-worth international investors relocating to Lisbon in 2026]
## NHR 2.0 and the Transatlantic Wealth Corridor
The replacement of the classic Non-Habitual Resident (NHR) regime with IFICI, the Incentivo Fiscal à Investigação Científica e Inovação, was misread by many advisors as Portugal's fiscal retreat. The 2025/2026 reality is more nuanced: NHR 2.0 is less democratic but structurally more powerful for correctly positioned HNWIs.
### What Does NHR 2.0 Actually Provide in 2026?
IFICI offers a 20% flat income tax rate on qualifying professional income for 10 years and maintains exemptions on foreign passive income. Eligibility is now tied to high value-added activities, requiring a shift from passive retirement planning to active investment management positioning. For a full comparison of the old and new regimes, our NHR vs IFICI tax guide [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers] provides an in-depth breakdown for international buyers.
### Due Diligence
The “Board Member” strategy has emerged as the standard implementation. The HNWI incorporates a Portuguese proprietary company (Lda) operating under qualifying CAE codes, CAE 620 for IT consulting or CAE 702 for management consulting are most commonly applied. The individual serves as Director/Manager, drawing a salary taxed at the 20% flat rate. This structure may also enable access to Portugal's participation exemption on dividends from properly structured foreign holdings in white-listed jurisdictions. The Portuguese entity must demonstrate operational substance, a registered office, local accountant, and documented activity, to withstand Autoridade Tributária (AT) scrutiny. Working with NHR tax regime specialists [https://www.realestate-lisbon.com/professionals/accountants-nhr-tax-regime] is essential for structuring this correctly.
### The US Expat Tax Architecture
Key Insight: United States citizens face a structural conflict between Common Law trust instruments and Portugal's Civil Law framework, which does not recognize trusts as fiscally transparent entities. Portuguese tax authorities have historically characterized distributions from foreign trusts as generic capital distributions subject to 28% flat tax; in cases where the trust is deemed opaque and domiciled in a low-tax jurisdiction, rates exceeding 35% can apply.
The emerging 2026 standard is the “Double-Blocker” approach: holding assets in a US LLC (disregarded for US tax purposes, opaque for Portuguese purposes) or wrapping assets in Unit-Linked Insurance Policies (ULIPs). ULIPs are recognized by Portuguese law and reduce applicable tax on gains to 11.2% after an 8-year holding period, effectively replicating trust-like tax deferral within a locally compliant structure. Coordinating with expatriate tax services [https://www.realestate-lisbon.com/professionals/accountants-expatriate-tax-services] that handle both US and Portuguese obligations is critical for implementing this structure correctly.
### The UK Capital Flight: Inheritance Tax Arbitrage
With the UK government dismantling the non-domiciled regime, Lisbon is absorbing a targeted class of British wealth. The inheritance tax differential is structural and compounding. The UK imposes 40% IHT on global assets for domiciled residents. Portugal levies zero inheritance tax for direct family (spouses, children, parents) and only a 10% Stamp Duty for others, strictly on Portuguese territorial assets.
Market Intelligence: For a London-based Family Office, establishing the principal's Portuguese tax residence under NHR 2.0, while maintaining an offshore family trust excluded from Portuguese taxation under the regime's foreign passive income rules, can effectively neutralize the global IHT exposure that the UK now threatens to impose. This jurisdictional arbitrage is a primary driver of demand in the €3M–€8M Lisbon residential market among British HNWIs. The financial concerns section [https://www.realestate-lisbon.com/buying-guide/financial-concerns] of our buying guide covers cross-border capital structuring considerations in depth.
## The Underground Real Estate Market: Off-Market and Ultra-Prime
The inventory visible on Idealista or Imovirtual represents the secondary market. The primary luxury market in 2026, properties above €3 million in Avenida da Liberdade, Príncipe Real [https://www.realestate-lisbon.com/lisbon/principe-real], and Lapa, operates almost exclusively through private lists and pocket listings managed by boutique brokerages and family office intermediaries.
### Avenida da Liberdade: The Private List Economy
Avenida da Liberdade functions as Lisbon's equivalent of Avenue Montaigne or Bond Street in terms of value preservation logic. Supply is inelastic, constrained by the finite number of Pombaline buildings suitable for residential conversion.
Market Intelligence: Industry estimates indicate 60–70% of transactions above €4 million on the Avenida occur off-market in 2026. Sellers, predominantly established Portuguese families and early-cycle developers, require privacy to prevent public price discovery and avoid market burnout stigma. The “share deal” structure dominates these transactions: the buyer acquires the Single Purpose Vehicle (SPV) that holds the property, potentially mitigating IMT and Stamp Duty costs that combined can exceed 7–8% of purchase price. SPV acquisitions require forensic legal and financial due diligence on the entity's transactional history, further restricting this market to institutional or sophisticated Family Office buyers. Our due diligence legal specialists [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence] are experienced in forensic SPV review at this level.
The target asset in this market is the “Lateral Penthouse”, two or more aggregated apartments creating expansive single-floor plates exceeding 300 sqm. These command a 30–40% premium per square meter over lower-floor comparables, reflecting their extreme scarcity within Lisbon's narrow historic building footprints.
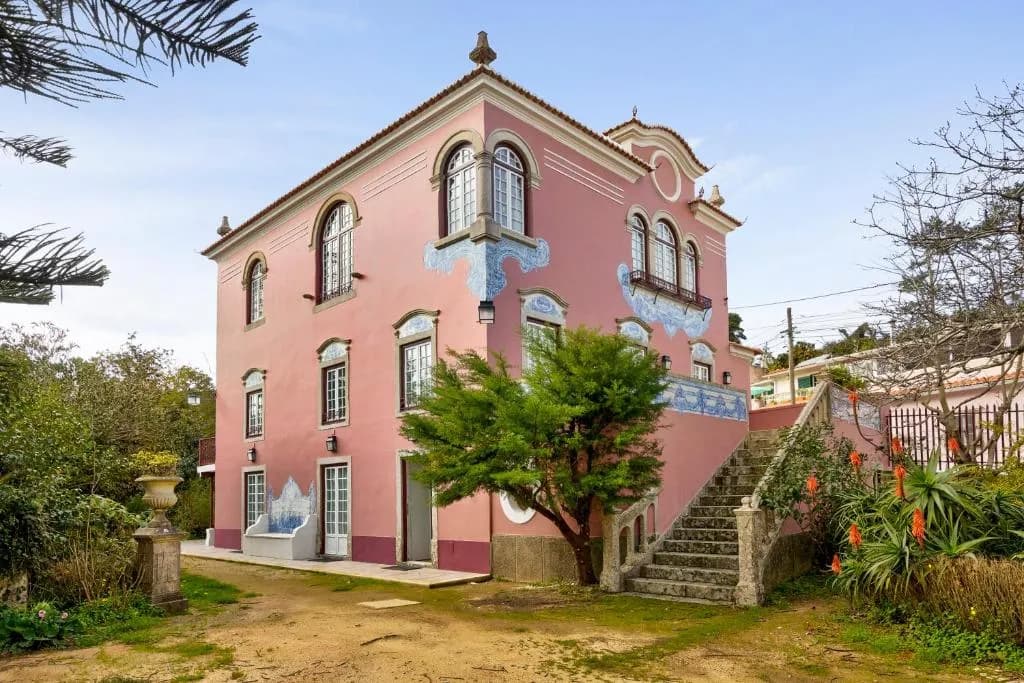
[Image: Unrenovated 18th-century palace shell in Lapa, Lisbon — acquisition entry at 4,000 to 6,000 euros per sqm for heritage architectural arbitrage]
### Lapa: The Palace Shell and Architectural Arbitrage
The most structurally distinctive trend in Lisbon's 2026 ultra-prime market is robust demand for unrenovated palace shells in Lapa [https://www.realestate-lisbon.com/lisbon/lapa] and Estrela. This is the domain of investors creating bespoke trophy assets rather than purchasing developer-standardized finishes.
Investment Consideration: The arithmetic of the “palace shell trade”: acquisition costs of €4,000–€6,000/sqm for structurally sound but internally decayed 18th and 19th-century aristocratic mansions. Museum-quality restoration using architects of the caliber of Souto de Moura or Aires Mateus runs €2,500–€3,500/sqm. Completed architecturally significant palaces in Lapa transact at €12,000–€16,000/sqm. The spread is generated by navigating the multi-year licensing process with the Câmara Municipal de Lisboa and the DGPC (Directorate-General for Cultural Heritage). Engaging historic restoration specialists [https://www.realestate-lisbon.com/professionals/constructors-historic-restoration] with documented DGPC approval history is essential to managing this process.
Supply is inelastic by legal design. Heritage protections prevent new builds and prohibit significant facade modifications, rendering Lapa palace ownership a sovereign-grade asset class exhibiting low correlation with broader market cycles.
## Institutional Strategy: Family Offices and the Multi-Unit Block
Where individual HNWIs focus on units, Family Offices are aggregating buildings. The defining trend for 2026 is whole-block acquisition in Baixa [https://www.realestate-lisbon.com/lisbon/baixa], Chiado [https://www.realestate-lisbon.com/lisbon/chiado], and emerging zones including Arroios, structured for Private Rented Sector (PRS) long-term hold strategies.
Investment Consideration: Lisbon prime yields of 4.75% compare favorably against the compressed benchmarks of Paris (4.00%) and London West End (3.75%). This 75–100 basis point spread draws institutional capital explicitly seeking “yield with safety.” Family offices including Lusoproa and Vertix are actively repositioning mixed-use buildings, retail ground floors combined with residential or office upper floors, converting B-grade stock or hostels into boutique branded residences or luxury rental blocks. This “brown-to-green” renovation strategy aligns with EU ESG mandates, unlocking access to preferential green building [https://www.realestate-lisbon.com/professionals/constructors-green-building] financing terms. For a comprehensive view of current Lisbon market insights [https://www.realestate-lisbon.com/market-insights], our dedicated section tracks yields and transaction volumes in real time.
Market Intelligence: Unlike residential units where bulk acquisition typically generates purchase discounts, whole-block acquisition in Baixa now commands a control premium. Unified ownership enables efficient management, consistent branding, and the operational flexibility to rotate between short-term tourist lettings and medium-term corporate relocations as regulatory conditions evolve.
### Branded Residences: The Lock-Up-and-Leave Premium
Lisbon is experiencing accelerating demand for Branded Residences, properties managed under hotel chain brands (Hyatt, Marriott) or luxury fashion houses (Missoni). This sector is forecast to grow 150% over the next 5 years.
Key Insight: For the globally mobile HNWI, the traditional Lisbon apartment lacks one critical feature: service continuity during owner absence. Branded residences address this through 24/7 concierge, security, and property management, plus rental pool models enabling hotel operators to manage short-term lets when owners are absent. These units trade at a 20–30% premium over comparable non-branded luxury stock, justified in 2026 by net yield potential of 3–5% and elimination of operational management burden. Luxury property specialists [https://www.realestate-lisbon.com/professionals/real-estate-agents-luxury-properties] active in this segment maintain direct access to branded residence inventory before public release. Use our ROI & Rental Yield Calculator [https://www.realestate-lisbon.com/calculators/investment-analyzer] to model branded residence returns against your capital allocation.
[Image: Prime furnished rental apartment in Chiado, Lisbon — 10 to 25 day absorption with sight-unseen international offers standard in 2026]
## Rental Market Dynamics: Velocity and Yield
The Lisbon rental market has decoupled from domestic wage realities. It is now correlated with international demand from digital nomads, corporate relocations, and NHR 2.0 beneficiaries.
Market Intelligence: Prime rentals in Chiado [https://www.realestate-lisbon.com/lisbon/chiado], Príncipe Real, and Estrela let within 10–25 days in 2026. In hyper-desirable streets, sight-unseen offers from US and UK tenants are standard for quality furnished stock. The “More Housing” package's restrictions on new Alojamento Local licenses in containment areas have not generated the anticipated flood of long-term rental supply. Owners have instead migrated to mid-term rentals (1–12 months) to circumvent long-term tenant protection legislation. Our Rental Yield Calculator [https://www.realestate-lisbon.com/calculators/rental-yield] can help model returns across both mid-term and long-term holding strategies.
Due Diligence: The 2026 rent adjustment coefficient is capped at 2.24% for continuing contracts. This creates a structurally perverse incentive: landlords are motivated to rotate tenants at contract end to reset rents to market rates, further compressing days-on-market metrics. Foreign tenants without Portuguese credit history or guarantors are commonly required to provide 6–12 months of rent upfront, a cash-flow accelerant for investors that effectively de-risks the first operating year. For a full breakdown of investment risks in the Lisbon rental market [https://www.realestate-lisbon.com/buying-guide/investment-risks], including regulatory exposure, see our dedicated guide.
## Insider Perspective: What the Data Doesn't Show
The headline metrics of the 2026 Lisbon market, 4.75% prime yields, sub-25-day rental absorption, 150% branded residence growth forecast, describe outcomes. They do not describe the mechanisms through which capital actually transacts at the top of the market.
Market Intelligence: In the ultra-prime segment above €4 million, relationship architecture precedes transaction architecture. Brokers operating the “private list” economy on Avenida da Liberdade do not respond to inbound inquiries from unknown parties, access is granted through introductions from institutional intermediaries (private banks, family office networks, Portuguese legal firms with established seller relationships). Foreign buyers who approach Lisbon's top-tier market through public portals are, by definition, accessing the secondary market. Real estate agents specializing in international clients [https://www.realestate-lisbon.com/professionals/real-estate-agents-international-clients] provide the critical introduction layer into this off-market ecosystem.
Professional Coordination: For HNWI buyers targeting the €3M–€10M segment, the recommended sequencing is: engage a buy-side advisory mandate (Week 1), initiate Portuguese legal counsel for SPV due diligence capability (Week 2), and coordinate pre-arrival tax planning with a cross-border specialist before any offer is made. This sequencing compresses transaction timelines from 150–180 days to 90–110 days by eliminating structural holdups at the due diligence phase. Review our legal issues in Lisbon property acquisition [https://www.realestate-lisbon.com/buying-guide/legal-issues] for the critical SPV-specific considerations.
Regulatory Nuance: The DGPC licensing process for palace restorations in Lapa is frequently underestimated by first-time buyers. Approval timelines for architectural interventions in Grade A heritage buildings range 18–36 months and are sensitive to the identity and track record of the appointed architect. Engaging a Portuguese architect with documented DGPC approval history reduces licensing risk materially, and this factor is not priced into shell acquisition costs at the €4,000–€6,000/sqm entry level. Our directory of traditional Portuguese architecture specialists [https://www.realestate-lisbon.com/professionals/architects-traditional-portuguese-architecture] includes firms with DGPC-approved project portfolios.
## Investment Considerations & Risk Factors
**Market Volatility:** Lisbon luxury property (€1M+) faces quarterly price fluctuations driven by ECB rate adjustments and shifts in international buyer sentiment. Yield compression has been persistent since 2020 and is not guaranteed to reverse on any predictable timeline.
**Holding Cost Reality:** Annual Portuguese property ownership costs, IMI (0.3–0.8% of assessed value annually), condominium fees (€150–600/month for luxury developments), insurance, and maintenance, typically total €45,000–75,000 for a €2M property. These costs are incurred regardless of rental income or capital appreciation. Use our True Cost Calculator [https://www.realestate-lisbon.com/calculators/true-cost] to model the full ownership cost envelope before committing capital.
**Regulatory Evolution:** Portugal's Golden Visa, NHR program, and Alojamento Local licensing have undergone material changes four times between 2023 and 2025. Future policy shifts remain possible as successive governments balance foreign investment attraction against domestic housing affordability pressure. The fund route for Golden Visa is currently stable but not permanently guaranteed. Our regulatory and legal frameworks blog [https://www.realestate-lisbon.com/blog/regulatory-legal-frameworks] tracks these developments in real time.
**Exit Liquidity:** Properties above €1M in Lisbon average 120–180 days to sale versus 60–90 days in mid-market segments. The ultra-prime segment (€4M+) has historically longer absorption periods due to the concentrated buyer pool. Palace shell investments add 2–4 years of restoration illiquidity before the exit can be executed.
**Currency Exposure:** Non-EU buyers face EUR/USD and EUR/GBP exchange rate risk. A 10% currency move represents €100,000 on a €1M acquisition, a material sensitivity for US and UK buyers deploying capital cross-border.
## Privacy & Transaction Security
All client consultations and transactions maintain strict confidentiality protocols:
### Discretion Standards
Off-market property access via private broker network (no public listing exposure), encrypted communication channels for all financial documentation, NDA-protected seller negotiations and due diligence processes, secure title verification through vetted Portuguese legal partners [https://www.realestate-lisbon.com/real-estate-lawyers] only. No client information shared with third parties without explicit written consent.
**GDPR Compliance:** All data handling follows Portuguese DPO-certified protocols with EU data residency guarantees.
## Common Due Diligence Oversights
### Conflating Golden Visa Physical Presence with IFICI Tax Residency
The Golden Visa fund route requires only 7 days annual presence in Portugal. IFICI (NHR 2.0) tax residency requires 183 days or registered residence with intent to stay. Investors who deploy €500,000 into a qualifying fund expecting automatic access to the 20% flat income tax rate without establishing full Portuguese tax residency are misreading the regulatory framework. These are separate legal processes requiring separate compliance tracks. Our guide on Golden Visa alternatives [https://www.realestate-lisbon.com/guides/golden-visa-alternatives-in-lisbon-a-2025-buyers-guide] clarifies the distinction between residency-by-investment and tax residency in detail.
### Underestimating SPV Due Diligence Complexity
Share deals on Avenida da Liberdade and Lapa avoid IMT/Stamp Duty costs but transfer all historical liabilities of the SPV to the buyer. Undisclosed debt, outstanding municipal licensing fees, or unresolved heritage disputes attached to the vehicle are not visible in surface-level property due diligence. Forensic legal review of SPV corporate history, including creditor searches, planning records, and notary archives, is non-negotiable in these transactions and adds 3–6 weeks to timelines. Engage property acquisition legal specialists [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-property-acquisition] experienced in SPV forensic review from the outset.
### Trusting Generic NHR Advisors for US-Specific Structures
The US tax overlay on Portuguese residency planning requires specialists in both jurisdictions simultaneously. PFIC classification of Golden Visa funds, trust recognition conflicts, and FBAR/FATCA reporting obligations are not addressed in standard Portuguese tax advisory. US-Portuguese tax planning requires parallel coordination between Portuguese fiscal representatives and US CPAs with international structuring experience. Our directory of English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants] includes firms with documented US-Portuguese dual-jurisdiction experience.
### Ignoring Pre-Arrival Tax Residency Timing
The transition from UK or US tax residency to Portuguese residency can trigger exit taxes, accelerated capital gains recognition, or inadvertent dual residency in the departure country if the departure year is not structured precisely. Pre-arrival planning should begin 12–18 months before the intended move date to allow for portfolio repositioning, trust restructuring if applicable, and OECD treaty analysis [https://www.oecd.org].
## Strategic Implementation Steps
### Immediate Actions (Week 1–2)
**Capital Structure Review:** Engage cross-border tax specialist to assess NHR 2.0/IFICI eligibility, PFIC exposure in targeted Golden Visa funds, and trust compatibility with Portuguese Civil Law
**Buy-Side Mandate:** Initiate relationship with off-market advisory firm to access investment property specialists [https://www.realestate-lisbon.com/professionals/real-estate-agents-investment-properties] and private inventory above €3M before public portal search
**NIF Application:** Begin Portuguese tax number application (4–6 week timeline, required before any property offer or fund subscription)
### Due Diligence Phase (Week 3–8)
**Legal Counsel:** Retain international property law specialists [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-international-property-law] with SPV due diligence experience for transactions in the €1M+ segment
**Fund Selection:** If pursuing Golden Visa fund route, request PFIC Annual Information Statement capability confirmation and review exit track record of fund manager
**Lda Incorporation:** If targeting NHR 2.0, engage Portuguese corporate lawyer and accountant for proprietary company setup under qualifying CAE codes
### Transaction Execution (Week 9–16)
**CPCV Structuring:** Negotiate promissory contract with contingencies for fiscal residency clearance and SPV verification where applicable. Our CPCV vs Escritura guide [https://www.realestate-lisbon.com/guides/cpcv-vs-escritura-in-lisbon-a-buyers-legal-guide] explains the legal stages of Portuguese property acquisition.
**Fund Subscription:** Complete KYC documentation for Golden Visa fund subscription (8–12 weeks for AIMA application processing)
**Funding Coordination:** Arrange international wire transfers with 5–7 business day lead time and full AML documentation. Use our IMT Tax Calculator [https://www.realestate-lisbon.com/calculators/imt] to model the final transaction tax exposure before committing.
## Frequently Asked Questions
What replaced the Golden Visa real estate route after October 2023?
CMVM-regulated investment funds became the primary Golden Visa pathway after October 2023. Investors subscribe to Portuguese venture capital funds (€500,000 minimum) that finance commercial entities in hospitality or logistics, qualifying under the “capitalization of commercial entities” provision. Major fund managers including Mercan offer buyback agreements timed to the 5-year residency and 6-year citizenship timelines. For professional guidance on fund selection, consult our Golden Visa accounting specialists [https://www.realestate-lisbon.com/professionals/accountants-golden-visa-accounting].
How does NHR 2.0 (IFICI) differ from the original NHR regime?
IFICI (effective January 2024) restricts eligibility to high value-added activities and requires active economic participation rather than passive residency. It provides a 20% flat income tax rate for 10 years. Foreign pension income, which was broadly exempt under original NHR, now faces progressive rates. Capital gains from Portuguese real estate are taxed at 50% of gain at progressive rates for IFICI residents versus the NHR-era broad exemptions. Read the detailed comparison in our NHR vs IFICI tax guide [https://www.realestate-lisbon.com/guides/nhr-vs-ifici-in-lisbon-a-2025-tax-guide-for-buyers].
What is a "share deal" in Lisbon real estate, and who should use it?
A share deal involves acquiring the Single Purpose Vehicle (SPV) that owns a property rather than buying the asset directly. This structure can mitigate IMT and Stamp Duty, which combined can exceed 7–8% of purchase price on high-value transactions. Share deals require extensive SPV due diligence and are appropriate only for sophisticated buyers with experienced legal counsel. They are most common in off-market ultra-prime transactions above €4 million. Engage due diligence legal specialists [https://www.realestate-lisbon.com/professionals/real-estate-lawyers-due-diligence] before proceeding with any SPV acquisition.
What are the PFIC implications for US investors in Portuguese Golden Visa funds?
US investors must confirm that target funds provide a PFIC Annual Information Statement enabling a Qualified Electing Fund (QEF) election. Without this, gains are subject to the IRS excess distribution regime, which applies punitive interest charges and ordinary income rates. “American-friendly” Golden Visa fund managers explicitly offer QEF-compatible reporting, this should be a non-negotiable due diligence requirement before fund subscription. Consult with English-speaking accountants [https://www.realestate-lisbon.com/english-speaking-accountants] experienced in US-Portuguese dual-jurisdiction taxation.
Can a Family Office buy an entire residential block in Lisbon?
Whole-block acquisitions in Baixa [https://www.realestate-lisbon.com/lisbon/baixa], Chiado [https://www.realestate-lisbon.com/lisbon/chiado], and Arroios have become a preferred strategy for Family Offices pursuing PRS (Private Rented Sector) long-term holds. These transactions typically command a control premium over unit-level pricing due to unified management potential. Mixed-use blocks (retail ground floor plus residential/office upper floors) offer repositioning flexibility aligned with EU ESG mandates and qualify for green financing incentives.
What is the realistic timeline for restoring a Lapa palace shell?
Architectural restoration of a heritage-listed Lapa [https://www.realestate-lisbon.com/lisbon/lapa] palace typically spans 3–5 years from acquisition to completion: 18–36 months for DGPC and municipal licensing, followed by 18–24 months of physical construction. Buyers should model full illiquidity through this period. The financial case depends on acquisition cost, restoration quality (museum-grade finishes require €2,500–€3,500/sqm), and exit pricing (€12,000–€16,000/sqm for completed architecturally significant assets). Review our guide on maintenance and restoration costs [https://www.realestate-lisbon.com/buying-guide/maintenance-costs] for full budgeting context.
How does Lisbon's rental market protect investors from vacancy risk in 2026?
Prime rental stock in Chiado, Príncipe Real, and Estrela absorbs within 10–25 days in 2026. Tenant demand from international tech workers, corporate relocations, and NHR 2.0 beneficiaries has decoupled from domestic wage sensitivity. Foreign tenants without Portuguese credit history are routinely required to prepay 6–12 months of rent, providing investors with immediate cash flow security. Vacancy risk for prime-grade furnished stock is structurally low relative to comparable European cities. Model your specific scenario with our Rental Yield Calculator [https://www.realestate-lisbon.com/calculators/rental-yield].
Data sourced from INE Portugal [https://www.ine.pt], Knight Frank [https://knightfrank.com], and historical transaction records. Updated February 2026. This article is for informational purposes only and does not constitute investment, tax, or legal advice. Consult qualified professionals before making investment decisions. Explore more market intelligence [https://www.realestate-lisbon.com/blog/market-intelligence-analysis] or view Lisbon market insights [https://www.realestate-lisbon.com/market-insights].